RoboMacro ResearchAlso todaySee the Commodities Daily

Brazil Macro Daily(Beta Mode)

November 17, 2026 robomacro.com

Real Slumps as Growth Falters, Rates Spike

Bovespa169,295.00-1.83%
USD/BRL5.78+2.02%
EUR/BRL6.36+1.89%
Vale10.46-6.77%

Market Snapshot

AssetLevelChange
Bovespa169,295.00-1.83%
USD/BRL5.78+2.02%
EUR/BRL6.36+1.89%
Vale10.46-6.77%
Petrobras17.30-5.67%
WTI Crude85.46-0.30%
Gold3,874.80+0.57%
Bitcoin64,175.13-1.05%
Brazil 5Y Govt Yield15.20%+17 bp
Brazil 10Y Govt Yield15.30%+21 bp

Prior Economic Events

Data Prior Cons Actual
BCB Focus Market Readout---
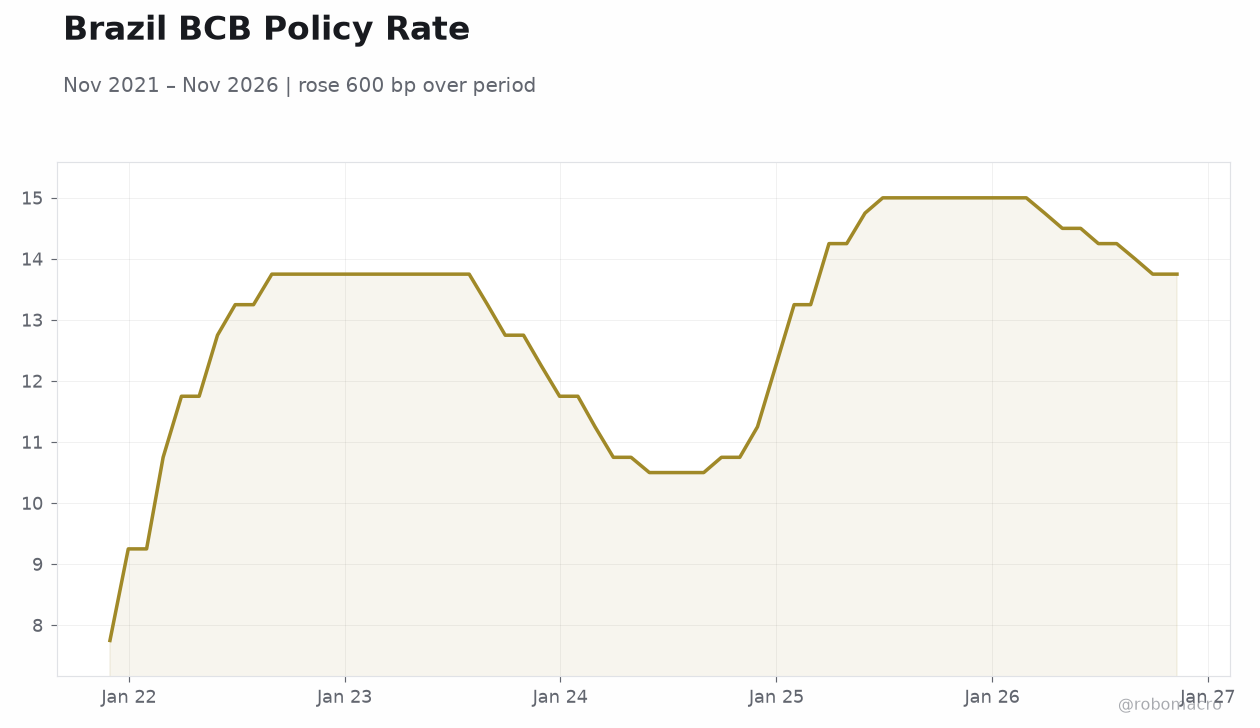
Brazil BCB Policy RateBrazil BCB Policy Rate | Type: macro_line | Policy Rate %: 13.75 (2026-11-10) | Range: 7.75–15 | Trend(5pt): 7.75,13.75,10.5,15,13.75

Today's Economic Events

Data Prior Cons Time
No events available
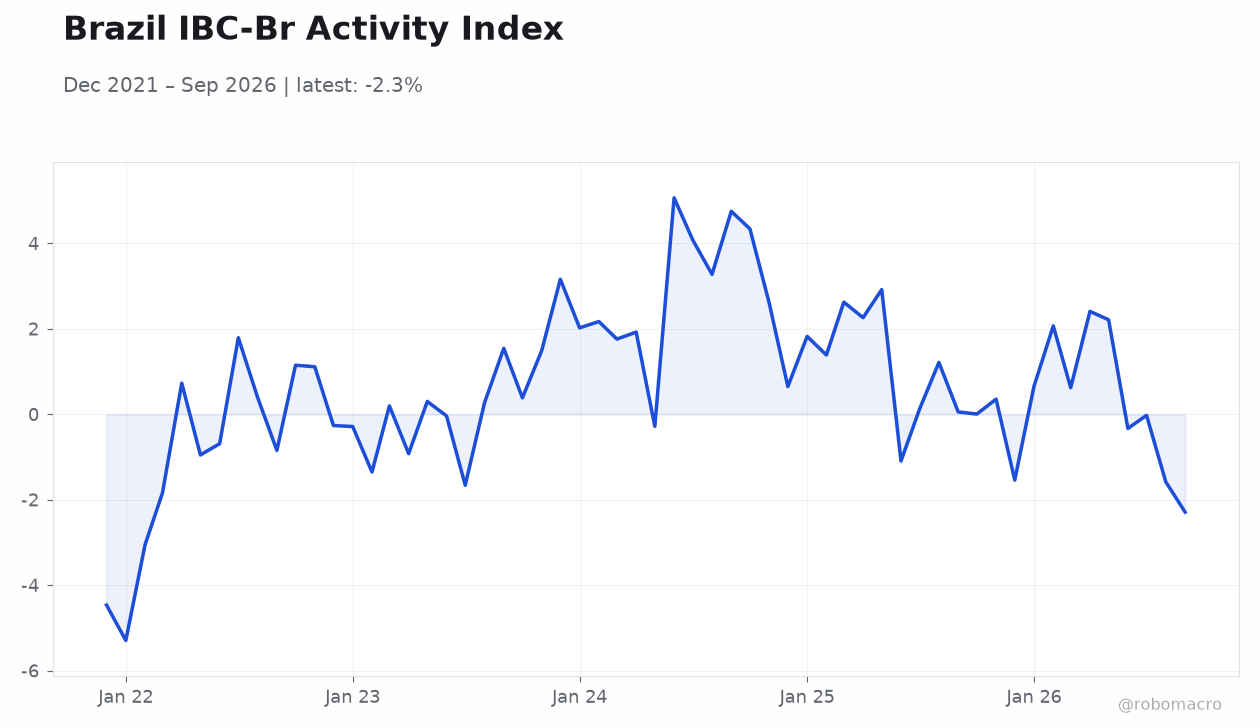
  • Brazil's IBC-Br activity index fell 0.2% in September, confirming a broad loss of economic momentum and triggering a sharp cross-asset selloff.
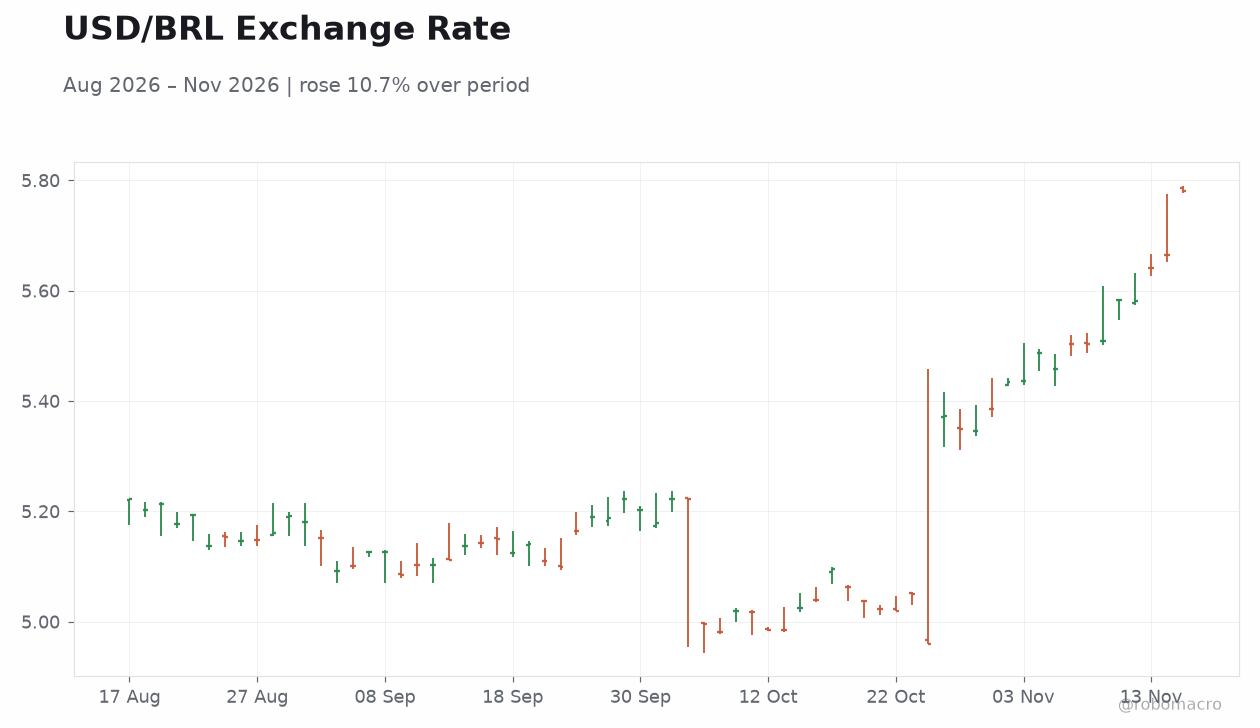
  • The real plunged to a 19-month low, with USD/BRL surging 2.02% to 5.78, while the Bovespa dropped 1.83% to 169,295.
  • Domestic yields spiked sharply — the 10-year rose 21 bp to 15.30% and the 5-year added 17 bp to 15.20% — as fiscal and inflation concerns resurfaced.

Yesterday's Recap

Brazilian markets came under heavy pressure yesterday following the release of the BCB Focus Market Readout and the IBC-Br activity print, which showed a 0.2% contraction in September. The real bore the brunt of the adjustment, weakening 2.02% against the dollar to 5.78 and hitting a 19-month low, while EUR/BRL climbed 1.89% to 6.36. Equities followed the currency lower, with the Bovespa shedding 1.83% to close at 169,295.

Commodity-linked names led the decline: Vale collapsed 6.77% to 10.46 and Petrobras fell 5.67% to 17.30, amplifying the index drag. The fixed-income market priced in a more cautious outlook, pushing the 10-year government yield up 21 bp to 15.30% and the 5-year up 17 bp to 15.20%. The selloff was broad-based across LatAm, with Brazil leading regional weakness as investors reassessed the growth trajectory.

The Day Ahead

The calendar is empty for today and tomorrow, leaving markets to digest yesterday's activity shock and position ahead of the BCB's December 9 COPOM meeting. With no domestic data to anchor sentiment, price action will likely be driven by currency dynamics and global risk appetite. Traders will watch the real closely after its slide to a 19-month low, monitoring whether the BCB signals any concern through intervention or communication.

The steepening in the yield curve — with the 10-year at 15.30% — suggests the market is demanding a higher term premium amid fiscal uncertainty. Attention will also turn to commodity flows and iron ore pricing given Vale's sharp decline.

Other Economic Notes

The IBC-Br contraction reinforces a narrative of decelerating activity after a period of resilience, raising questions about the durability of Brazil's growth model heading into 2027. With CPI at 4.63% year-over-year, the disinflation process remains intact but the growth slowdown complicates the policy trade-off. Fiscal sustainability remains a central concern, as elevated real rates — the Selic at 13.75% — weigh on credit and investment.

↓ p.2
Page 1

Brazil Macro Daily(Beta Mode)

November 17, 2026 robomacro.com
Brazil IBC-Br Activity Index Brazil IBC-Br Activity Index | Type: macro_line | Industrial Production Index: -2.289 (2026-09-01) | Range: -5.294–5.066 | Trend(6pt): -4.466,-1.352,1.923,-1.095,-1.582,-2.289
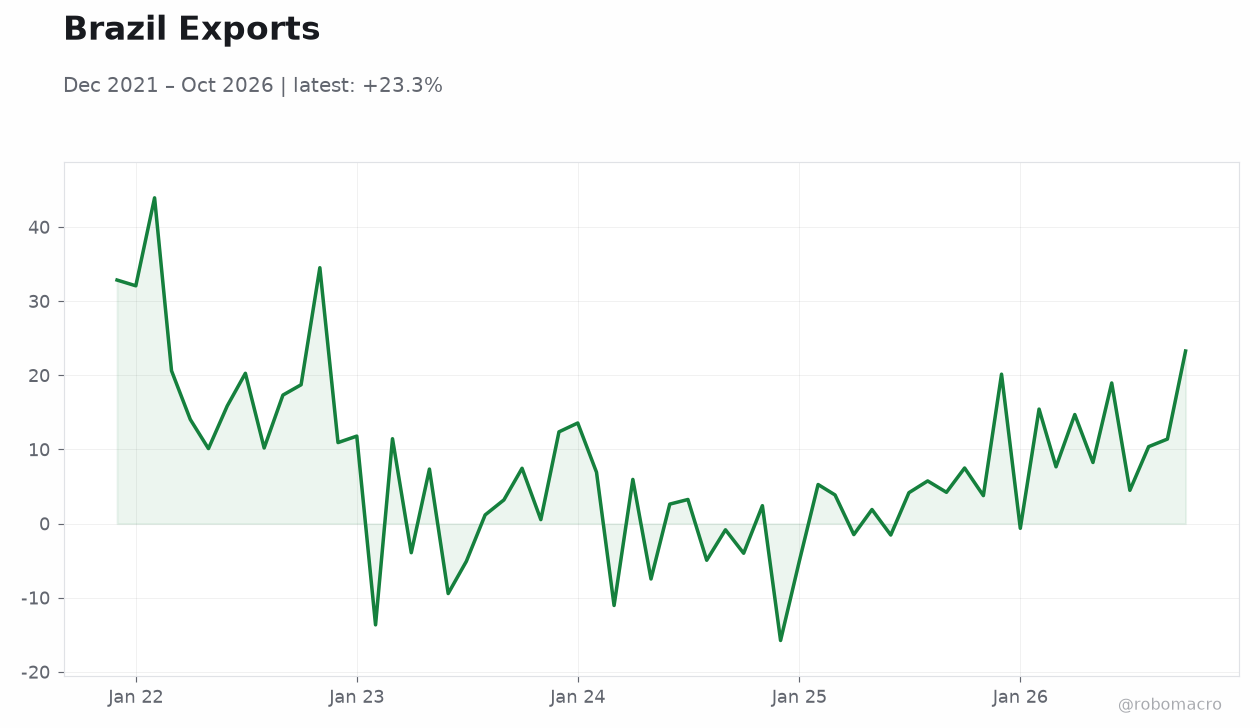
Brazil Exports Brazil Exports | Type: macro_line | Exports USD: 23.28 (2026-10-01) | Range: -15.76–43.94 | Trend(6pt): 32.86,-13.65,5.966,-1.536,10.39,23.28
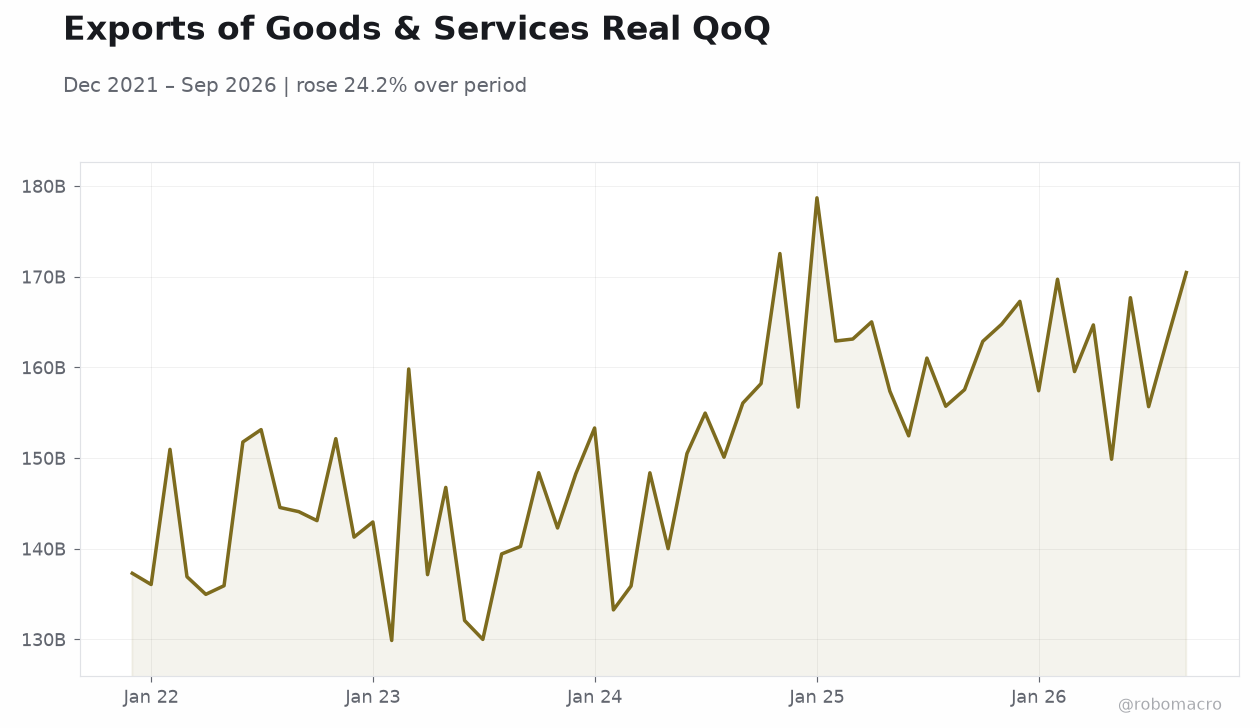
Exports of Goods & Services Real QoQ Exports of Goods & Services Real QoQ | Type: macro_line | Exports of Goods & Services Real QoQ: 1.705e+11 (2026-09-01) | Range: 1.299e+11–1.787e+11 | Trend(6pt): 1.373e+11,1.299e+11,1.484e+11,1.525e+11,1.632e+11,1.705e+11
USD/BRL Exchange Rate USD/BRL Exchange Rate | Type: market_hloc | USD/BRL: 5.781 (2026-11-17) | Range: 4.96–5.781 | Trend(6pt): 5.222,5.127,5.203,5.02,5.641,5.781

Other Economic Notes (continued)

The sharp equity selloff in commodity names reflects both global demand worries and idiosyncratic pressures, with Vale's 6.77% drop highlighting sensitivity to iron ore markets. The real's weakness, if sustained, could feed through to imported inflation and complicate the BCB's easing path.

Global Macro News

Global markets are grappling with a firmer dollar as Fed expectations shift, pressuring emerging-market currencies broadly — Indonesia's rupiah fell to a record low on the same dynamic. China raised its foreign-currency reserve requirement to curb yuan appreciation, a move that complicates the export outlook for commodity producers like Brazil. Goldman Sachs warned of a massive oil glut in 2027, with supply potentially exceeding demand by 2 million barrels daily — a bearish signal for Petrobras and the oil complex.

WTI crude edged down 0.30% to 85.46, while gold rose 0.57% to 3,874.80 as a safe-haven bid emerged. Bitcoin slipped 1.05% to 64,175, reflecting cautious risk sentiment. The MAS and Bundesbank tested cross-border digital currency settlement, underscoring ongoing financial infrastructure innovation.

These crosscurrents — a strong dollar, commodity demand uncertainty, and shifting Fed bets — are directly transmitted to Brazil through the currency and equity channels.

Sponsored by Arbitrage Search
Page 2

Brazil Macro Daily(Beta Mode)

November 17, 2026 robomacro.com

Continuation

BCB Watch

The BCB has held the Selic at 13.75% since its November 4 decision, following a 25 bp cut at the September 16 meeting from 14.00%. The committee's forward guidance remains data-dependent, and yesterday's weak IBC-Br print complicates the easing trajectory by suggesting activity is cooling faster than anticipated. With CPI at 4.63%, the BCB retains room to maneuver, but the real's slide to a 19-month low introduces a currency-inflation channel that could temper further cuts.

Markets are pricing a cautious approach ahead of the December 9 COPOM meeting, with the steep yield curve — 10-year at 15.30% — signaling skepticism about aggressive easing. The BCB's inflation-targeting framework remains the anchor, but fiscal noise and external volatility are testing credibility. Any future rate increase would be framed as a reversal of the September cut, not a new tightening cycle.

Sponsored by Arbitrage Search
Page 3