Brazil Macro Daily(Beta Mode)
BCB Hold Meets Global Risk-Off
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 169,817.00 | +0.31% |
| USD/BRL | 5.77 | -0.21% |
| EUR/BRL | 6.33 | -0.35% |
| Vale | 10.42 | -0.38% |
| Petrobras | 17.41 | +0.64% |
| WTI Crude | 82.72 | -3.83% |
| Gold | 3,771.70 | -2.39% |
| Bitcoin | 64,680.95 | -0.33% |
| Brazil 5Y Govt Yield | 15.11% | -9 bp |
| Brazil 10Y Govt Yield | 15.21% | -9 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BCB Focus Market Readout | - | - | "" |
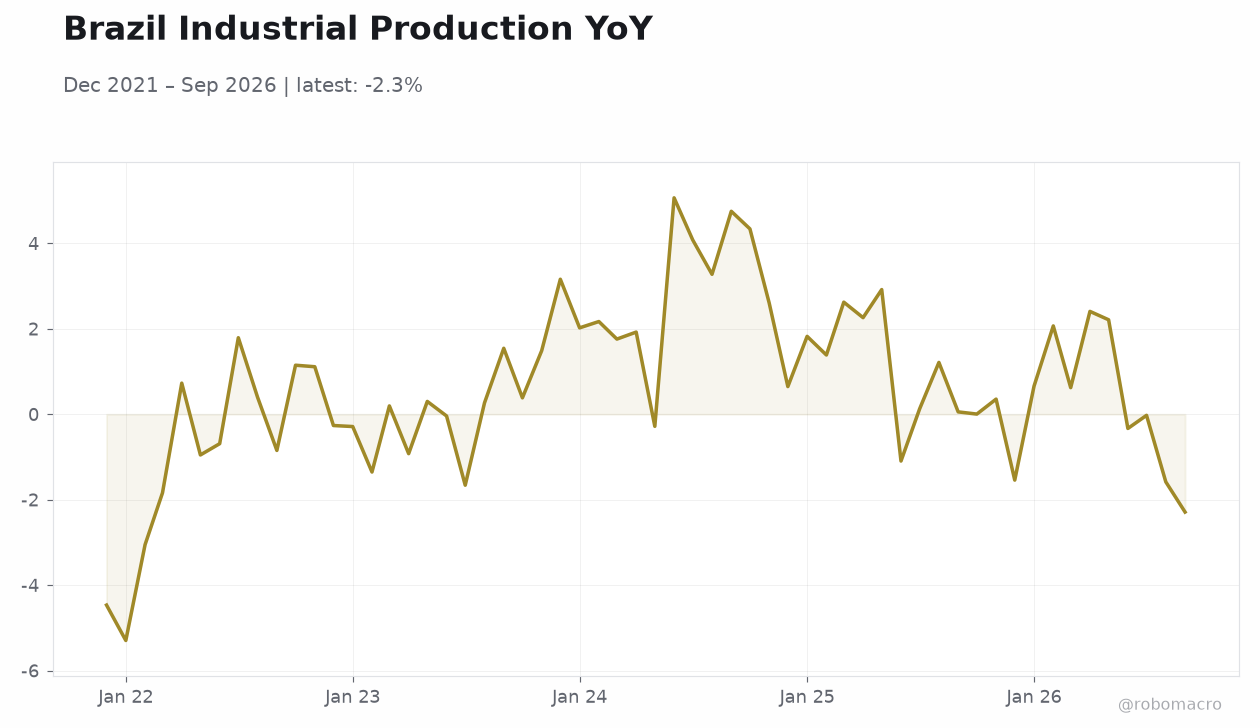 Brazil Industrial Production YoY | Type: macro_line | IP YoY (%): -2.289 (2026-09-01) | Range: -5.294–5.066 | Trend(6pt): -4.466,-1.352,1.923,-1.095,-1.582,-2.289
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Brazilian assets diverged from a sharp global risk-off move, with local yields easing 9 bp across the curve even as commodities sold off hard
- The BCB Focus survey was the sole scheduled release; no Brazilian data prints on deck for today or tomorrow
- Citi projects continued real depreciation but sees USD/BRL at 5.50 by 2027; B3 moves to include Brazil-domiciled companies listed abroad in the Ibovespa
Yesterday's Recap
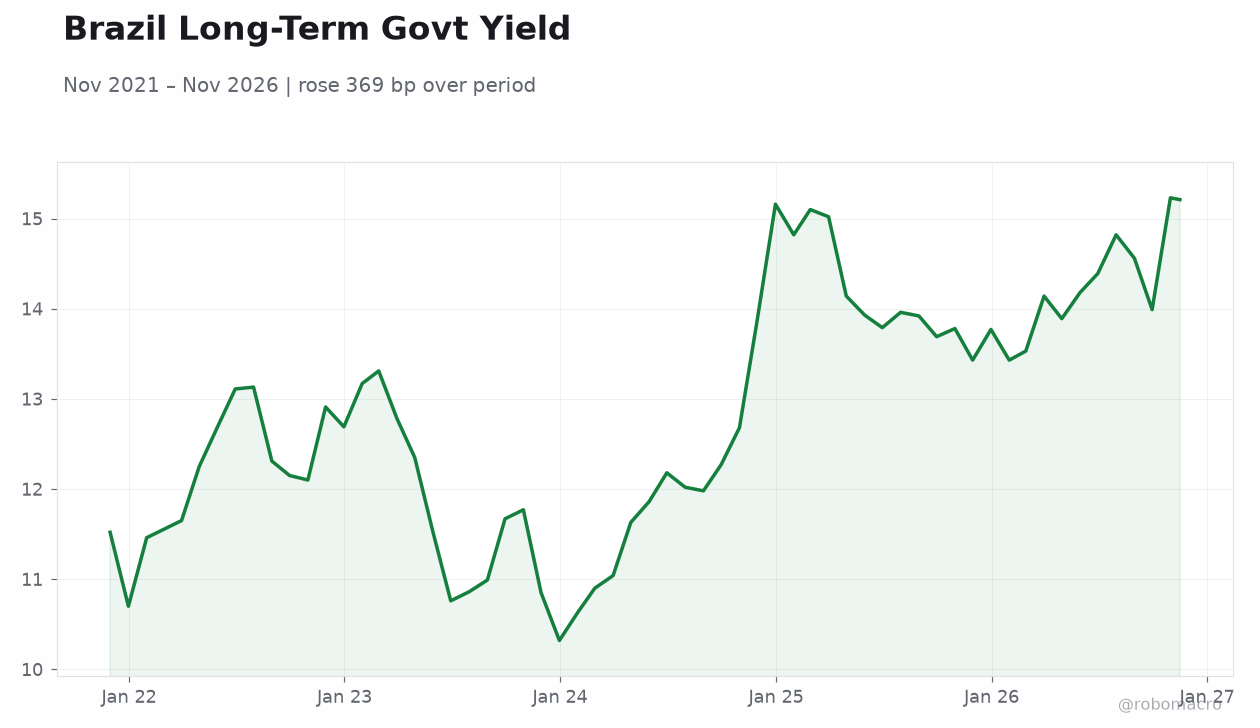
The BCB Focus Market Readout was the only scheduled Brazilian release on November 16, with the survey's median projections holding the spotlight for local rate expectations. Brazilian fixed income rallied against the global grain: the 5-year yield eased 9 bp to 15.11% and the 10-year fell 9 bp to 15.21%, a notable divergence from the risk-off tone abroad. The Ibovespa edged up 0.31% to 169,817, with Petrobras (+0.64%) outperforming while Vale slipped 0.38% at 10.42.
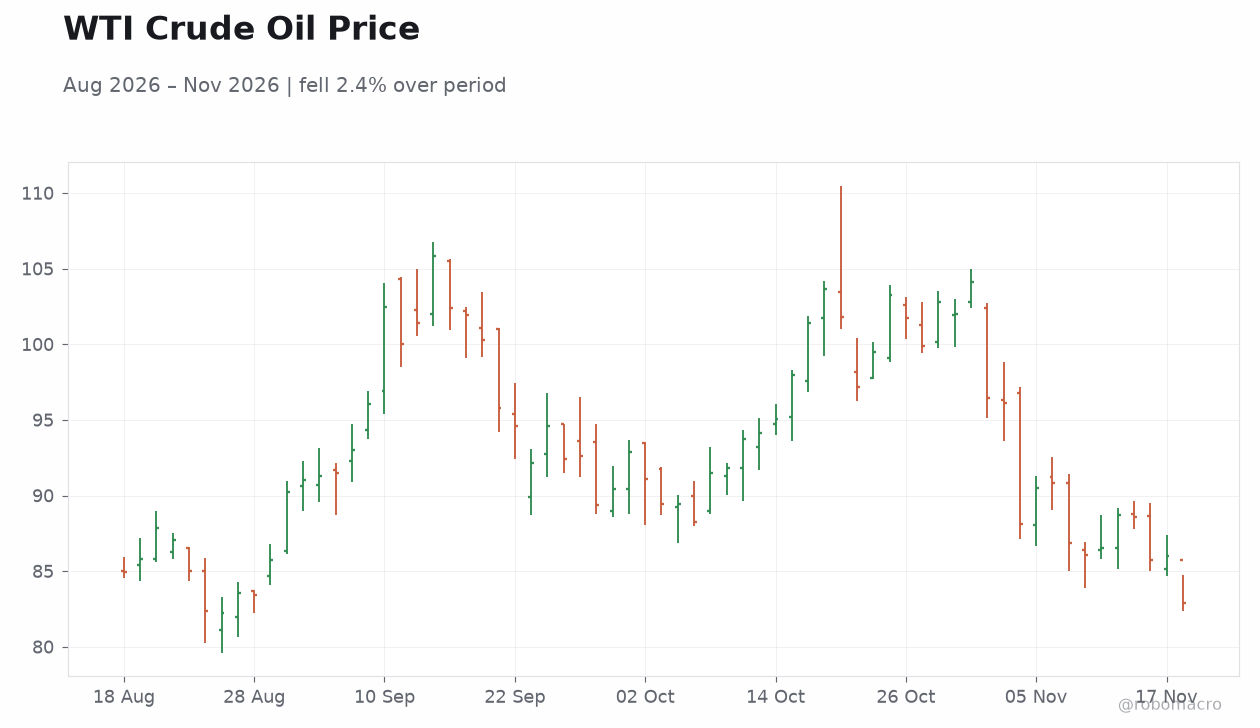
USD/BRL traded at 5.77, down 0.21%, and EUR/BRL at 6.33, down 0.35%, showing the real firming modestly despite the dollar's broader strength. The divergence was stark against commodities: WTI crude collapsed 3.83% to 82.72 and gold dropped 2.39% to 3,771.70, yet Brazilian local rates and the currency held their ground. Bitcoin slipped 0.33% to 64,680.95, rounding out a session where Brazil stood apart from the global de-risking.
The Day Ahead
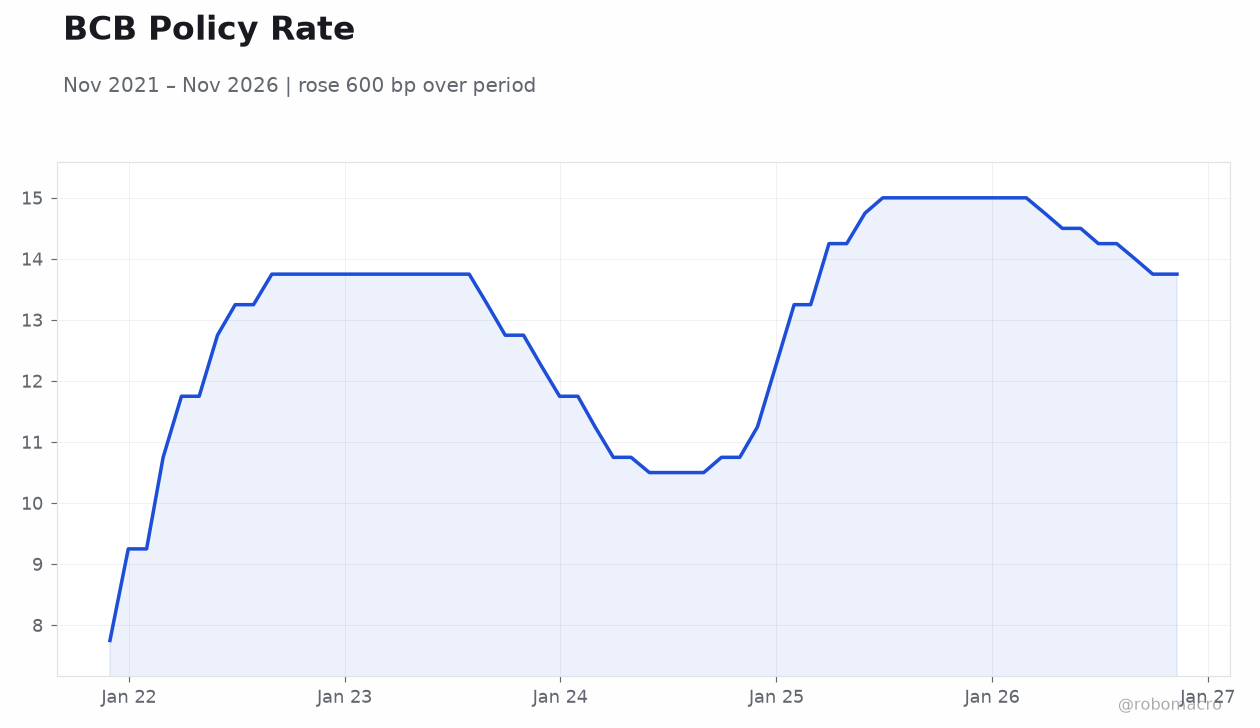
No Brazilian economic releases are scheduled for today or tomorrow, leaving the market to trade off positioning, external risk sentiment, and the prior session's local-rate rally. With the calendar empty, attention shifts to the BCB's communications cadence and the approach to the December 9 COPOM meeting. Flows will likely be driven by commodity price action — particularly the sharp oil selloff — and by global rates as the dollar firms against most EM currencies.
Local traders will watch whether the yield curve can hold its gains without fresh domestic catalysts, and whether the real's resilience persists against a strengthening greenback.
Other Economic Notes
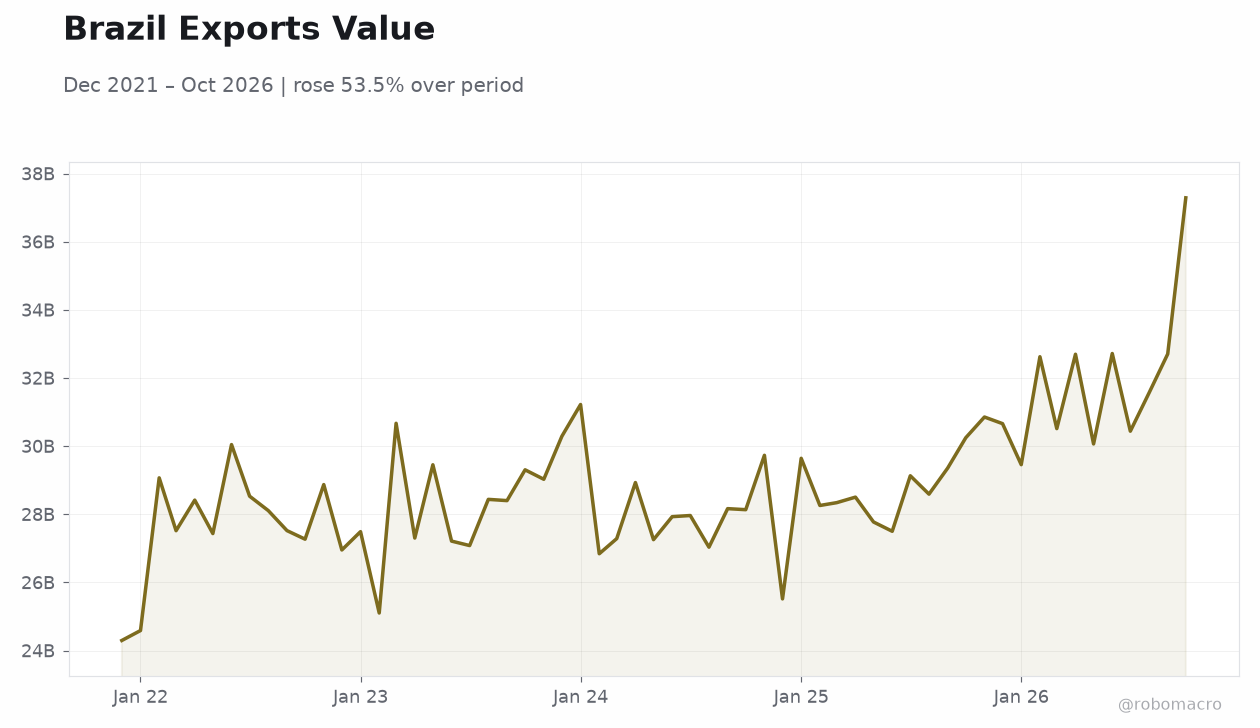
The B3 announcement that it will incorporate shares of Brazilian companies listed abroad into the benchmark equity index starting next year is a structural development worth monitoring — it could broaden the Ibovespa's investable universe and improve liquidity in a market the exchange itself describes as ailing. Citi's FX view sees continued real depreciation but projects USD/BRL at 5.50 by 2027, arguing carry trade alone is insufficient to sustain the currency — a call that sits uneasily with the real's firming yesterday. On the trade front, the Philippines is seeking wider agricultural market access to Brazil, a reminder of Brazil's expanding role as a global food supplier.
↓ p.2