Canada Macro Daily(Beta Mode)
Oil Rally, Trade Strains Frame Canada CPI Watch
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,697.50 | +0.54% |
| USD/CAD | 1.39 | +0.37% |
| EUR/CAD | 1.60 | -0.16% |
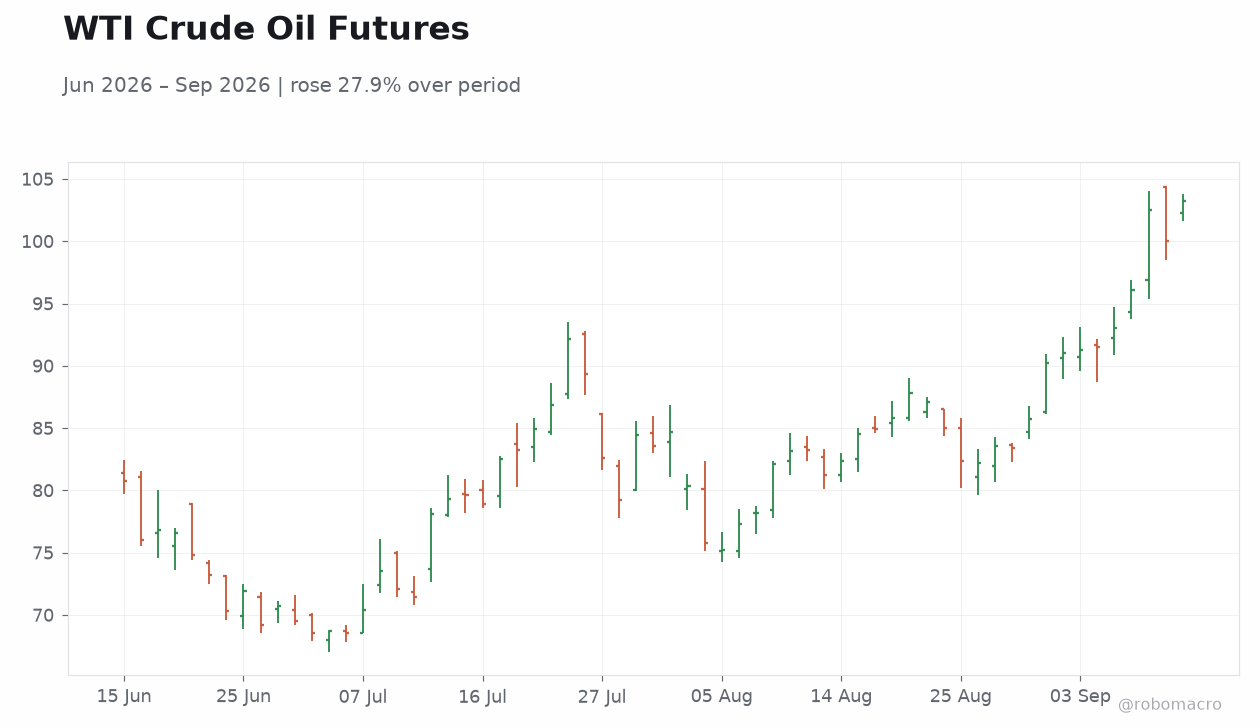
| WTI Crude | 103.13 | +3.08% |
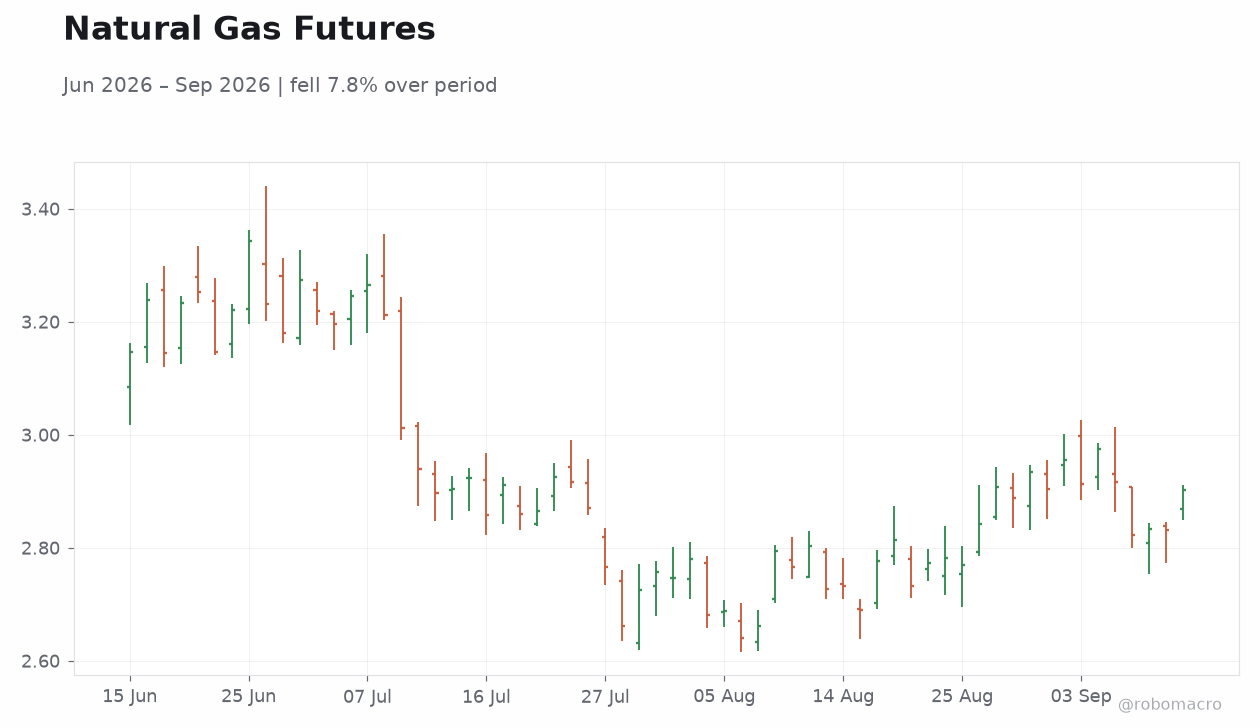
| Natural Gas | 2.90 | +2.58% |
| Gold | 4,336.20 | -0.69% |
| Brent Crude | 108.18 | +3.41% |
| Bitcoin | 77,766.55 | +1.21% |
| Canada 2Y Govt Yield | 2.27% | +1.00% |
| Canada 10Y Govt Yield | 3.42% | -3.43% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
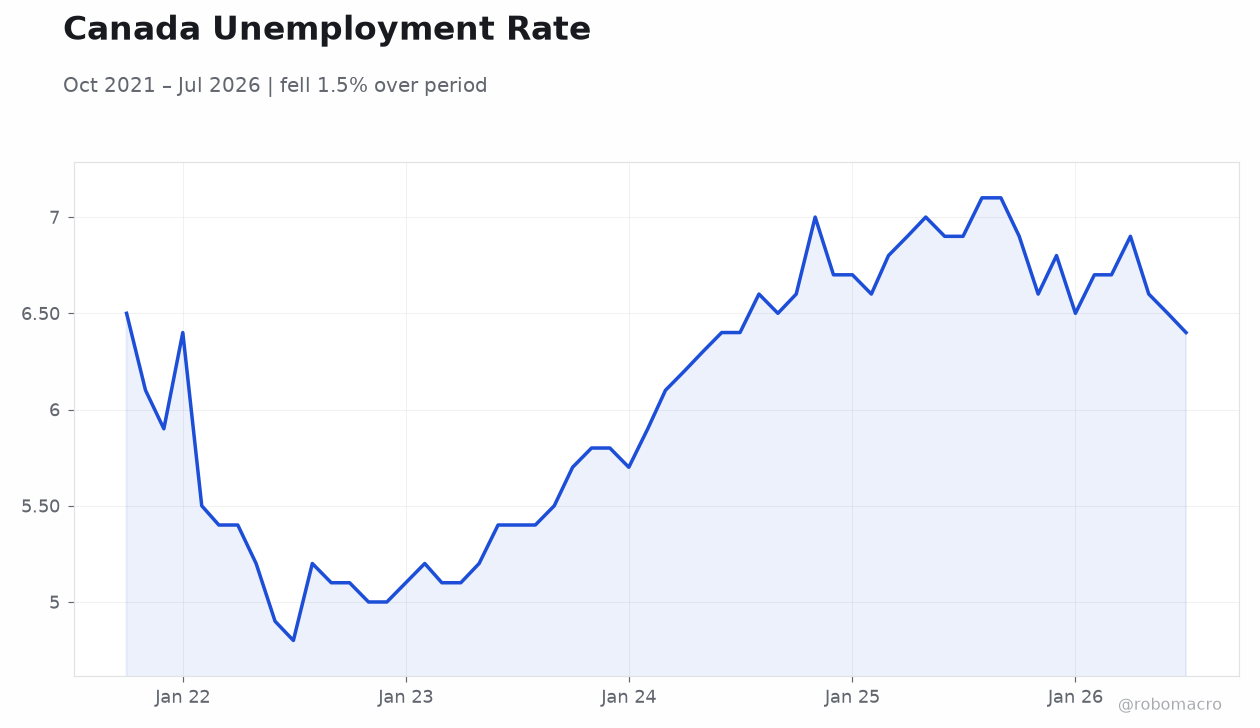
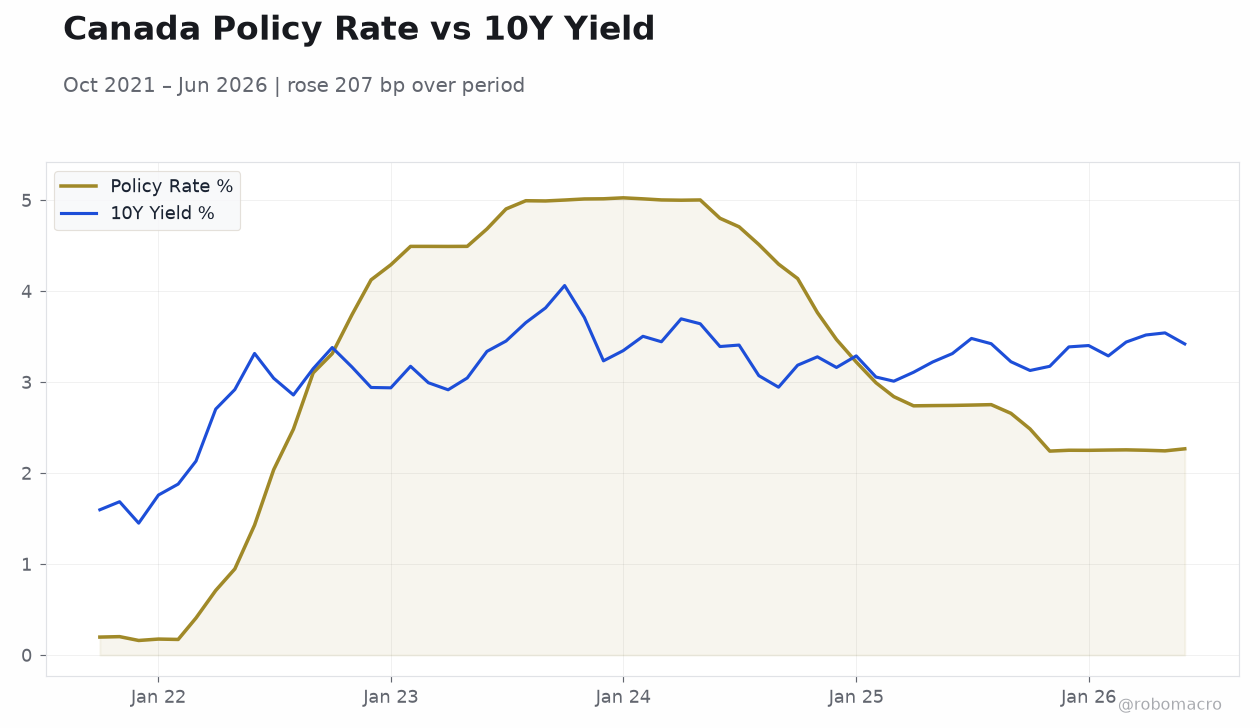 Canada Policy Rate vs 10Y Yield | Type: macro_line | Policy Rate %: 2.267 (2026-06-01) | Range: 0.1604–5.026 | Trend(5pt): 0.1977,4.125,5.015,2.74,2.267 | 10Y Yield %: 3.42 (2026-06-01) | Range: 1.45–4.062 | Trend(5pt): 1.597,2.942,3.504,3.109,3.42
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Year-over-Year | 3 | - | 04:30 |
| Core Inflation Rate Year-over-Year | 2.30 | - | 04:30 |
| Inflation Rate Month-over-Month | 0.50 | 0 | 04:30 |
| Wednesday (2026-09-16) | |||
| Housing Starts Level | 229,100 | 235,000 | 04:15 |
- August CPI figures due today with steady inflation expected
- S&P/TSX rises 0.54% while WTI crude jumps 3.08% to 103.13
- BoC holds policy rate at 2.25% amid US-Canada trade frictions
Yesterday's Recap
Equity and commodity markets advanced on September 13 with no Canadian economic releases scheduled. The S&P/TSX Composite closed at 35,697.50, up 0.54%. WTI Crude rose 3.08% to 103.13 and Brent Crude gained 3.41% to 108.18, while Natural Gas increased 2.58% to 2.90.
Bitcoin finished at 77,766.55, up 1.21%, and Gold declined 0.69% to 4,336.20. The Canadian dollar weakened, with USD/CAD at 1.39, up 0.37%, and EUR/CAD at 1.60, down 0.16%. Government bond yields moved in opposite directions: the 2-year yield rose 1.00% to 2.27% while the 10-year yield fell 3.43% to 3.42%.
Coverage focused on ongoing US-Canada trade tensions and domestic food inflation drivers rather than external policy shocks.
The Day Ahead
Statistics Canada will release August inflation data at 04:30 ET, including the Inflation Rate Year-over-Year, Core Inflation Rate Year-over-Year, and Inflation Rate Month-over-Month. These prints carry high impact and will shape near-term Bank of Canada expectations and CAD trading. Housing Starts are scheduled for September 16 with a consensus forecast of 235,000.
Market participants will monitor how the CPI outcome aligns with the prior 3.03% year-over-year reading and influences rate-hold probabilities. Energy price strength may provide additional support to the loonie if the data print softer than expected.
Other Economic Notes
Domestic factors continue to dominate Canadian food inflation discussions, with analysts pointing to supply-chain and regulatory issues inside Canada rather than US tariffs. Mark Carney has actively pitched Canadian assets to global investors despite the ongoing trade conflict with Washington. Bank of Montreal announced a $70 billion domestic commitment that could support credit growth and housing activity.
RBC hired Bank of America’s Dan Mills to lead Canada rates sales, signaling continued institutional focus on fixed-income markets. Broader commentary suggests the Bank of Canada should remain on hold while monitoring Federal Reserve actions.
Global Macro News
Oil prices jumped on supply concerns after reports of potential disruptions from the Persian Gulf and Saudi pipeline issues. ↓ p.2