Canada Macro Daily(Beta Mode)
Stable CPI Eases Near-Term Rate Pressure
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,582.10 | -0.34% |
| USD/CAD | 1.39 | +0.26% |
| EUR/CAD | 1.61 | -0.16% |
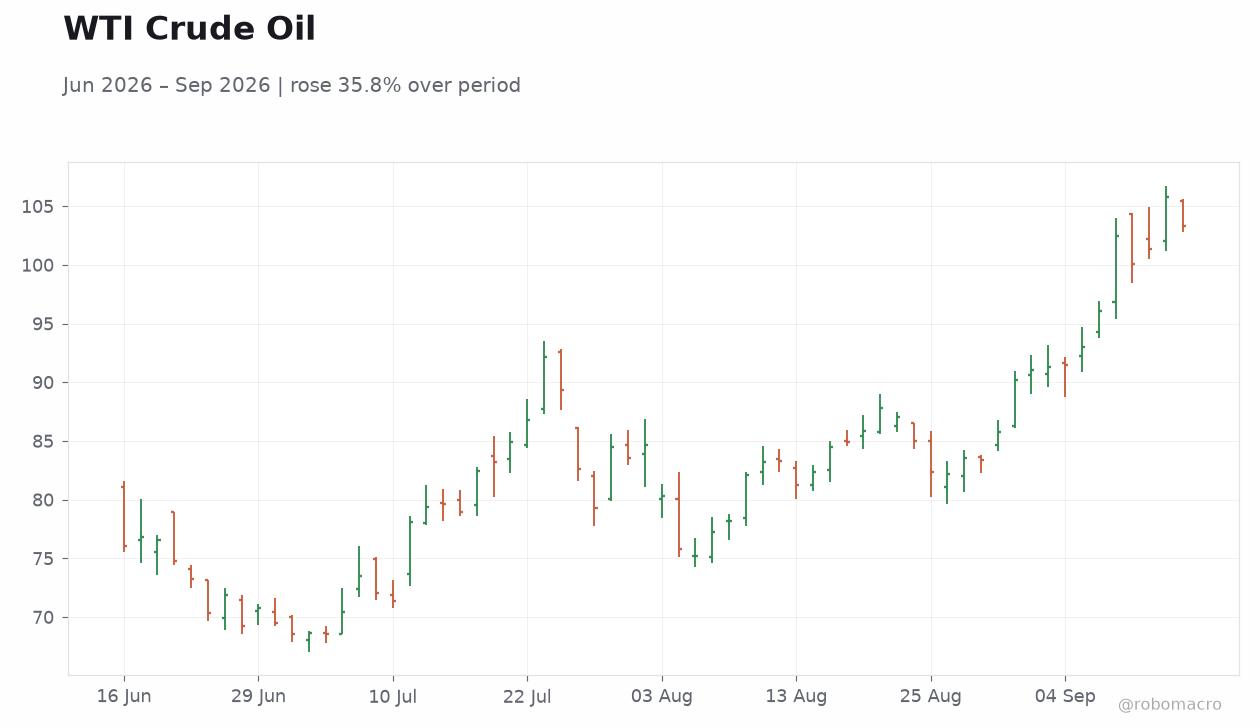
| WTI Crude | 103.22 | -2.47% |
| Natural Gas | 2.93 | +0.48% |
| Gold | 4,392.00 | +1.37% |
| Brent Crude | 107.02 | -1.59% |
| Bitcoin | 75,948.71 | +0.44% |
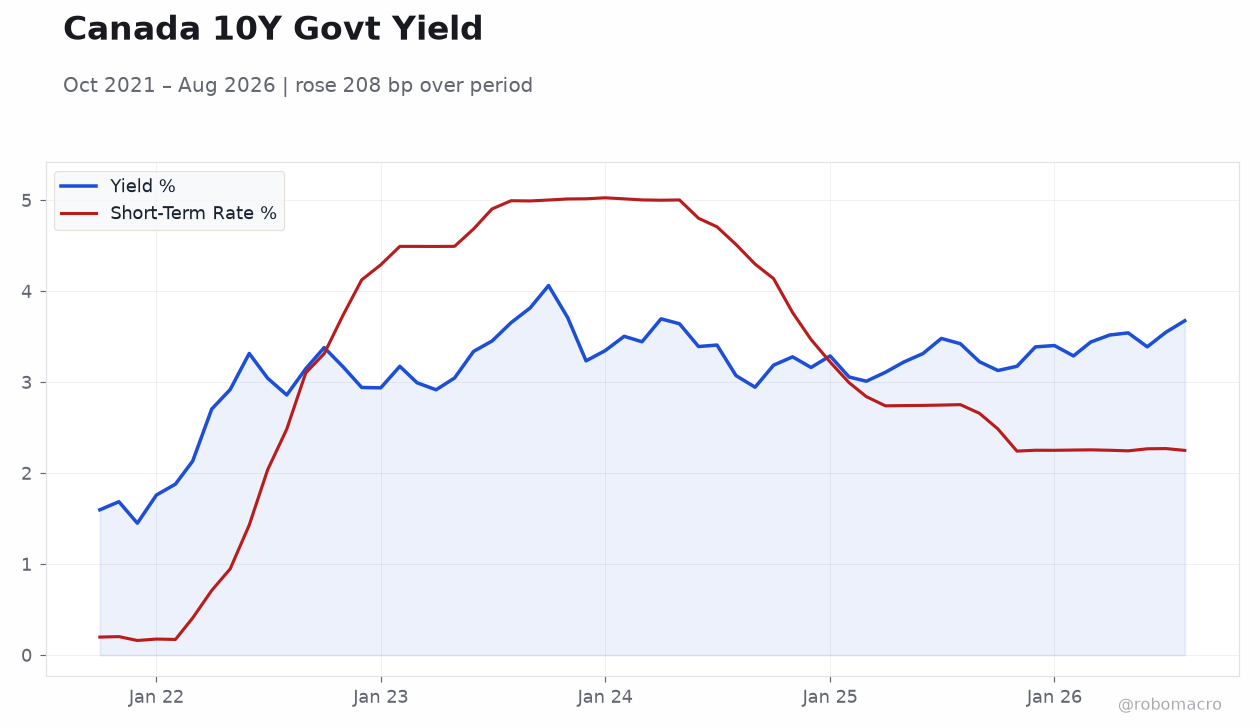
| Canada 2Y Govt Yield | 3.37% | +2 bp |
| Canada 10Y Govt Yield | 3.94% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 3 | 3 | 3 |
| Core Inflation Rate Year-over-Year | 2.30 | - | 2.40 |
| Inflation Rate Month-over-Month | 0.50 | 0 | -0.10 |
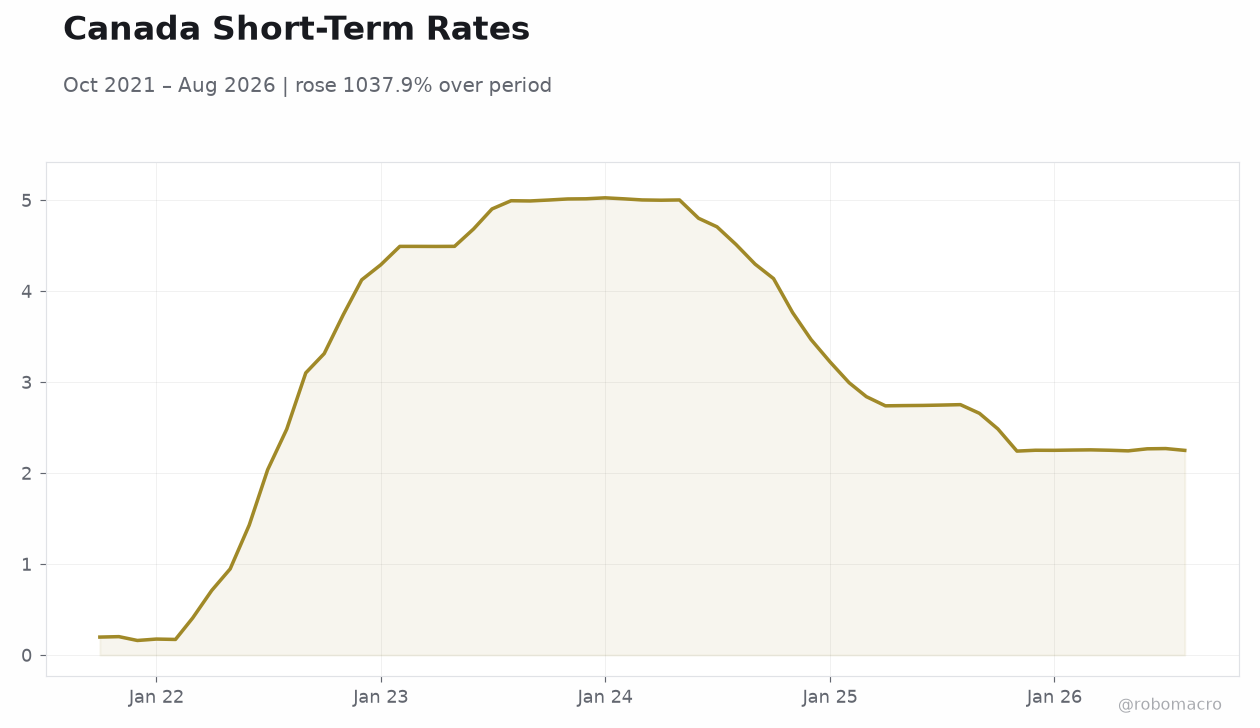 Canada Short-Term Rates | Type: macro_line | Rate %: 2.25 (2026-08-01) | Range: 0.1604–5.026 | Trend(6pt): 0.1977,4.125,5.015,2.74,2.267,2.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Housing Starts Level | 229,100 | 240,000 | 04:15 |
- Canadian CPI YoY held at 3.0% in line with consensus, while core rose to 2.4%.
- S&P/TSX fell 0.34% to 35,582.10 as WTI crude dropped 2.47% to 103.22.
- USD/CAD rose 0.26% to 1.39; Canada 2-year yield climbed 2 bp to 3.37%.
Yesterday's Recap
Canadian inflation data released on September 14 showed headline CPI YoY unchanged at 3.0%, matching both consensus and the prior reading. Core CPI YoY increased to 2.4% from 2.3%, while the month-over-month rate fell to -0.1% against a consensus of flat. The prints aligned with expectations and left near-term Bank of Canada policy views largely intact.
Equity markets reacted with the S&P/TSX Composite declining 0.34% to close at 35,582.10. USD/CAD advanced 0.26% to 1.39, reflecting modest Canadian dollar softening. Energy prices weighed on sentiment as WTI crude fell 2.47% to 103.22 and Brent declined 1.59% to 107.02.
The Canada 2-year government yield rose 2 bp to 3.37% while the 10-year eased 1 bp to 3.94%. Gold rose 1.37% to 4,392.00 and natural gas added 0.48% to 2.93, providing partial offsets in commodity-sensitive names.
The Day Ahead
Housing Starts for September are scheduled at 04:15 ET with consensus at 240,000 units versus the prior 229,100. The release carries medium market impact and will be watched for signs of resilience in residential construction amid higher borrowing costs. No other Canadian data points are due today.
Market participants will also monitor any updates on U.S.-Canada trade negotiations that have already pressured home sales. Fixed-income desks will track movements in government yields ahead of the next Bank of Canada decision.
Other Economic Notes
Escalating U.S.-Canada trade tensions have contributed to weaker home sales and flat residential prices, with higher bond yields pushing fixed mortgage rates higher. The Railway Association of Canada welcomed federal plans for immediate expensing on rail assets, signaling potential support for capital investment. National Bank of Canada launched an institutional NVCC preferred shares offering to bolster capital.
Business Council of Canada CEO Goldy Hyder noted signs of returning capital inflows following recent policy shifts. Broader uncertainty around U.S. tariffs continues to affect export-oriented sectors and provincial fiscal outlooks.