Canada Macro Daily(Beta Mode)
BoC Flags Tariffs Amid Sticky Core Inflation
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,491.30 | -0.26% |
| USD/CAD | 1.40 | +0.52% |
| EUR/CAD | 1.61 | -0.07% |
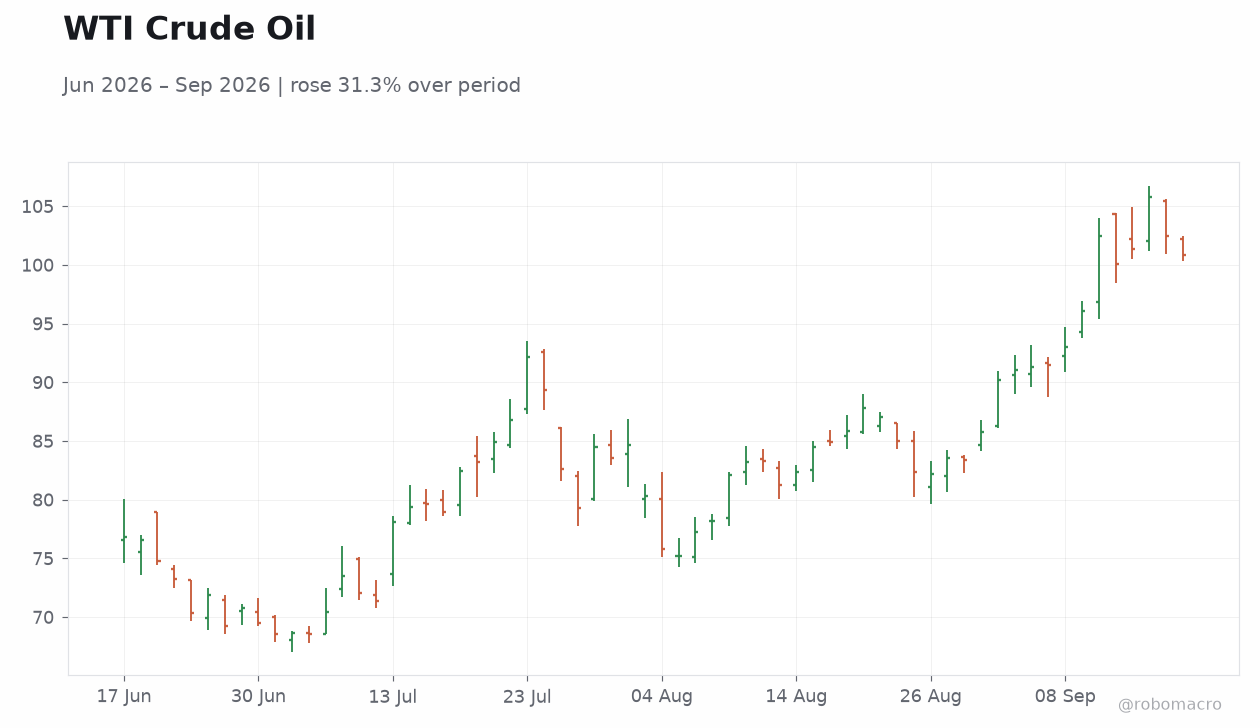
| WTI Crude | 100.73 | -1.66% |
| Natural Gas | 2.89 | -0.10% |
| Gold | 4,367.40 | -0.46% |
| Brent Crude | 99.34 | -6.13% |
| Bitcoin | 76,133.51 | -0.02% |
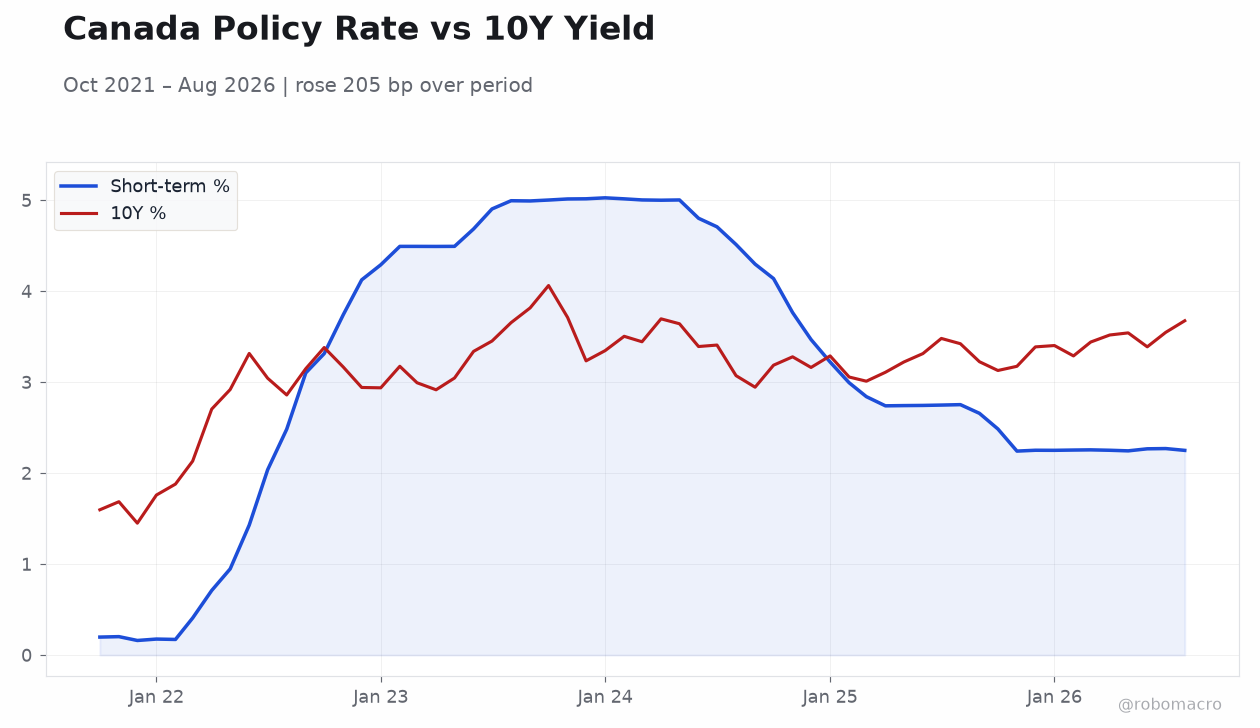
| Canada 2Y Govt Yield | 3.35% | -2 bp |
| Canada 10Y Govt Yield | 3.95% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 3 | 3 | 3 |
| Core Inflation Rate Year-over-Year | 2.30 | - | 2.40 |
| Inflation Rate Month-over-Month | 0.50 | 0 | -0.10 |
| Housing Starts Level | 229,400 | 240,000 | 229,000 |
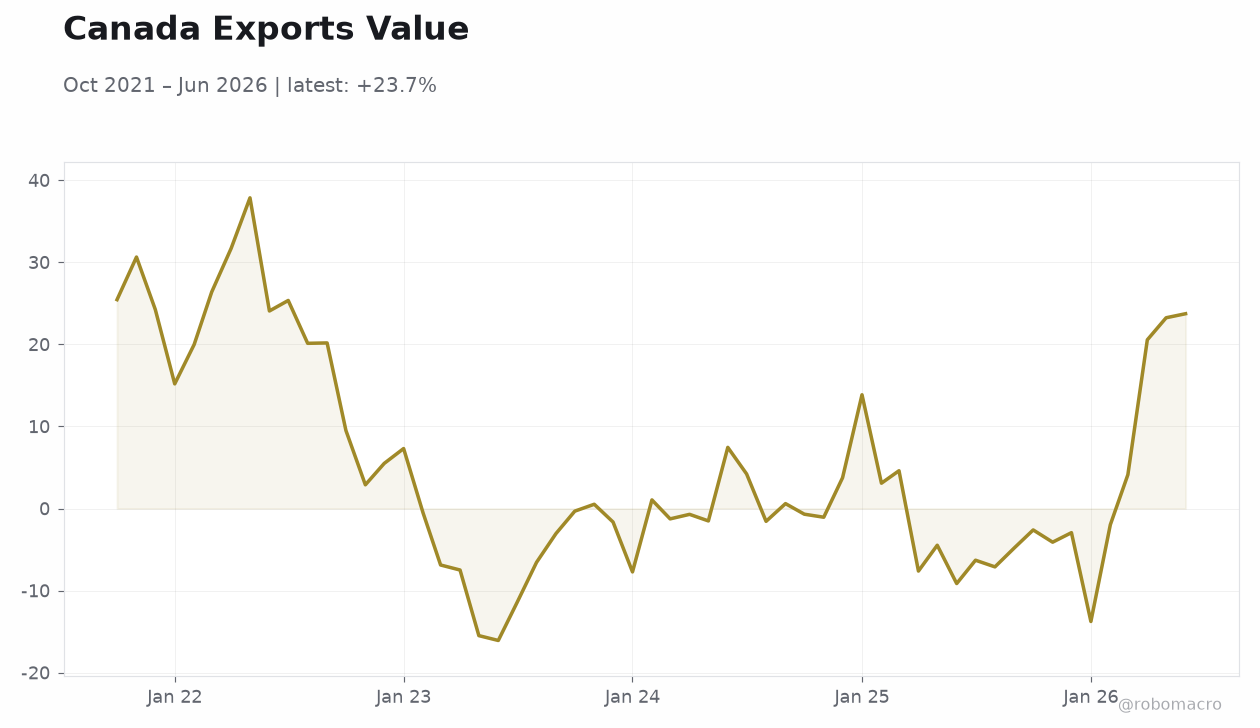 Canada Exports Value | Type: macro_line | Value: 23.73 (2026-06-01) | Range: -16.08–37.85 | Trend(5pt): 25.45,5.492,1.05,-7.62,23.73
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- August CPI holds at 3.0% YoY while core rises to 2.4%
- Housing starts miss at 229,000 versus 240,000 consensus
- TSX falls 0.26% as USD/CAD climbs 0.52% to 1.40
Yesterday's Recap
Statistics Canada reported August inflation data showing headline CPI unchanged at 3.0% year-over-year, matching consensus, while core CPI increased to 2.4% from 2.3%. August CPI held at 3.00% YoY against expectations of flat. Housing starts printed at 229,000 in August, below the 240,000 consensus and marginally softer than the prior 229,400.
The S&P/TSX Composite closed down 0.26% at 35,491.30. USD/CAD strengthened 0.52% to 1.40 while EUR/CAD eased 0.07% to 1.61. Canada 2-year yields fell 2 bp to 3.35% and 10-year yields rose 1 bp to 3.95%.
WTI crude declined 1.66% to 100.73 and Brent crude dropped 6.13% to 99.34. Natural gas eased 0.10% to 2.89 and gold declined 0.46% to 4,367.40.
The Day Ahead
No Canadian economic releases are scheduled for September 17. Markets will monitor any follow-through from recent BoC minutes and U.S. tariff developments.
Energy prices remain in focus given their influence on near-term inflation. CAD crosses may react to broader risk sentiment and any Fed-related commentary. Fixed-income participants will watch for shifts in the 2-year and 10-year yield curve.
Equity flows into the TSX could stay light absent fresh domestic catalysts.
Other Economic Notes
BoC minutes highlighted expectations that inflation will stay elevated in the near term, with officials citing persistent price pressures. The Bank also flagged risks from a fresh U.S. tariff dispute that could dampen business and consumer confidence.
European Commission President Ursula von der Leyen proposed Canada as the EU’s first associate member amid ongoing North American trade tensions. National Bank of Canada announced an institutional NVCC preferred shares offering to bolster capital. Developments around the Ksi Lisims LNG project continue to draw attention in the energy sector.