Canada Macro Daily(Beta Mode)
BoC Hike Bets Persist as Loonie Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,751.40 | -0.72% |
| USD/CAD | 1.41 | +0.35% |
| EUR/CAD | 1.60 | -0.32% |
| WTI Crude | 93.39 | +1.33% |
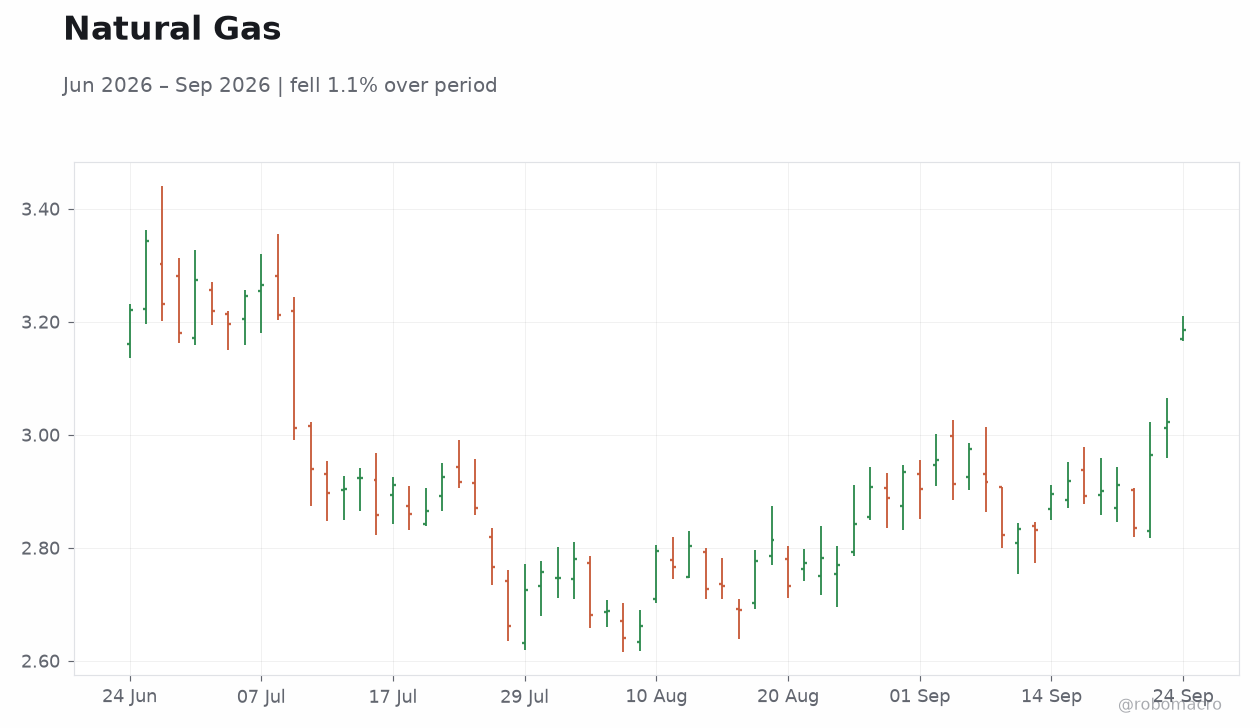
| Natural Gas | 3.19 | +5.39% |
| Gold | 4,298.70 | -0.46% |
| Brent Crude | 104.88 | +1.75% |
| Bitcoin | 83,431.73 | -1.13% |
| Canada 2Y Govt Yield | 3.29% | -3 bp |
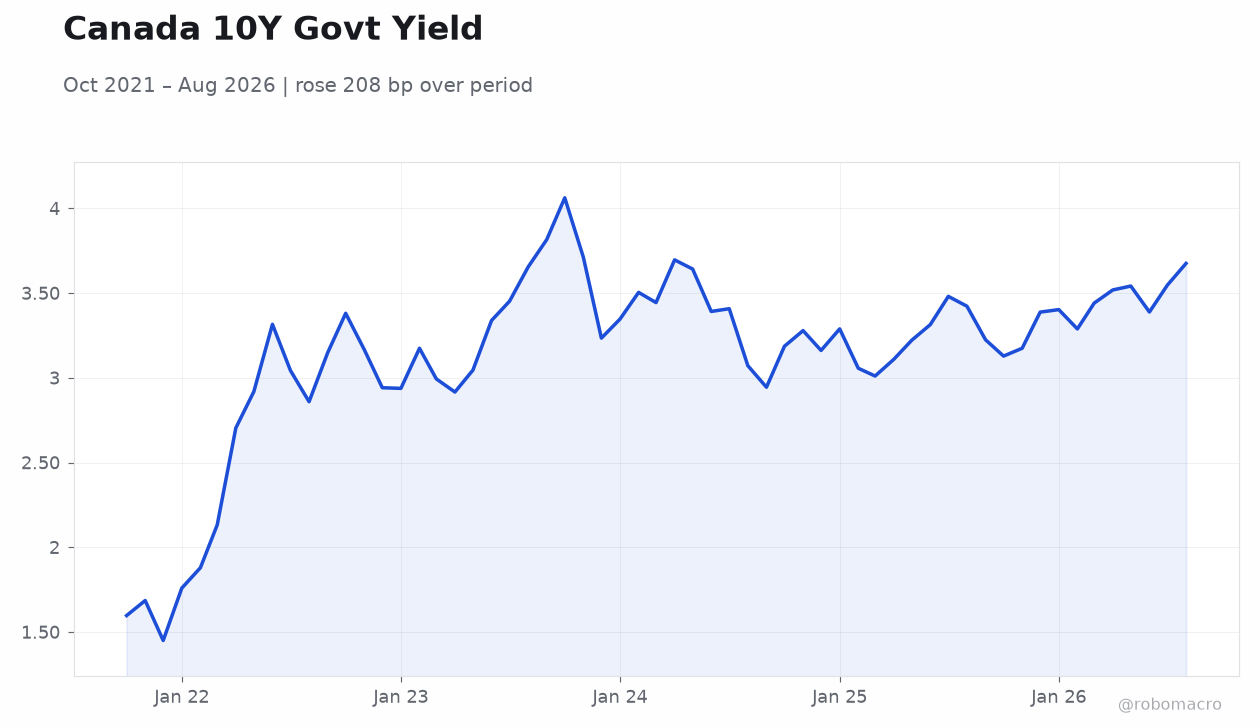
| Canada 10Y Govt Yield | 3.84% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
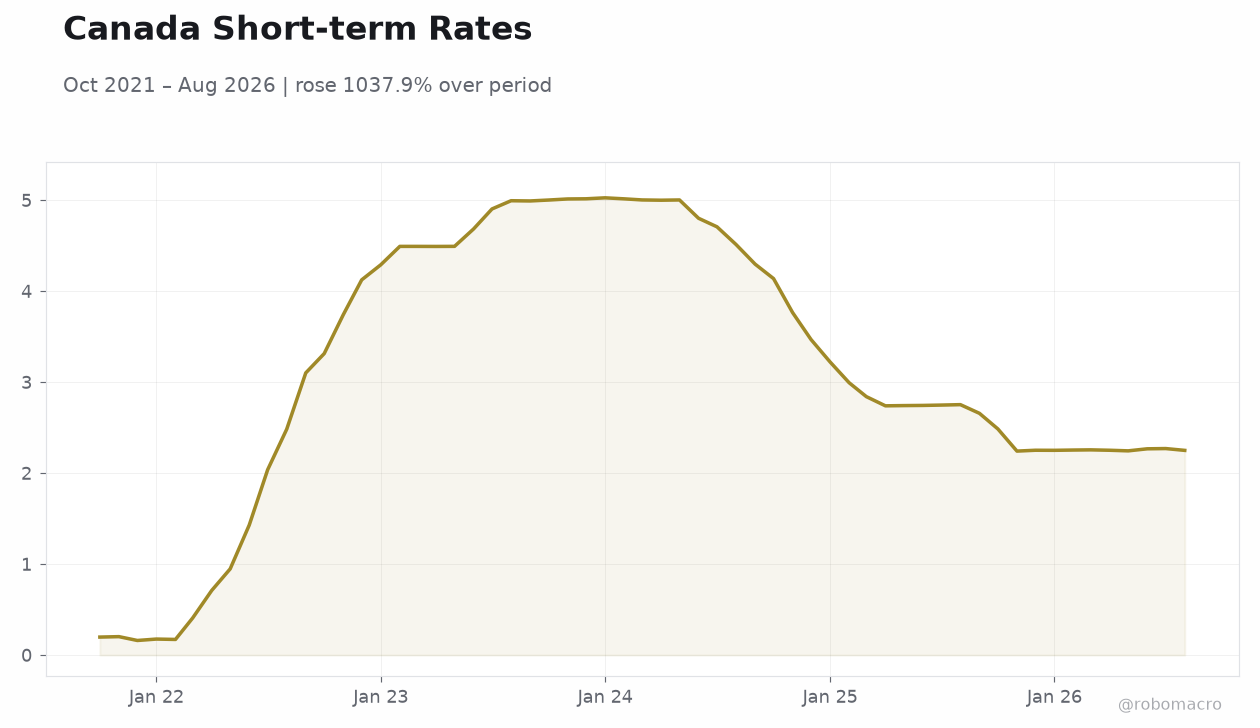 Canada Short-term Rates | Type: macro_line | %: 2.25 (2026-08-01) | Range: 0.1604–5.026 | Trend(6pt): 0.1977,4.125,5.015,2.74,2.267,2.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- S&P/TSX fell 0.72% to 35,751.40 while USD/CAD rose 0.35% to 1.41 amid energy gains.
- Canada 2-year yield eased 3 bp to 3.29% and 10-year yield eased 3 bp to 3.84%.
- Markets price near-term BoC rate hikes even as TD economist Burleton calls the case uncompelling.
Yesterday's Recap
Equity and commodity markets closed mixed on September 23 with no Statistics Canada releases or Bank of Canada communications. The S&P/TSX Composite declined 0.72% to 35,751.40 while WTI Crude advanced 1.33% to 93.39 and Brent Crude gained 1.75% to 104.88. Natural Gas surged 5.39% to 3.19.
Canadian government yields declined modestly, with the 2-year yield falling 3 bp to 3.29% and the 10-year yield falling 3 bp to 3.84%. USD/CAD climbed 0.35% to 1.41, pushing the loonie to 71 U.S. cents, while EUR/CAD eased 0.32% to 1.60.
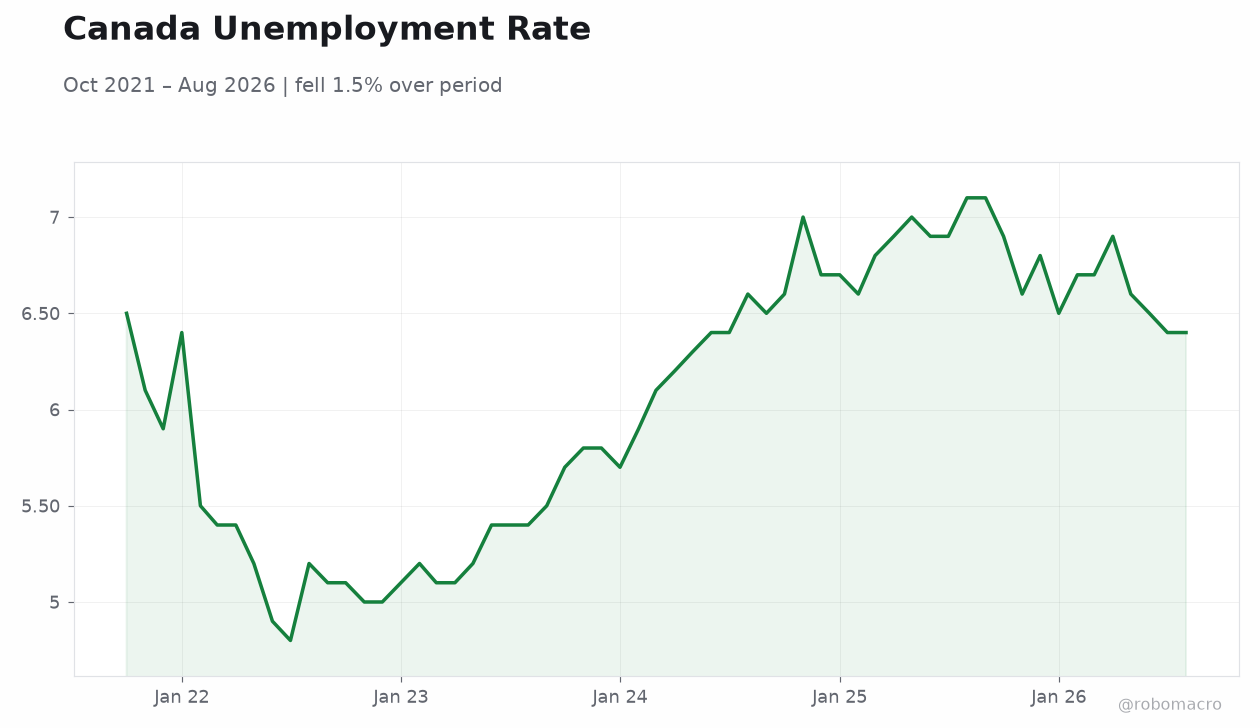
Royal Bank of Canada announced an NVCC subordinated debenture issue and Shell partners moved closer to doubling the LNG Canada project. An opinion piece urged caution when interpreting the August labour-force survey that showed a 42,000-job decline.
The Day Ahead
The calendar lists no economic releases or Bank of Canada events for September 24. Market participants will monitor global oil price movements driven by Middle East supply risks and any follow-through from U.S.-Iran diplomatic signals. Canadian asset managers continue to signal plans to reduce U.S.
equity allocations over the coming year. Attention will also focus on whether the loonie’s recent weakness prompts further commentary from officials. Energy exporters stand to benefit from sustained WTI and Brent strength above recent levels.
Other Economic Notes
Broader themes center on Canada’s external balances and domestic labour-market data interpretation. The NDP leader highlighted ongoing Bank of Canada staff strike issues nearing 100 days. More than half of surveyed Canadian asset managers plan to cut U.S.
equity holdings within twelve months, favoring domestic assets. LNG Canada expansion supports western gas export growth to Asia. These developments occur against a policy-rate backdrop of 2.25% and CPI at 3.00% year-over-year as of August.