Canada Macro Daily(Beta Mode)
Retail Sales Miss, Oil Slides
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,706.50 | -0.13% |
| USD/CAD | 1.41 | +0.27% |
| EUR/CAD | 1.61 | +0.48% |
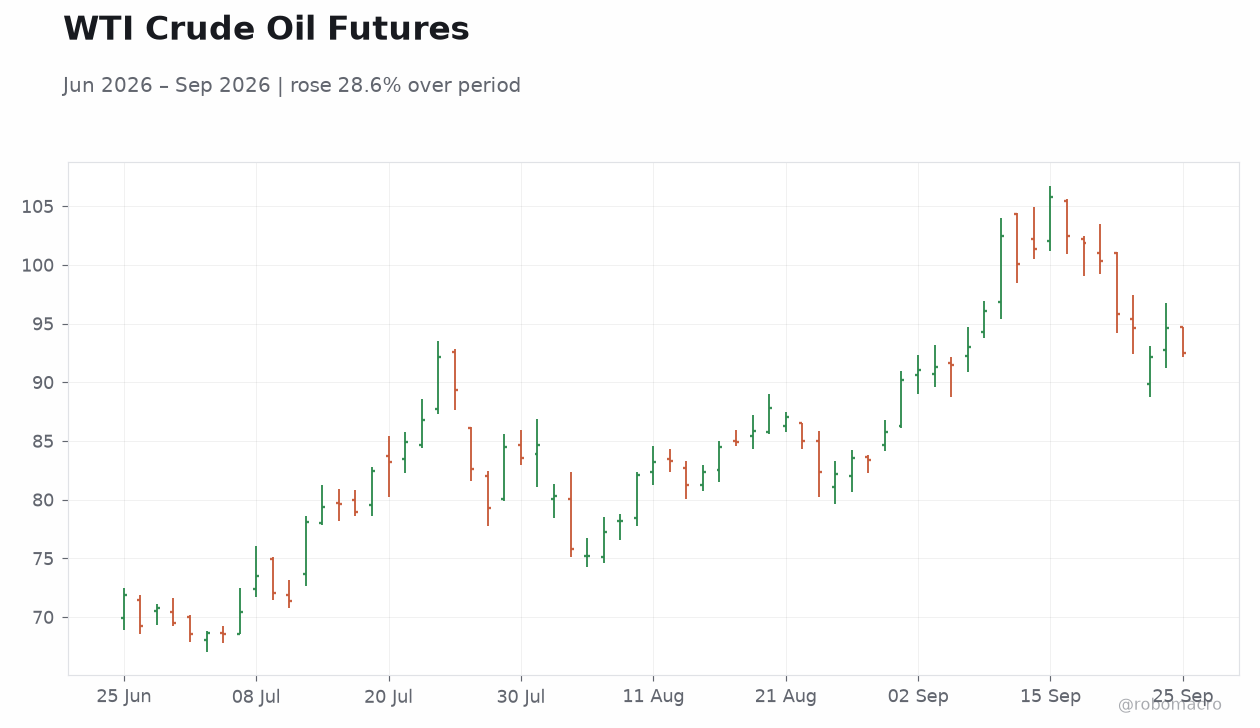
| WTI Crude | 92.45 | -2.28% |
| Natural Gas | 3.23 | -1.88% |
| Gold | 4,341.10 | +1.00% |
| Brent Crude | 98.35 | -7.74% |
| Bitcoin | 84,833.21 | +0.54% |
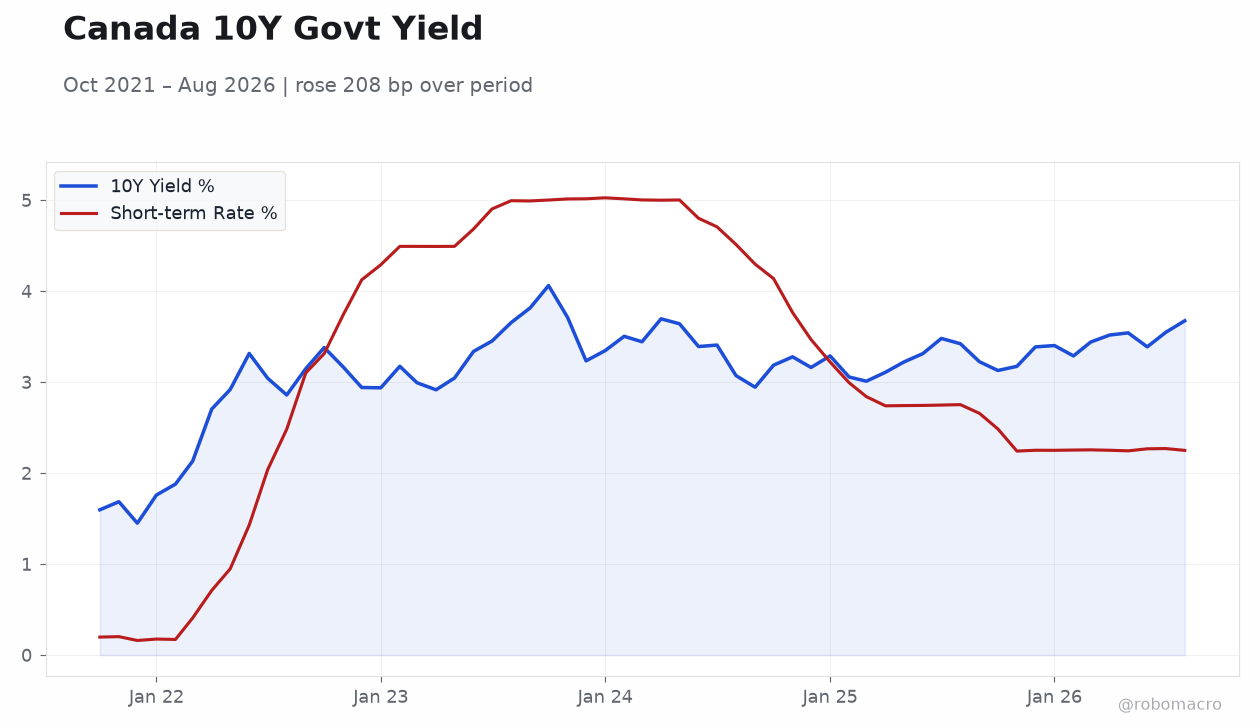
| Canada 2Y Govt Yield | 3.25% | -4 bp |
| Canada 10Y Govt Yield | 3.83% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Retail Sales Excluding Autos Month-over-Month | 0.50 | -0.50 | -0.70 |
| Retail Sales Month-over-Month Final | 0.60 | -0.80 | -0.70 |
| Retail Sales Month-over-Month Prel | - | - | 1.30 |
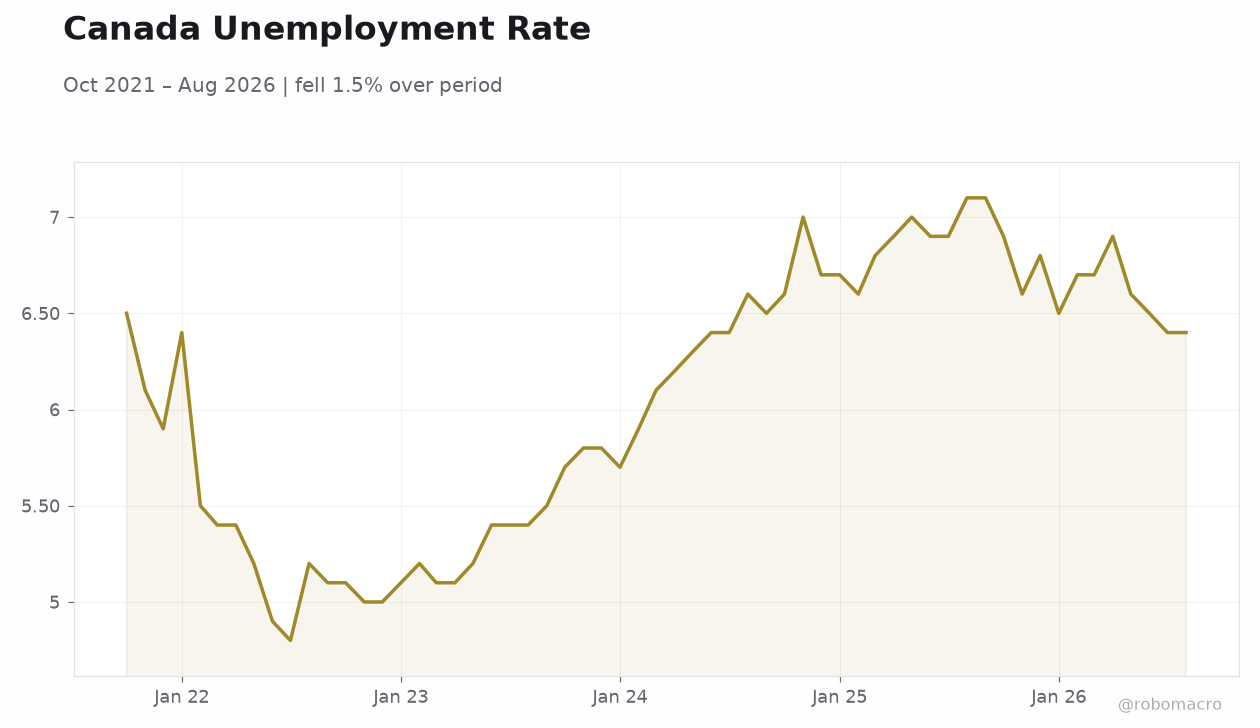 Canada Unemployment Rate | Type: macro_line | Unemployment Rate %: 6.4 (2026-08-01) | Range: 4.8–7.1 | Trend(6pt): 6.5,5,5.9,6.9,6.5,6.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Canadian retail sales missed forecasts with ex-autos falling 0.7% in August.
- S&P/TSX slipped 0.13% while the 2-year yield eased 4 bp to 3.25%.
- WTI crude dropped 2.28% to 92.45 amid softer domestic demand signals.
Yesterday's Recap
Retail sales data released at 4:30 ET showed clear consumer weakness. Retail Sales ex-Autos MoM printed -0.7% against a -0.5% consensus and 0.5% prior. The final Retail Sales MoM reading came in at -0.7% versus a -0.8% consensus and 0.6% prior, while the preliminary print reached 1.3%.
The S&P/TSX Composite closed at 35,706.50, down 0.13%. USD/CAD rose 0.27% to 1.41 and EUR/CAD gained 0.48% to 1.61. Canada 2-year yields eased 4 bp to 3.25% and the 10-year eased 1 bp to 3.83%.
WTI crude fell 2.28% to 92.45 while gold rose 1.00% to 4,341.10, reflecting the softer data tone. Natural gas declined 1.88% to 3.23 and Brent crude dropped 7.74% to 98.35. Bitcoin finished at 84,833.21, up 0.54%.
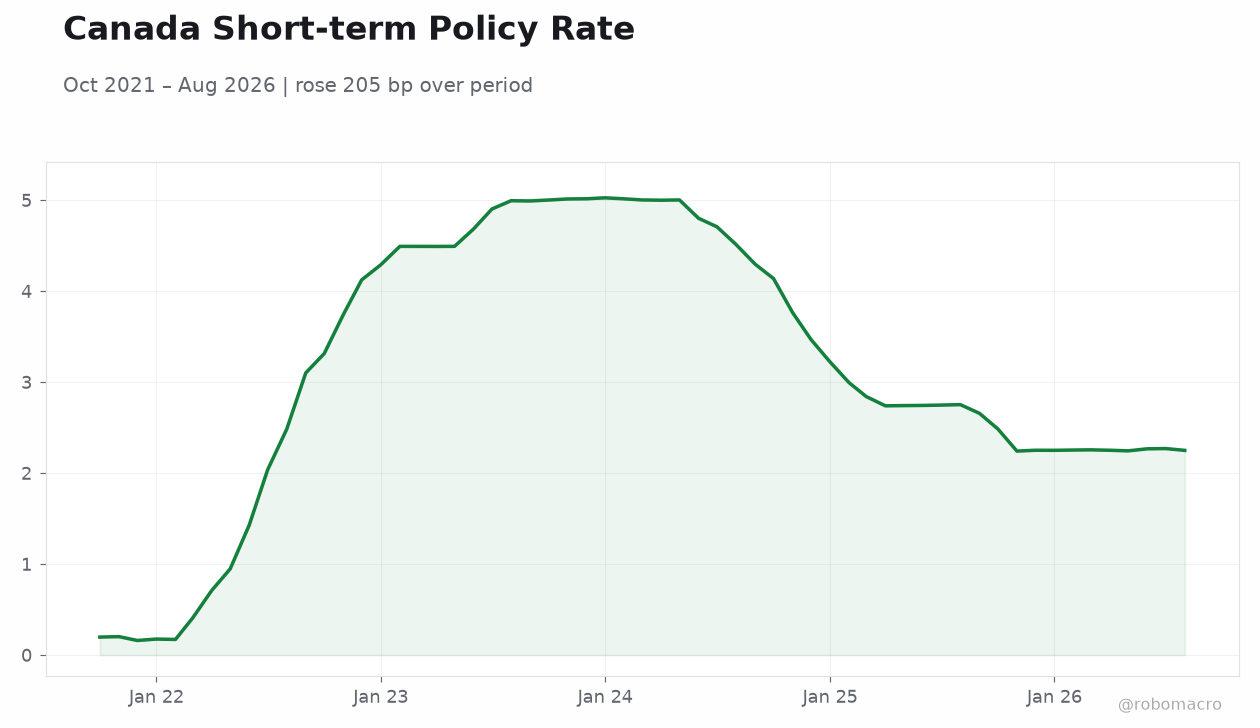
The moves suggest markets are pricing a steady Bank of Canada policy path amid softer domestic data and weaker energy prices.
The Day Ahead
No Canadian economic releases are scheduled for September 25. Markets will monitor external tariff developments and any follow-up remarks from Bank of Canada officials. Energy price swings and USD/CAD moves will likely dominate trading.
Attention also turns to U.S. data that could influence cross-border flows. Traders expect limited domestic volatility given the empty calendar.
Corporate announcements such as National Bank of Canada’s normal-course issuer bid may provide incremental equity-specific color without shifting broader macro sentiment.
Other Economic Notes
Headline inflation eased to 2.3% as gasoline prices declined. Revised population figures show slower growth than previously estimated. National Bank of Canada announced plans for a normal-course issuer bid while Royal Bank of Canada maintained its dividend at 2.49%.
These corporate moves occur against a backdrop of steady policy rates and subdued consumer spending. Broader themes center on tariff risks and their potential drag on growth. Canada’s 2025 GDP per capita remains below every U.S.
state, underscoring structural productivity challenges even as banking-sector fundamentals stay resilient.