Canada Macro Daily(Beta Mode)
Canada GDP Print Looms Amid Tariff Risks
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,489.90 | -0.87% |
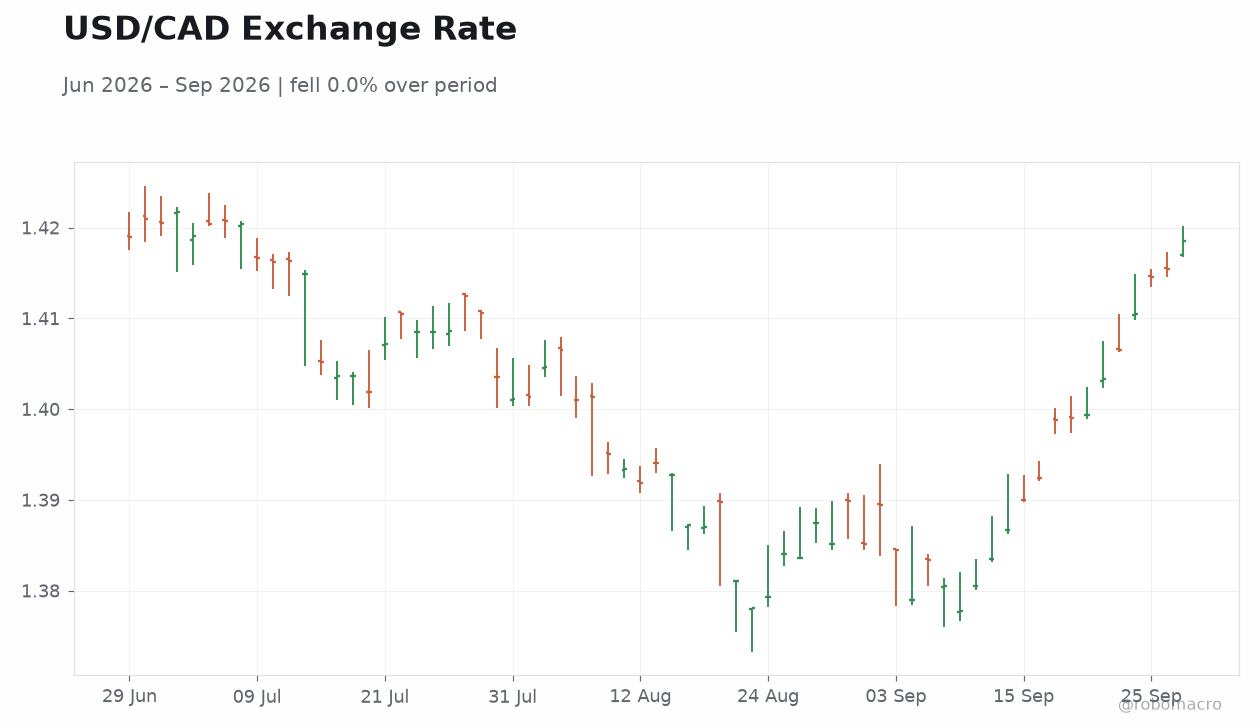
| USD/CAD | 1.42 | +0.22% |
| EUR/CAD | 1.61 | +0.09% |
| WTI Crude | 91.63 | -1.05% |
| Natural Gas | 3.10 | +3.33% |
| Gold | 4,190.20 | +0.52% |
| Brent Crude | 96.77 | -8.08% |
| Bitcoin | 84,218.52 | +0.86% |
| Canada 2Y Govt Yield | 3.39% | -1 bp |
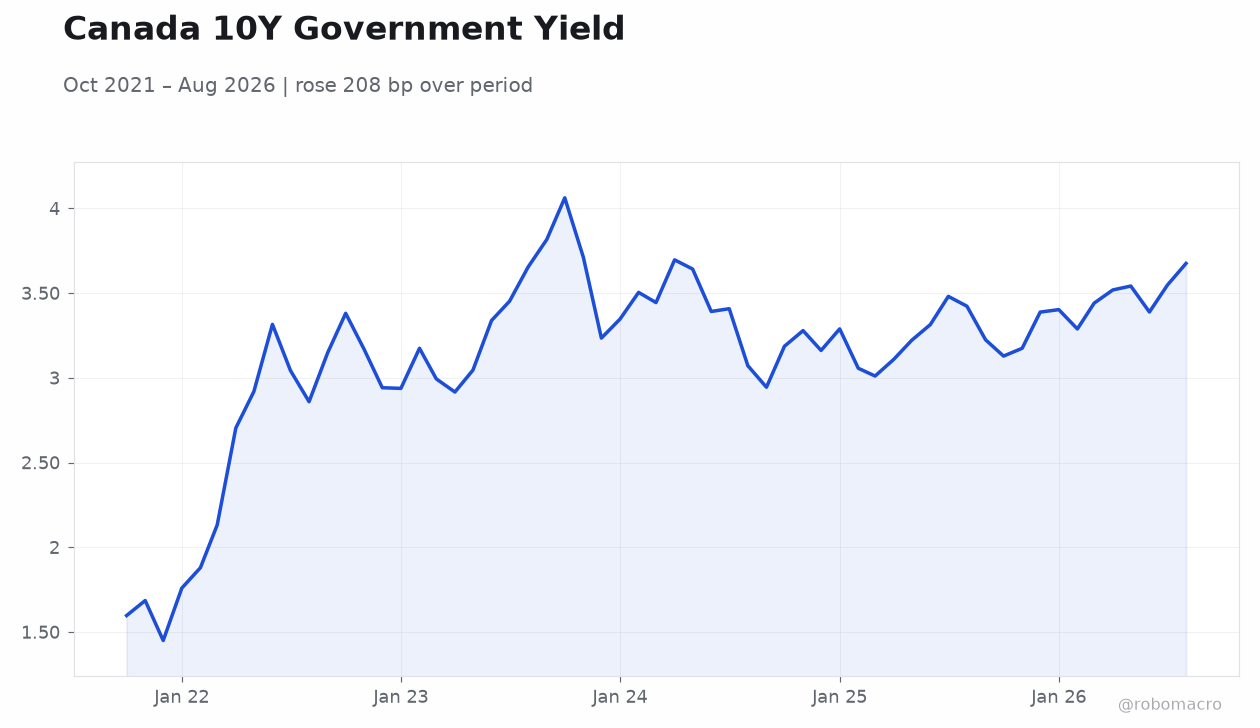
| Canada 10Y Govt Yield | 3.97% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
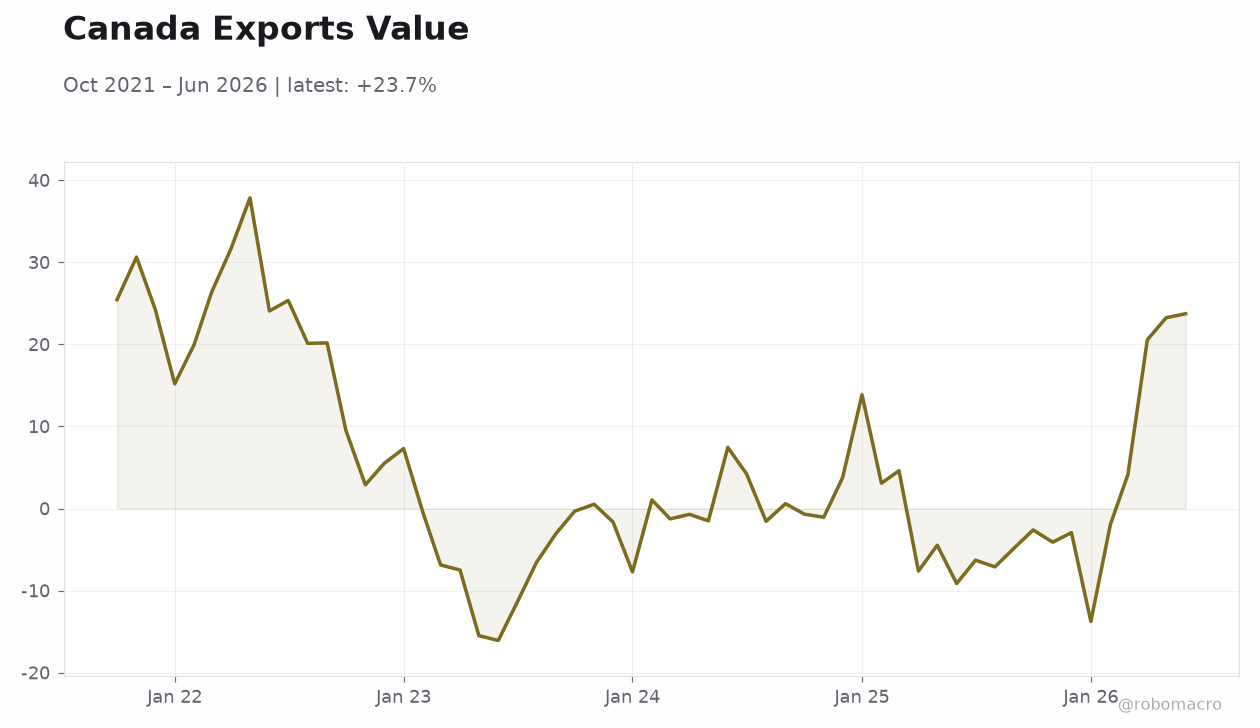
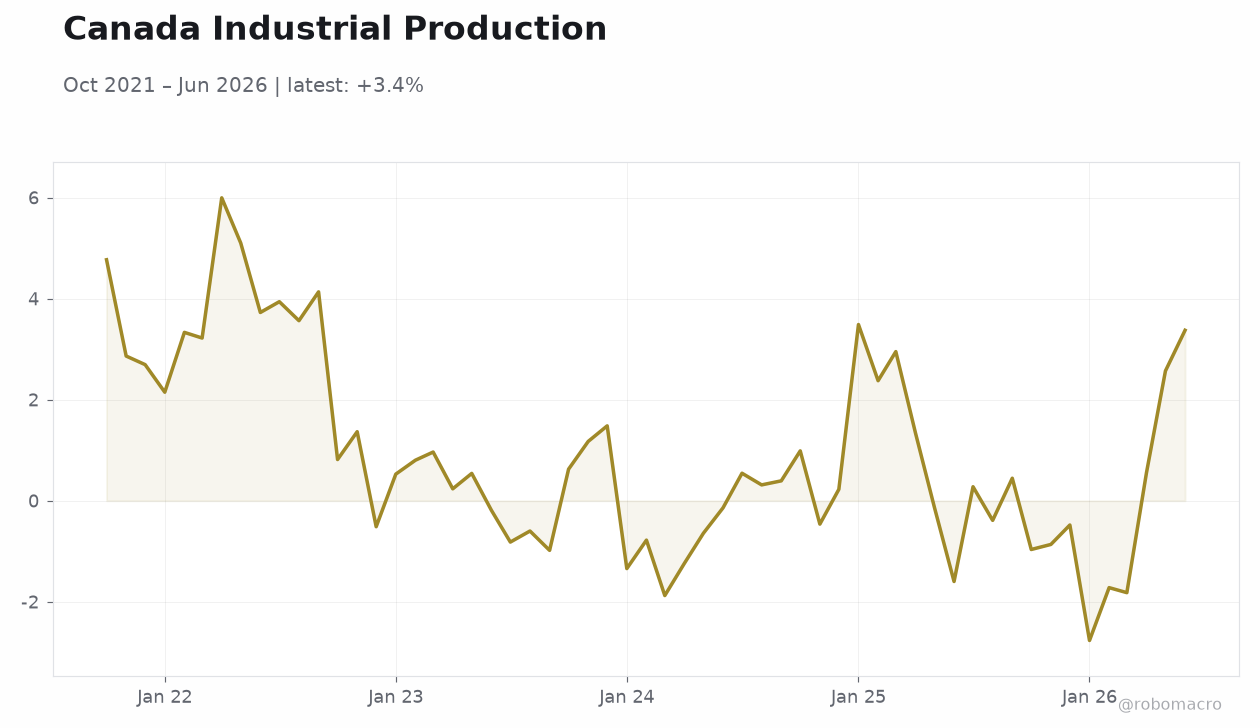 Canada Industrial Production | Type: macro_line | Industrial Production (YoY%): 3.374 (2026-06-01) | Range: -2.766–5.995 | Trend(5pt): 4.769,-0.514,-0.7799,1.344,3.374
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| GDP Month-over-Month | 0.30 | 0 | 04:30 |
| GDP Month-over-Month Prel | - | - | 04:30 |
| Thursday (2026-10-01) | |||
| S&P Global Manufacturing PMI Index | 53 | - | 05:30 |
- GDP Month-over-Month expected at 0.0% after 0.3% prior, with RBC flagging potential stall in July data.
- S&P/TSX fell 0.87% to 35,489.90 while USD/CAD rose 0.22% to 1.42 on tariff concerns.
- Canada 2-year yield eased 1 bp to 3.39% and 10-year yield rose 1 bp to 3.97% as BoC holds at 2.25%.
Yesterday's Recap
No Canadian economic releases occurred on September 28. The S&P/TSX Composite declined 0.87% to close at 35,489.90. USD/CAD advanced 0.22% to 1.42 while EUR/CAD gained 0.09% to 1.61.
WTI Crude fell 1.05% to 91.63 and Brent Crude dropped 8.08% to 96.77, though Natural Gas rose 3.33% to 3.10. Gold increased 0.52% to 4,190.20 and Bitcoin rose 0.86% to 84,218.52. Canada 2-year government yields declined 1 bp to 3.39% and 10-year yields rose 1 bp to 3.97%.
Reports highlighted US-Canada import restrictions and looming tariffs that could weigh on future growth, alongside RBC forecasts of GDP stalling in July.
The Day Ahead
Statistics Canada will release GDP Month-over-Month and GDP Month-over-Month Prelim at 04:30 ET, with consensus at 0.0% versus the prior 0.3% print. Markets will scrutinize the figures for signs of softening momentum ahead of US tariff implementation. The S&P Global Manufacturing PMI is scheduled for October 1 at 05:30 ET.
No Bank of Canada speeches or policy announcements are listed for the session. Traders will monitor CAD crosses and front-end yields for any repricing tied to the data outcome, with attention on how the prints interact with ongoing trade tensions.
Other Economic Notes
US tariffs threaten to erode recent Canadian GDP resilience, with analysts noting potential fading strength in coming quarters. Energy sector commentary points to Middle East tensions and US trade pressure as catalysts for renewed Canadian production growth. National Bank of Canada’s asset-management unit launched new funds while dividend coverage remains in focus for investors.
Broader domestic confidence stays neutral amid oil-driven inflation signals. These developments reinforce the linkage between external trade risks and Canadian output prospects, with coffee industry contributions adding $34.7 billion in economic impact as a separate domestic positive.