Canada Macro Daily(Beta Mode)
Canada GDP Stalls, Yields Ease on Flat Print
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,460.30 | -0.08% |
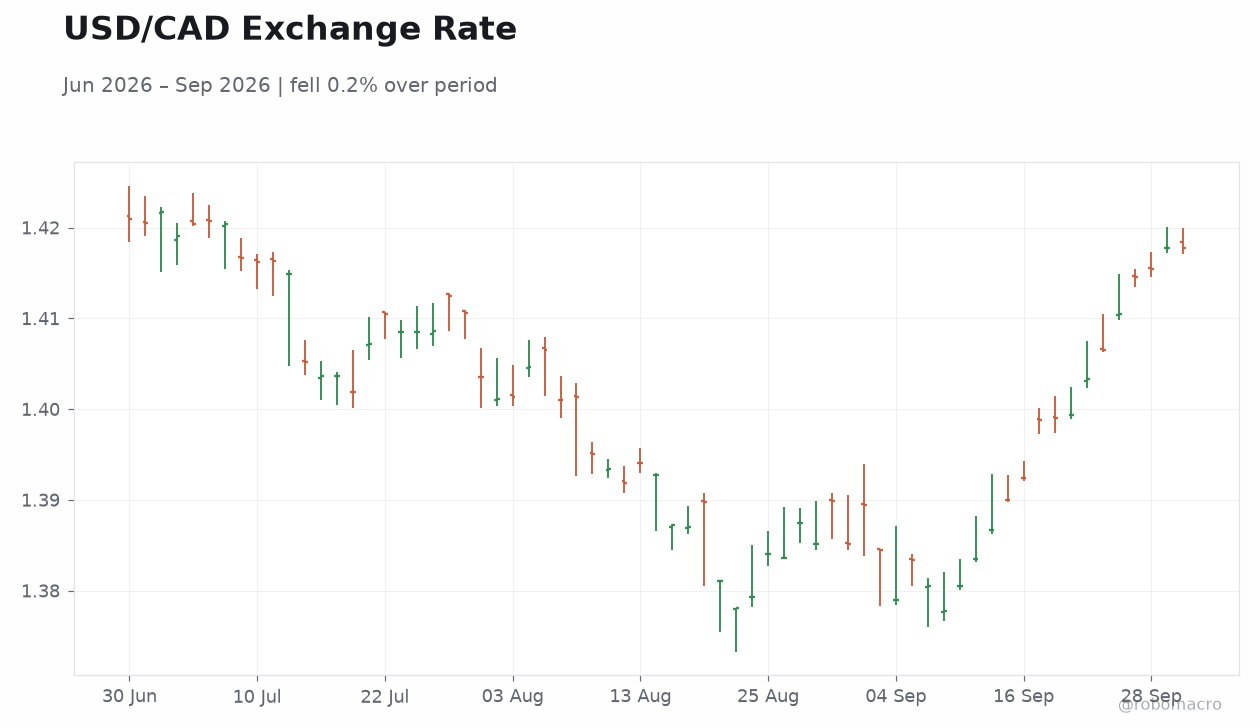
| USD/CAD | 1.42 | -0.01% |
| EUR/CAD | 1.61 | +0.11% |
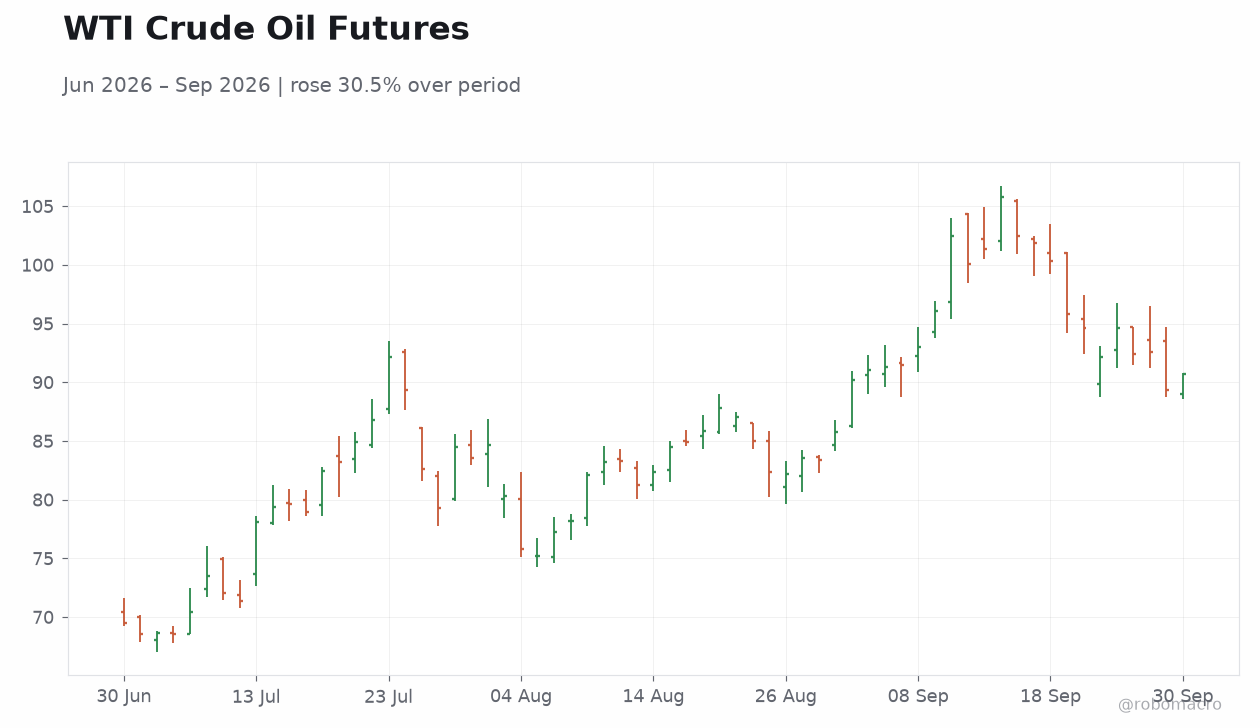
| WTI Crude | 90.78 | +1.57% |
| Natural Gas | 3.03 | +0.66% |
| Gold | 4,213.80 | +0.82% |
| Brent Crude | 97.77 | -4.70% |
| Bitcoin | 83,862.37 | +0.29% |
| Canada 2Y Govt Yield | 3.35% | -4 bp |
| Canada 10Y Govt Yield | 3.94% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| GDP Month-over-Month | 0.30 | 0 | 0 |
| GDP Month-over-Month Prel | - | - | 0.20 |
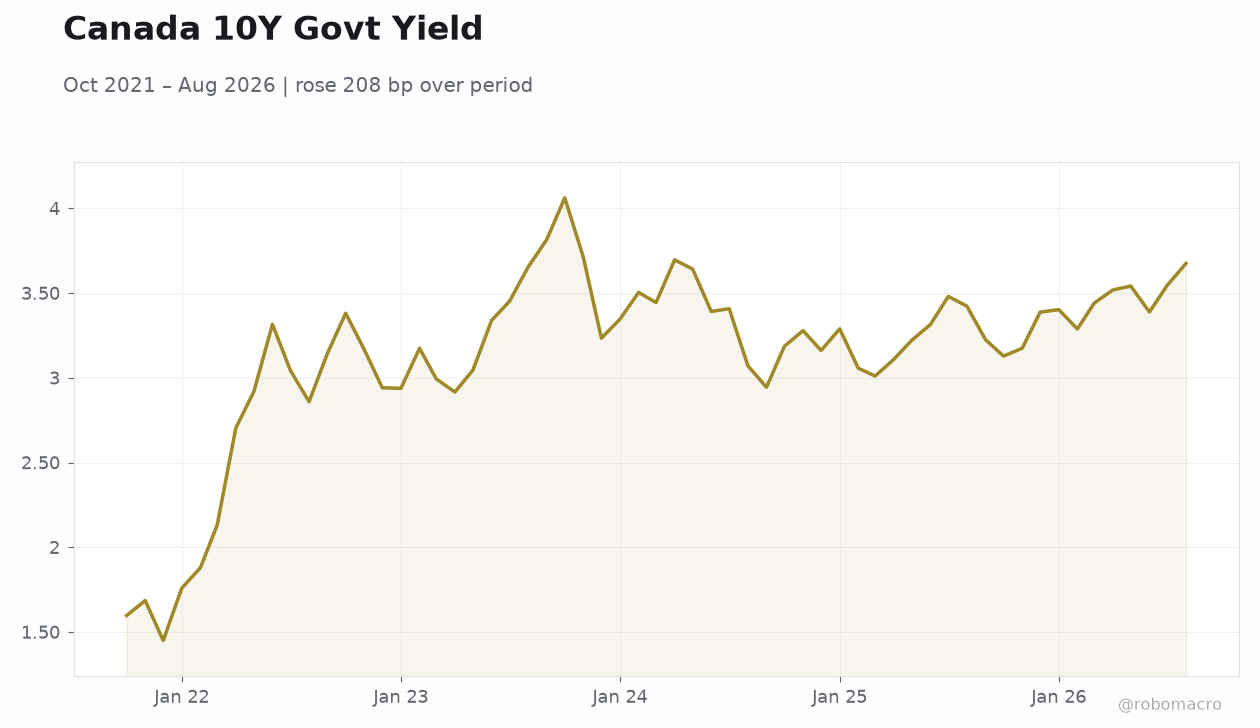 Canada 10Y Govt Yield | Type: macro_line | Yield %: 3.675 (2026-08-01) | Range: 1.45–4.062 | Trend(6pt): 1.597,2.942,3.504,3.109,3.388,3.675
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-10-01) | |||
| S&P Global Manufacturing PMI Index | 53 | - | 05:30 |
- Canada GDP rose 0.0% month-over-month in July, matching consensus but slowing from 0.3% prior.
- S&P/TSX fell 0.08% to 35,460.30 while Canada 2-year yields eased 4 bp to 3.35%.
- WTI crude climbed 1.57% to 90.78 as USD/CAD held near 1.42.
Yesterday's Recap
Statistics Canada reported July GDP flat at 0.0% month-over-month, with the preliminary estimate at +0.2%. The print followed a 0.3% gain in June and confirmed the stall noted in earlier releases. Markets absorbed the data without sharp moves.
The S&P/TSX closed down 0.08% at 35,460.30. Canada 2-year yields fell 4 bp to 3.35% and 10-year yields declined 3 bp to 3.94%. USD/CAD eased 0.01% to 1.42 while WTI crude advanced 1.57% to 90.78.
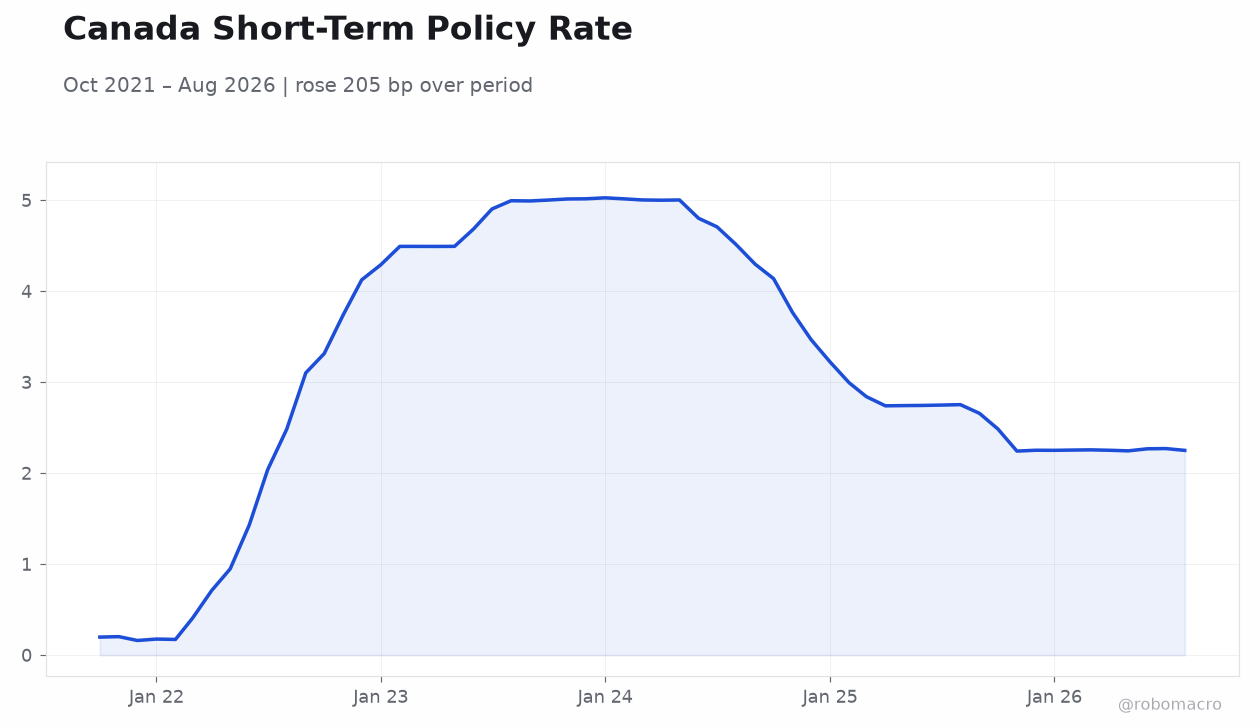
Natural gas rose 0.66% to 3.03 and gold gained 0.82% to 4,213.80. The Canadian dollar showed limited reaction, reflecting steady BoC policy expectations at the 2.25% rate. Brent Crude fell 4.70% to 97.77 amid mixed energy moves, while Bitcoin rose 0.29% to 83,862.37.
EUR/CAD advanced 0.11% to 1.61 on firmer oil prices and ECB caution.
The Day Ahead
The S&P Global Manufacturing PMI for September releases at 05:30 ET on October 1. The prior reading stood at 53.0, and no consensus is available. Markets will assess whether the index signals sustained expansion in factory activity.
Any downside surprise could reinforce views that growth momentum remains modest. The print may influence front-end yields and CAD crosses ahead of the weekend. No other Canada-specific data are scheduled.
Attention will also stay on external factors such as Middle East supply concerns that lifted WTI and tariff-related risks flagged in recent forecasts.
Other Economic Notes
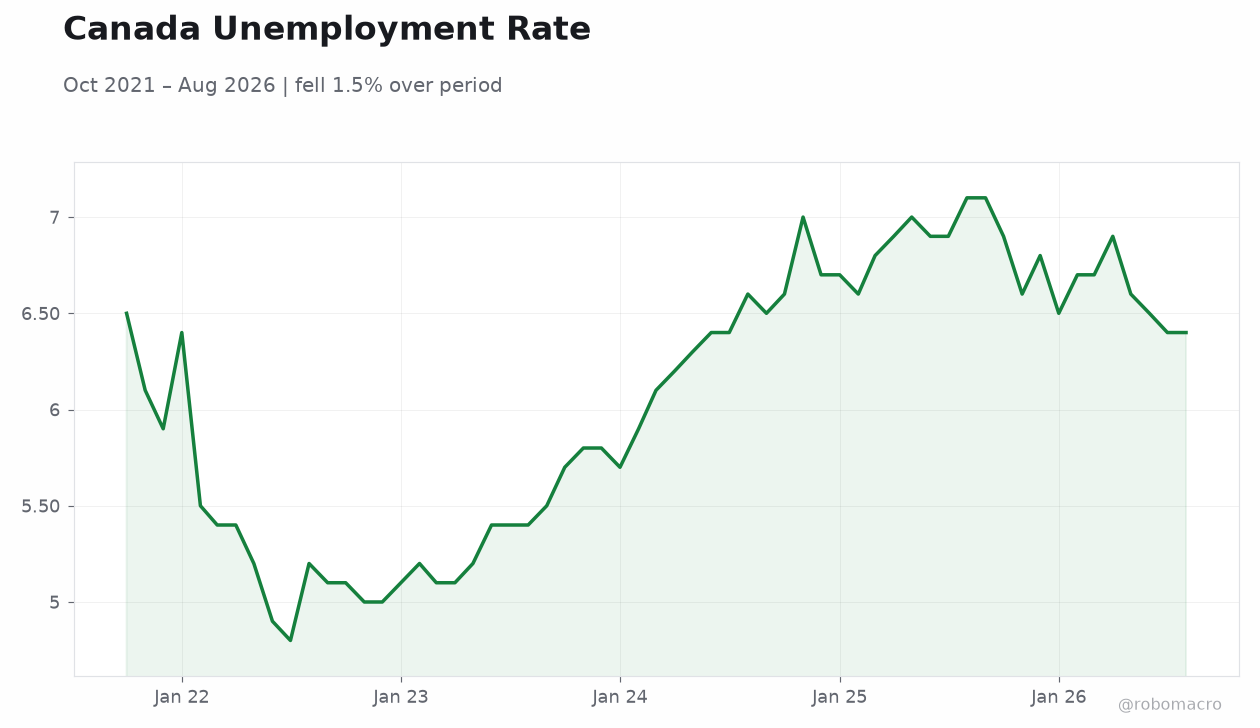
Headline CPI reached 3.00% year-over-year in August, driven by gasoline price rebounds. Economists at the Financial Post argued that economic resilience supports BoC rate hikes despite the flat GDP print. Tariffs are projected to slow 2027 growth, adding downside risk to the medium-term outlook.
LNG Canada expansion continues while Northern Shield pipeline developments remain in focus. These factors keep attention on supply-side pressures and external trade risks. Gasoline rebounds and energy shocks add layers to inflation dynamics, while LNG projects and pipeline news provide offsetting positive signals for longer-term supply.