Canada Macro Daily(Beta Mode)
Flat GDP, Rising Yields Fuel BoC Hike Debate
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,235.90 | -0.63% |
| USD/CAD | 1.42 | +0.39% |
| EUR/CAD | 1.61 | -0.17% |
| WTI Crude | 92.19 | +1.96% |
| Natural Gas | 2.96 | -2.18% |
| Gold | 4,201.10 | +0.34% |
| Brent Crude | 100.56 | -2.87% |
| Bitcoin | 83,894.79 | +0.41% |
| Canada 2Y Govt Yield | 3.37% | +2 bp |
| Canada 10Y Govt Yield | 3.96% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| GDP Month-over-Month | 0.40 | 0 | 0 |
| GDP Month-over-Month Prel | 0 | - | 0.20 |
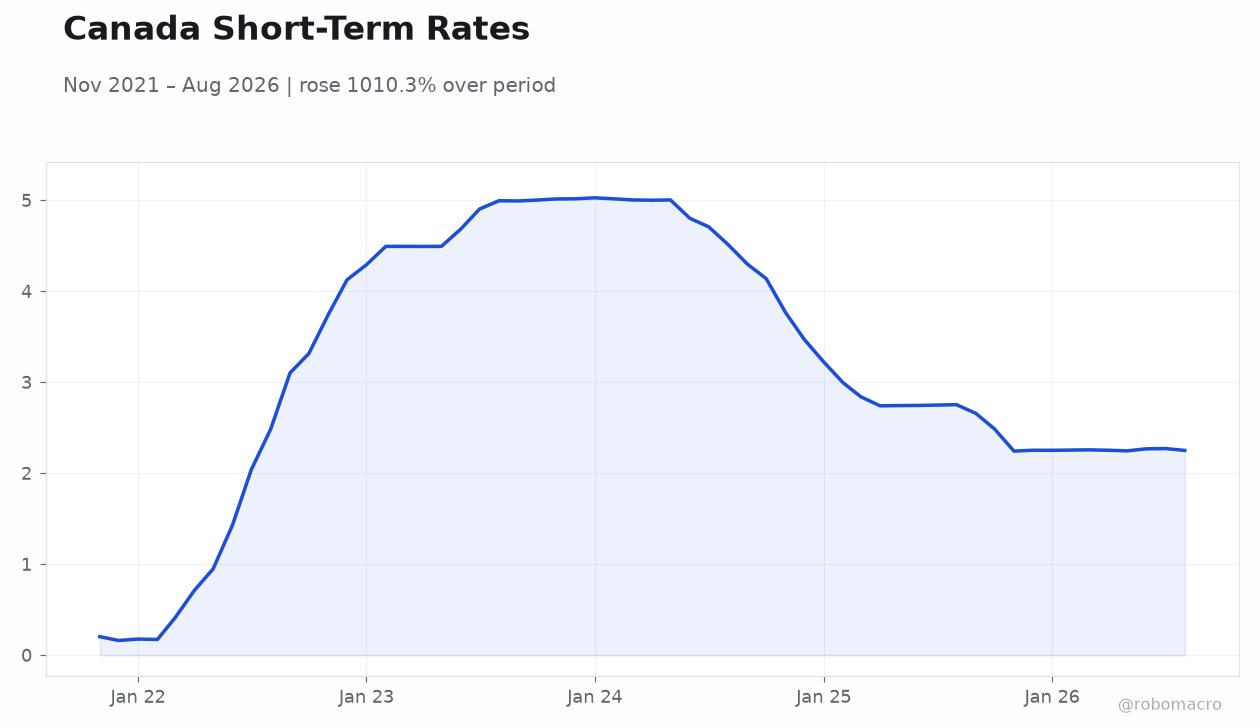
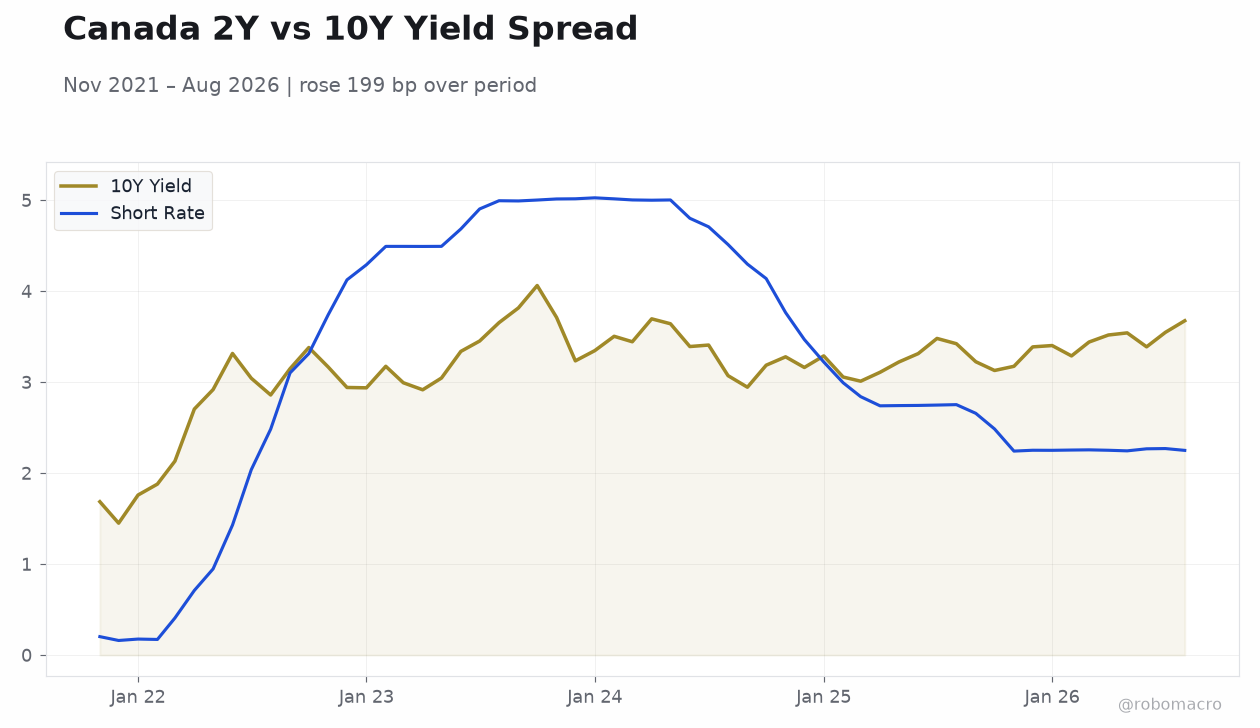 Canada 2Y vs 10Y Yield Spread | Type: macro_line | 10Y Yield: 3.675 (2026-08-01) | Range: 1.45–4.062 | Trend(6pt): 1.686,2.938,3.444,3.221,3.547,3.675 | Short Rate: 2.25 (2026-08-01) | Range: 0.1604–5.026 | Trend(6pt): 0.2027,4.29,5.003,2.742,2.27,2.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| S&P Global Manufacturing PMI Index | 53 | - | 05:30 |
- Canada GDP printed flat at 0.0% month-over-month in August, matching consensus but below the prior 0.4%.
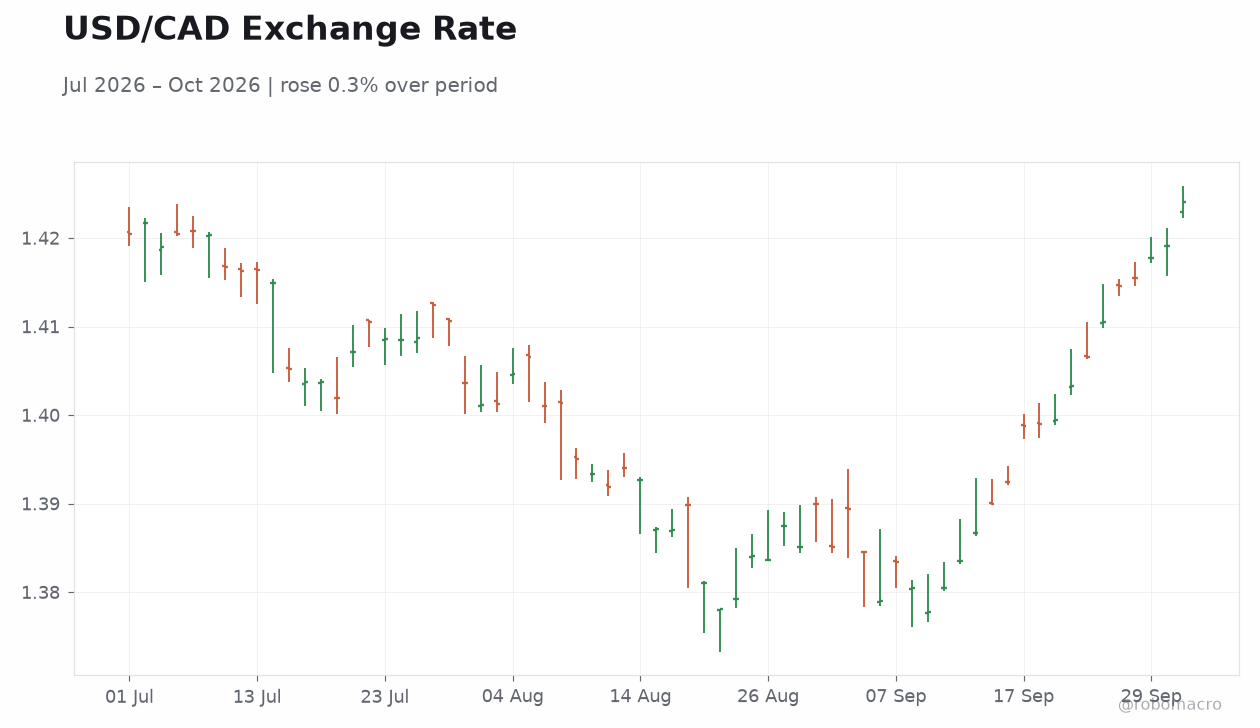
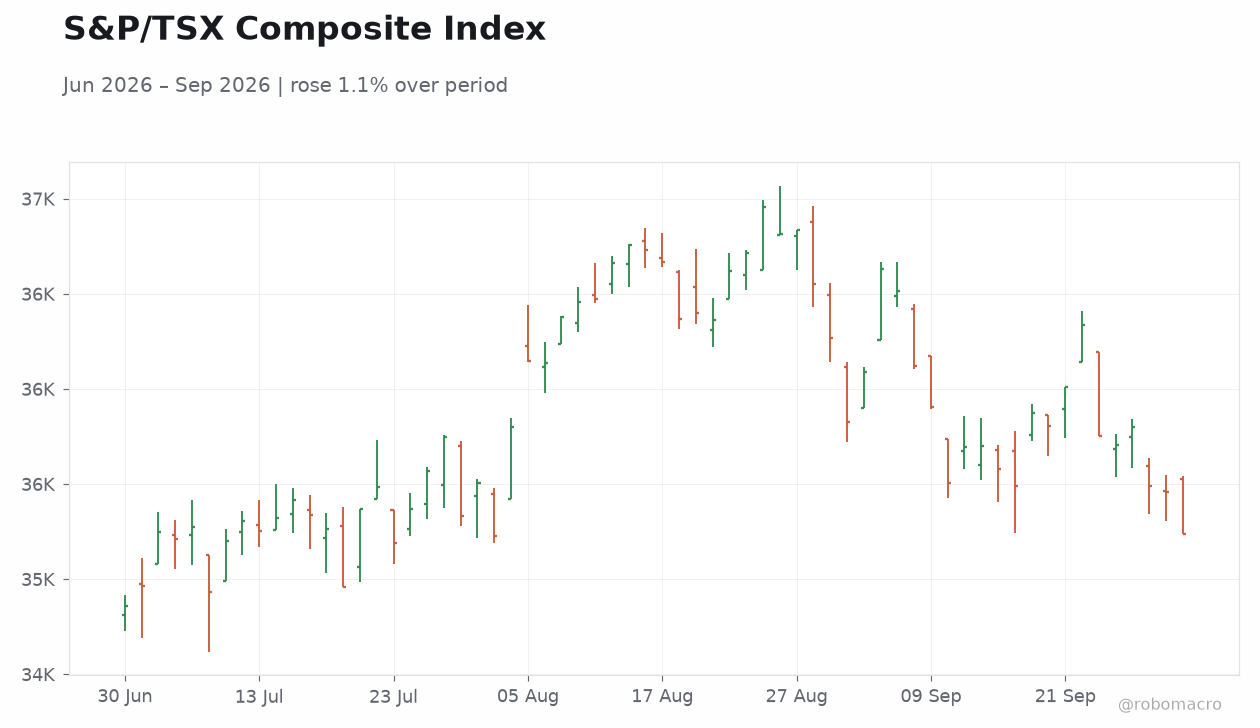
- S&P/TSX fell 0.63% to 35,235.90 while USD/CAD rose 0.39% to 1.42 amid higher yields.
- Canada 2-year yield climbed 2 bp to 3.37% and 10-year yield rose 2 bp to 3.96%.
Yesterday's Recap
Statistics Canada reported August GDP month-over-month at 0.0%, in line with consensus but down from 0.4% in July, with the preliminary reading at +0.2%. The soft print reinforced views of a cooling expansion. The S&P/TSX Composite declined 0.63% to close at 35,235.90.
USD/CAD advanced 0.39% to 1.42 while EUR/CAD eased 0.17% to 1.61. WTI crude gained 1.96% to 92.19 and natural gas fell 2.18% to 2.96. Canada 2-year government yields rose 2 bp to 3.37% and 10-year yields increased 2 bp to 3.96%, reflecting modest repricing of policy expectations.
No Bank of Canada officials spoke publicly.
The Day Ahead
The S&P Global Manufacturing PMI for September is due at 05:30 ET, with the prior reading at 53.0. The release carries medium market impact and will provide the latest gauge of factory activity. No other Canada-specific data or events are scheduled.
Traders will monitor the print for signals on growth momentum ahead of the next policy decision. CAD crosses and short-term yields are expected to react most directly to any surprise in the headline or sub-indices.
Other Economic Notes
Canada inflation eased to 2.3% year-over-year as gasoline prices declined, supporting the view of moderating price pressures. UBS revised its forecast to include two Bank of Canada rate hikes, while Capital Economics warned that a soft economy and slowing immigration should limit the pace of tightening. Trade tensions escalated after U.S.
President Trump criticized Canada’s stance, adding uncertainty to bilateral flows. The combination of cooling inflation and subdued growth keeps markets focused on the balance between policy normalization and downside risks to activity.
Global Macro News
Oil prices rebounded with WTI at 92.19 as Middle East supply risks persisted despite recovering Persian Gulf exports. Brent crude fell 2.87% to 100.56, highlighting divergent crude benchmarks. ↓ p.2