Canada Macro Daily(Beta Mode)
TSX Climbs as Yields Fall Ahead of Jobs Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
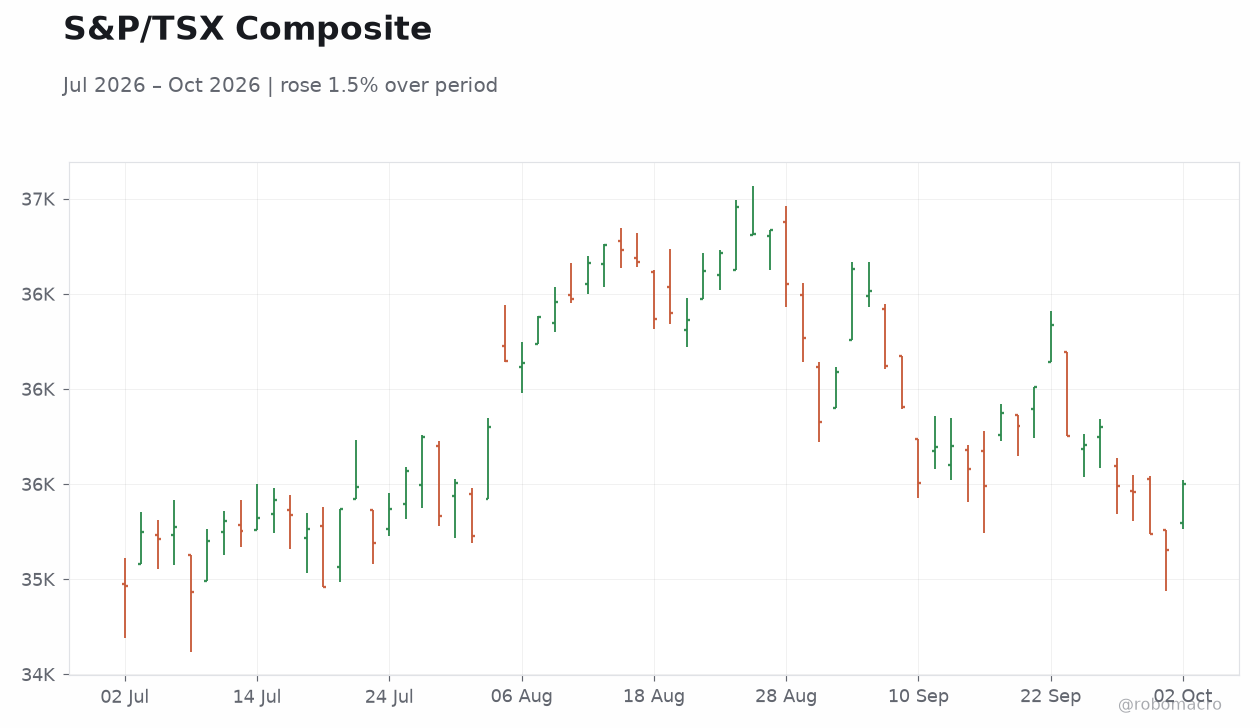
| S&P/TSX | 35,502.70 | +0.99% |
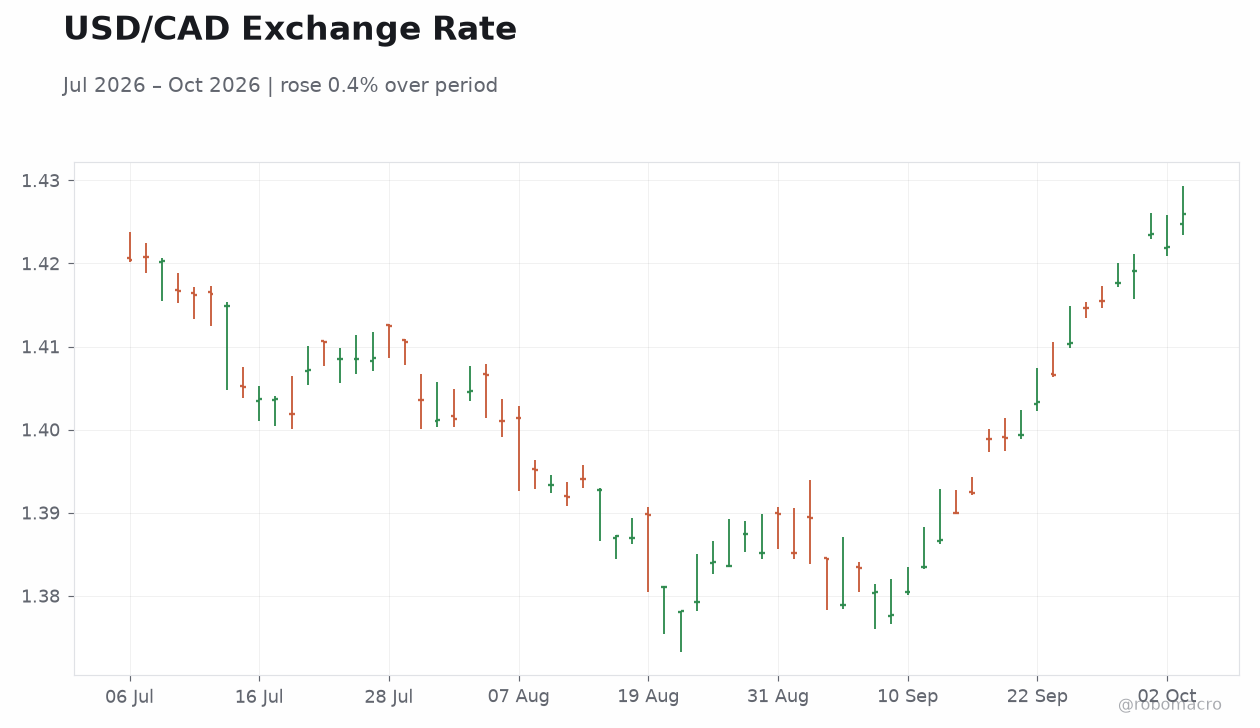
| USD/CAD | 1.43 | +0.28% |
| EUR/CAD | 1.60 | -0.09% |
| WTI Crude | 89.79 | -1.45% |
| Natural Gas | 3.03 | -0.10% |
| Gold | 4,195.40 | +0.80% |
| Brent Crude | 101.93 | -0.31% |
| Bitcoin | 86,070.75 | -0.47% |
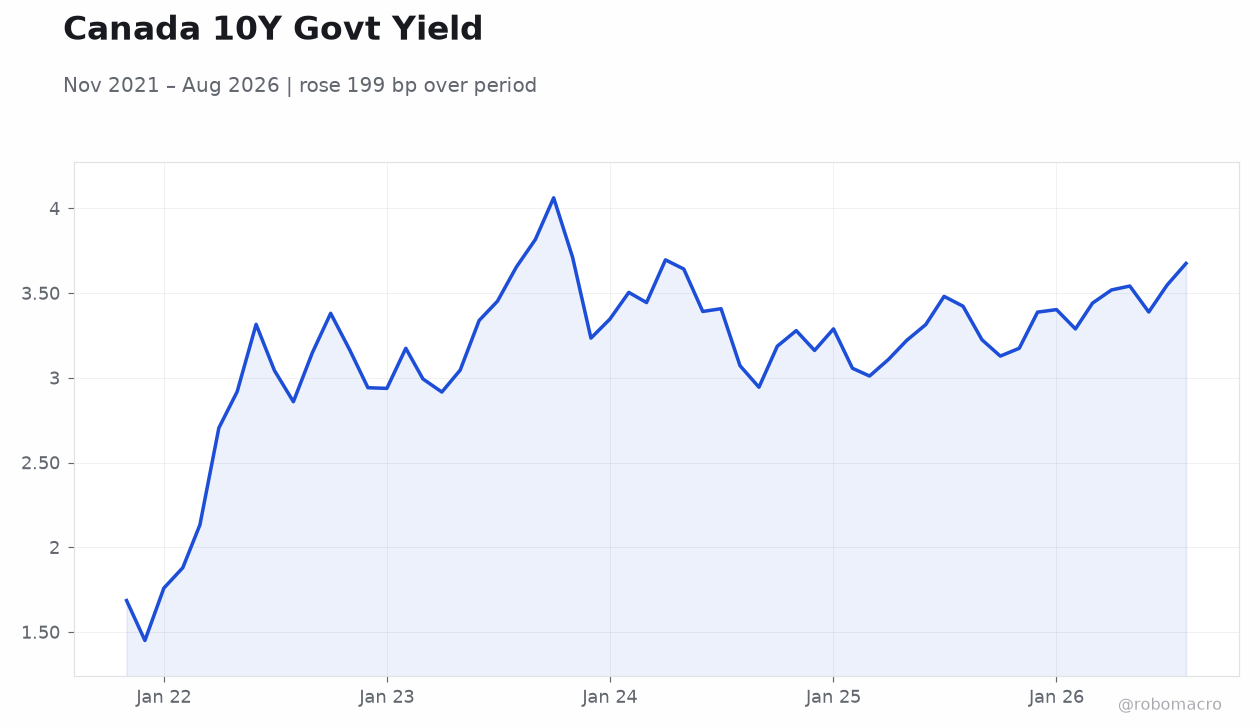
| Canada 2Y Govt Yield | 3.27% | -10 bp |
| Canada 10Y Govt Yield | 3.94% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
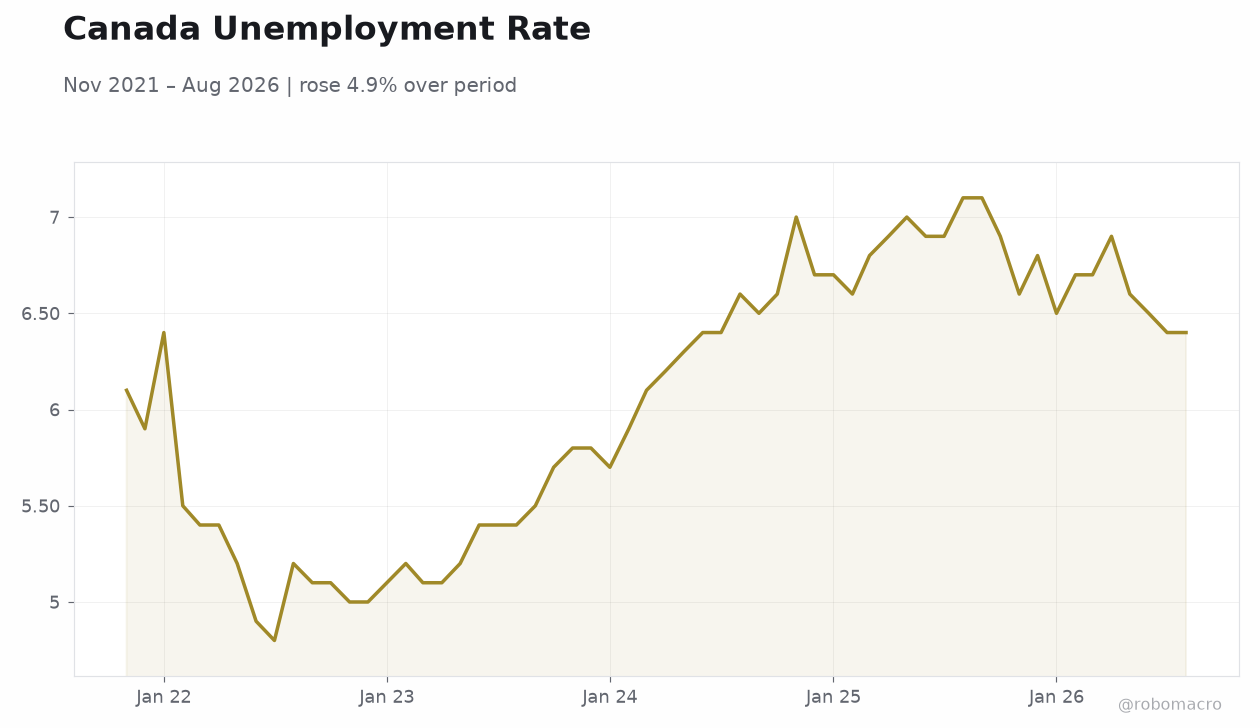 Canada Unemployment Rate | Type: macro_line | Unemployment Rate %: 6.4 (2026-08-01) | Range: 4.8–7.1 | Trend(5pt): 6.1,5.1,6.1,7,6.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-10-06) | |||
| Trade Balance | 770m | 1,300m | 08:30 |
| Ivey PMI Seasonally Adjusted | 64.30 | 65.20 | 10:00 |
| Friday (2026-10-09) | |||
| Headline Unemployment Rate | 6.40 | 6.50 | 08:30 |
| Employment Change | -41,700 | 9,500 | 08:30 |
| Full-Time Employment Change | -35,900 | - | 08:30 |
| Labor Force Participation | 65 | - | 08:30 |
| Part-Time Employment Change | -5,800 | - | 08:30 |
- S&P/TSX rose 0.99% to 35,502.70 while Canada 2-year yields fell 10 bp to 3.27%.
- USD/CAD climbed 0.28% to 1.43 amid tariff concerns and weakening oil-CAD link.
- Trade Balance and Ivey PMI due tomorrow; September jobs data follow on Friday.
Yesterday's Recap
Canadian markets advanced on October 4 with the S&P/TSX Composite closing at 35,502.70, up 0.99%. The Canada 2-year government yield dropped 10 bp to 3.27% and the 10-year yield eased 2 bp to 3.94%. USD/CAD rose 0.28% to 1.43 while WTI crude fell 1.45% to 89.79.
No economic data were released. News highlighted upcoming employment figures as tariffs weigh on the outlook and a Bank of Canada official stressed housing supply over rate policy to address affordability. Inflation readings showed mixed gasoline effects, with one report citing a rebound to 3.00% and another noting a decline to 2.3%.
Royal Bank of Canada shares gained but lagged the broader index.
The Day Ahead
Canada Trade Balance is scheduled for release at 08:30 ET on October 6 with consensus at C$1.3 billion versus the prior C$770 million. The Ivey PMI Seasonally Adjusted follows at 10:00 ET, expected at 65.2 after 64.3 last month. Both prints carry medium-to-high impact and will shape near-term CAD and rate expectations.
Markets will also monitor any tariff-related headlines that could influence sentiment ahead of Friday’s labour report. No Bank of Canada speeches are listed.
Other Economic Notes
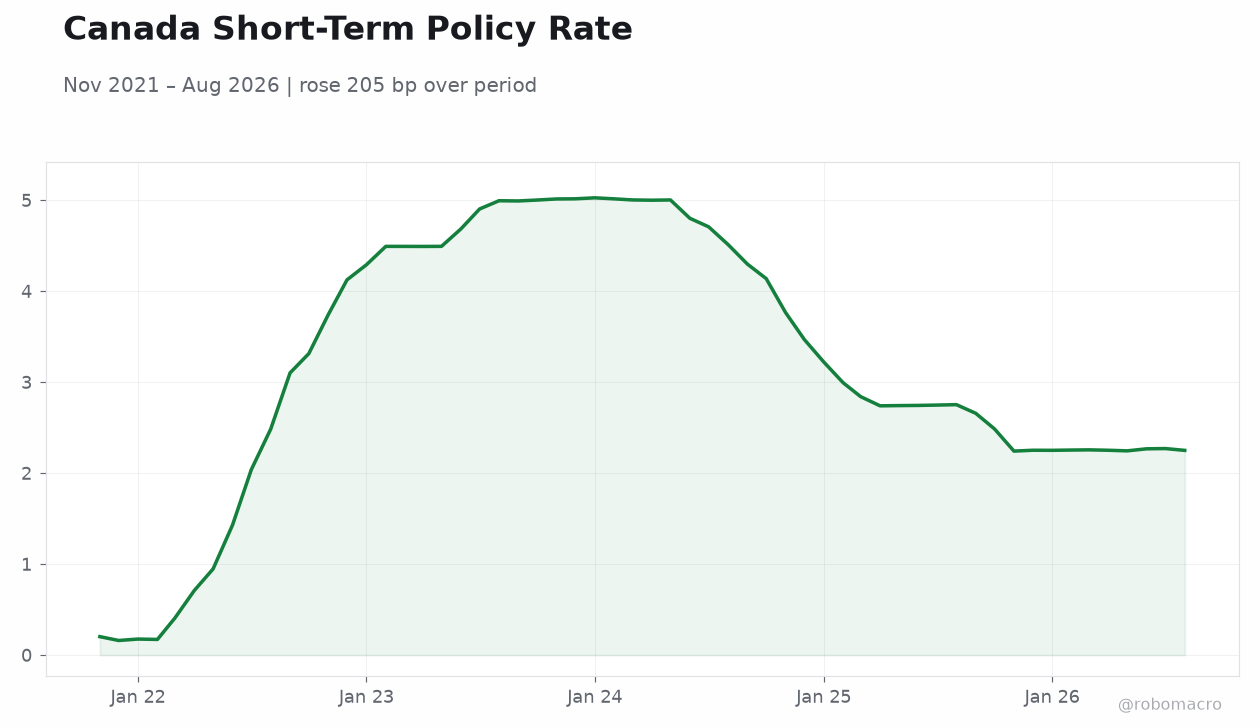
Tariff uncertainty continues to cloud Canada’s growth outlook and supports bets against the currency. Inflation remains anchored near the 3.00% level reported for August, with gasoline price swings driving recent volatility. Housing affordability discussions centre on supply constraints rather than further monetary easing.
Equity investors favour domestic resilience themes, lifting the TSX despite mixed bank performance. Broader commodity moves, especially softer crude, add pressure to export-oriented sectors.
Global Macro News
The Canadian dollar extended its weekly losing streak as interest-rate spreads widened against the US. Its traditional link to oil prices has weakened, amplifying short positions amid tariff risks. The euro gained on the CAD ahead of Eurozone HICP data while ECB’s Lane flagged growth concerns.
↓ p.2