Canada Macro Daily(Beta Mode)
TSX Holds as PMI and Trade Data Loom
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,518.60 | +0.04% |
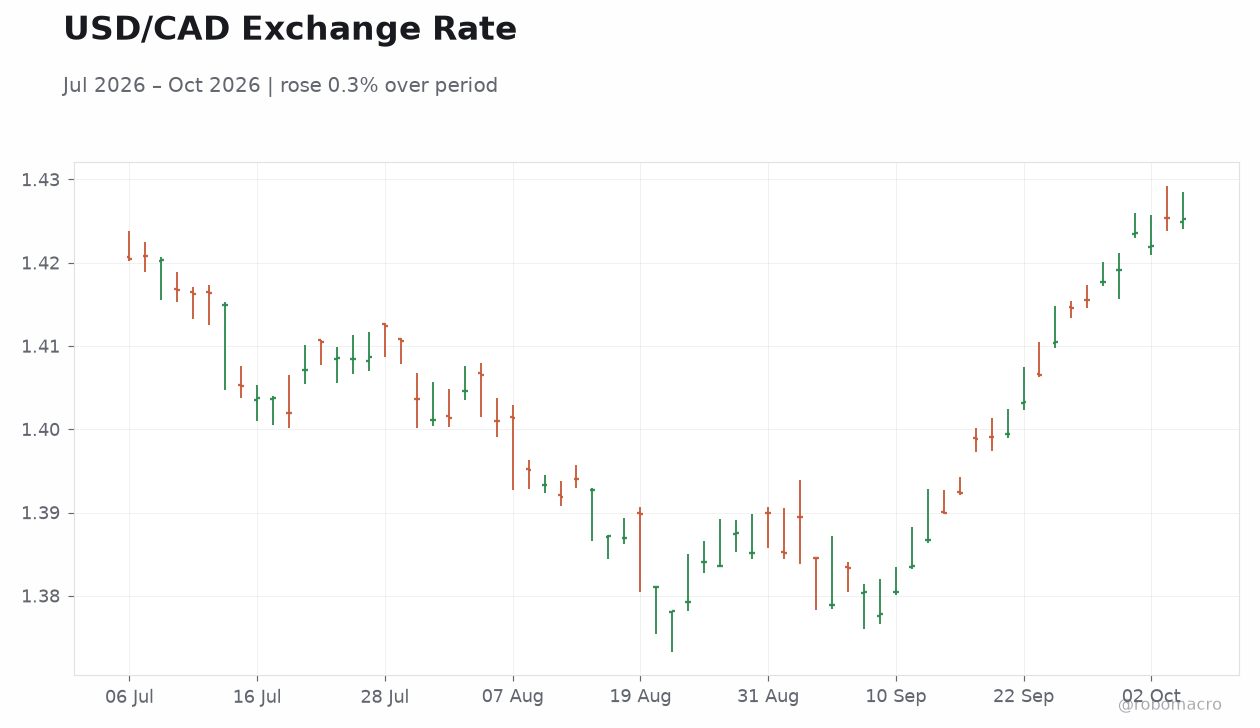
| USD/CAD | 1.43 | -0.00% |
| EUR/CAD | 1.61 | +0.07% |
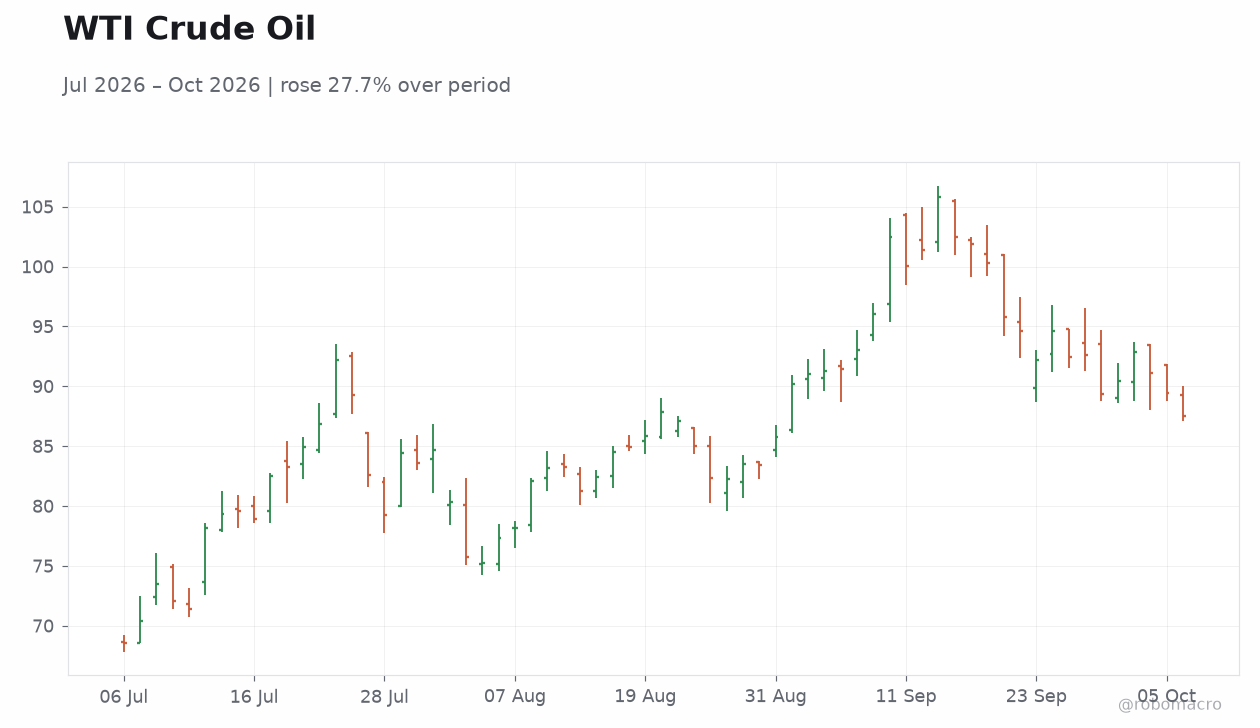
| WTI Crude | 87.58 | -2.07% |
| Natural Gas | 3.09 | +0.62% |
| Gold | 4,192.70 | +0.86% |
| Brent Crude | 98.26 | -2.05% |
| Bitcoin | 86,329.94 | +0.63% |
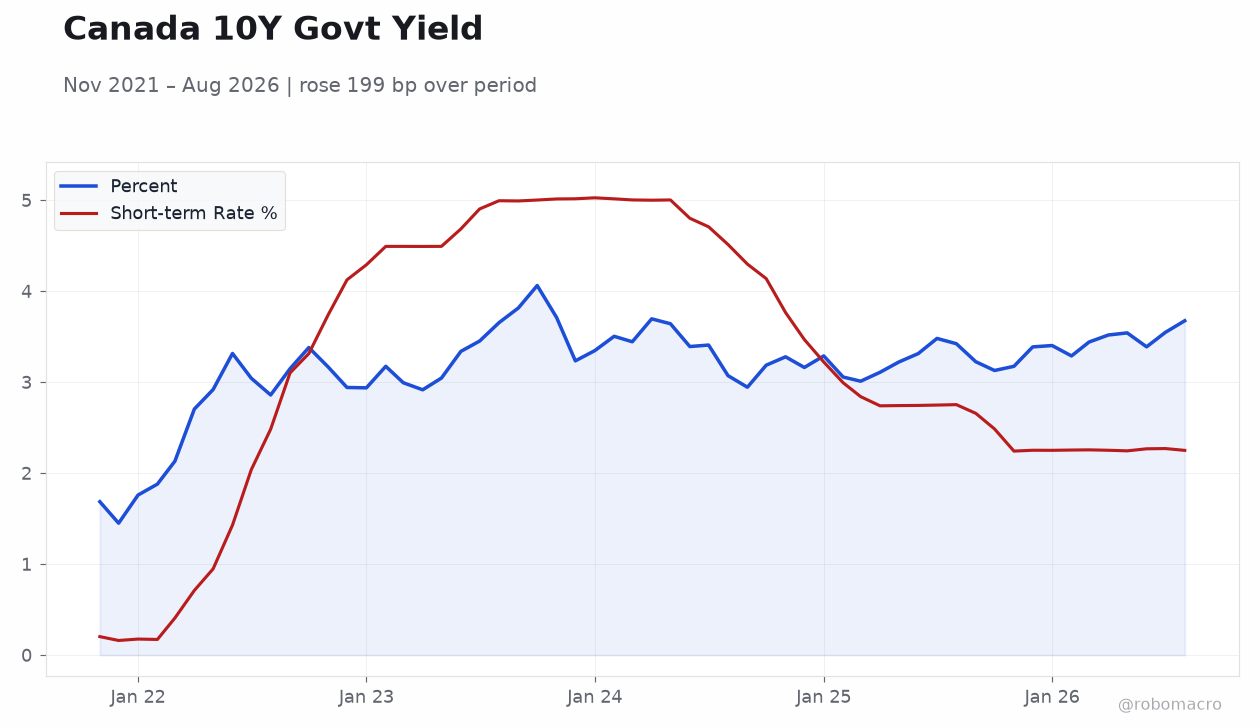
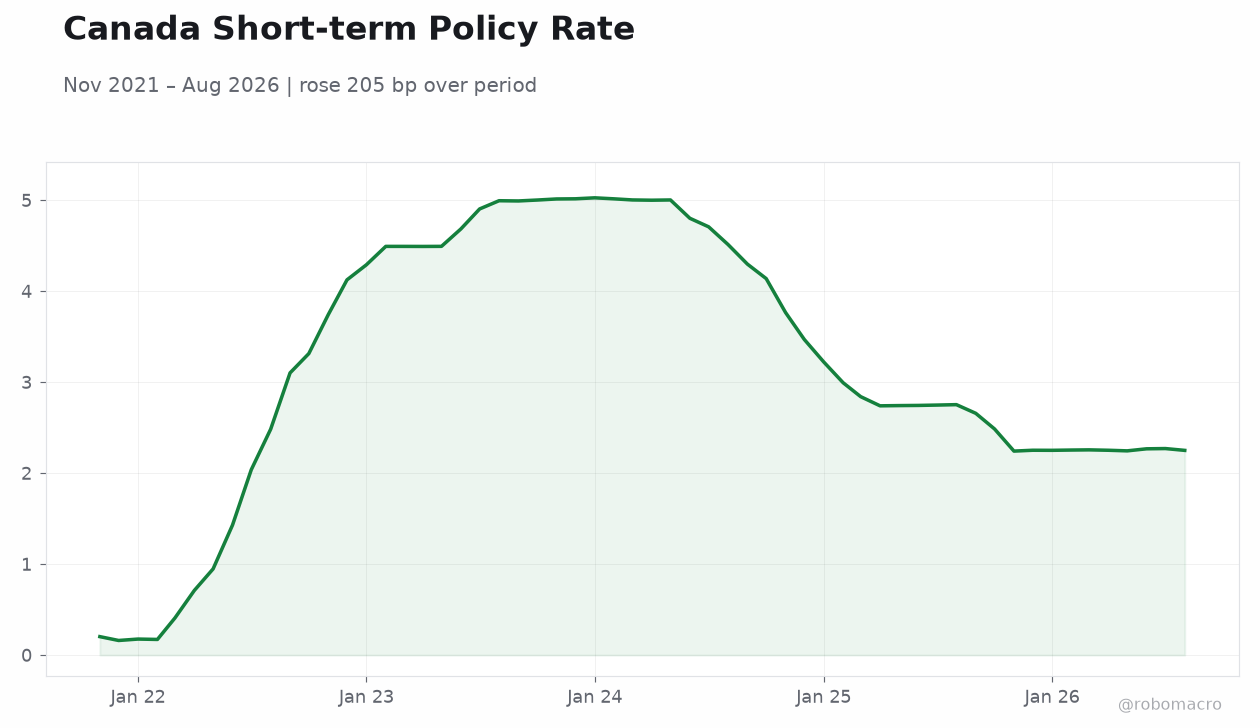
| Canada 2Y Govt Yield | 3.25% | -2 bp |
| Canada 10Y Govt Yield | 3.93% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
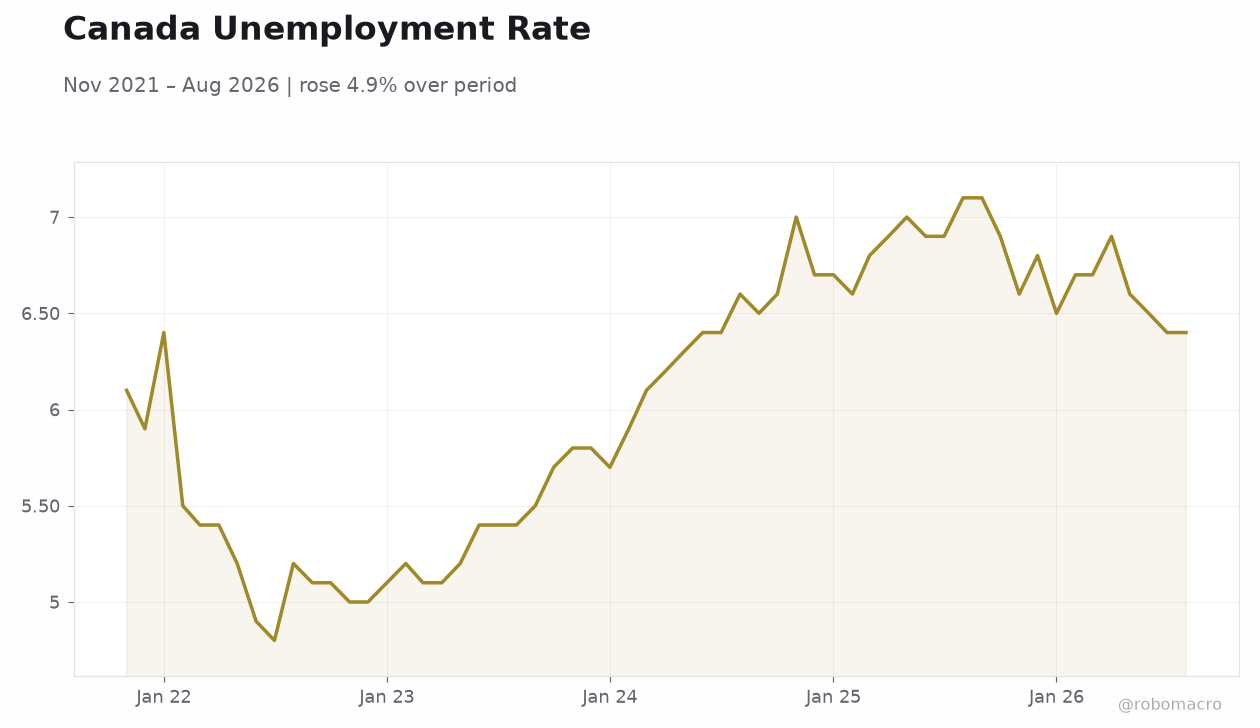 Canada Unemployment Rate | Type: macro_line | Percent: 6.4 (2026-08-01) | Range: 4.8–7.1 | Trend(5pt): 6.1,5.1,6.1,7,6.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | 770m | 1,700m | 08:30 |
| Ivey PMI Seasonally Adjusted | 64.30 | 65.20 | 10:00 |
| Friday (2026-10-09) | |||
| Headline Unemployment Rate | 6.40 | 6.50 | 08:30 |
| Employment Change | -41,700 | 7,000 | 08:30 |
| Full-Time Employment Change | -35,900 | - | 08:30 |
| Labor Force Participation | 65 | - | 08:30 |
| Part-Time Employment Change | -5,800 | - | 08:30 |
- Ivey PMI and trade balance due today with potential to shift CAD and short-end yields
- WTI crude fell 2.07% while Canada 2-year yield eased 2 bp to 3.25%
- KPMG flags bond-market pressure for possible December BoC hike despite soft growth signals
Yesterday's Recap
The S&P/TSX Composite edged up 0.04% to 35,518.60 as energy shares weighed on the index. WTI crude declined 2.07% to 87.58 and Brent crude fell 2.05% to 98.26, pressuring the Canadian dollar. Natural gas rose 0.62% to 3.09 while gold advanced 0.86% to 4,192.70.
USD/CAD held steady at 1.43 and EUR/CAD rose 0.07% to 1.61. Canada 2-year government yield fell 2 bp to 3.25% and the 10-year yield declined 1 bp to 3.93%. No Canadian economic data were released on October 5.
A Bank of Canada security-guard strike passed the 100-day mark while reports highlighted ongoing weakness in services activity that deepened growth concerns.
The Day Ahead
Markets will focus on two Canadian releases scheduled for October 6. The trade balance at 08:30 ET carries a consensus of C$1.7 billion against a prior C$0.77 billion. The Ivey PMI seasonally adjusted print at 10:00 ET is expected at 65.2 versus 64.3 previously and carries high market impact.
A stronger-than-expected Ivey reading could support CAD and lift short-term yields while a miss may reinforce expectations for steady policy. No Bank of Canada speeches or additional data are listed for the session. Attention will also turn to Friday’s labour-market report that includes the unemployment rate and employment change.
Other Economic Notes
The Bank of Canada noted that Canada still faces a lengthy path to restore housing affordability amid elevated borrowing costs. KPMG Canada highlighted that bond markets are demanding credibility and could push the central bank toward a December rate hike followed by a wait-and-see stance. The 100-day security-guard strike at the Bank of Canada continues without resolution and adds operational friction.
Heavy trading in Royal Bank of Canada and National Bank of Canada shares reflected investor focus on domestic bank earnings and credit conditions. Broader services weakness has kept growth concerns elevated even as inflation prints remain above target.