Canada Macro Daily(Beta Mode)
Loonie Firms, Yields Ease as BoC Pause Bets Build
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,984.00 | +0.90% |
| USD/CAD | 1.42 | -0.44% |
| EUR/CAD | 1.59 | -0.25% |
| WTI Crude | 95.87 | +1.84% |
| Natural Gas | 3.26 | -0.73% |
| Gold | 4,161.80 | -0.37% |
| Brent Crude | 106.30 | +0.58% |
| Bitcoin | 83,343.31 | +0.30% |
| Canada 2Y Govt Yield | 3.18% | -6 bp |
| Canada 10Y Govt Yield | 3.86% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoC Gov Macklem Speech | - | - | - |
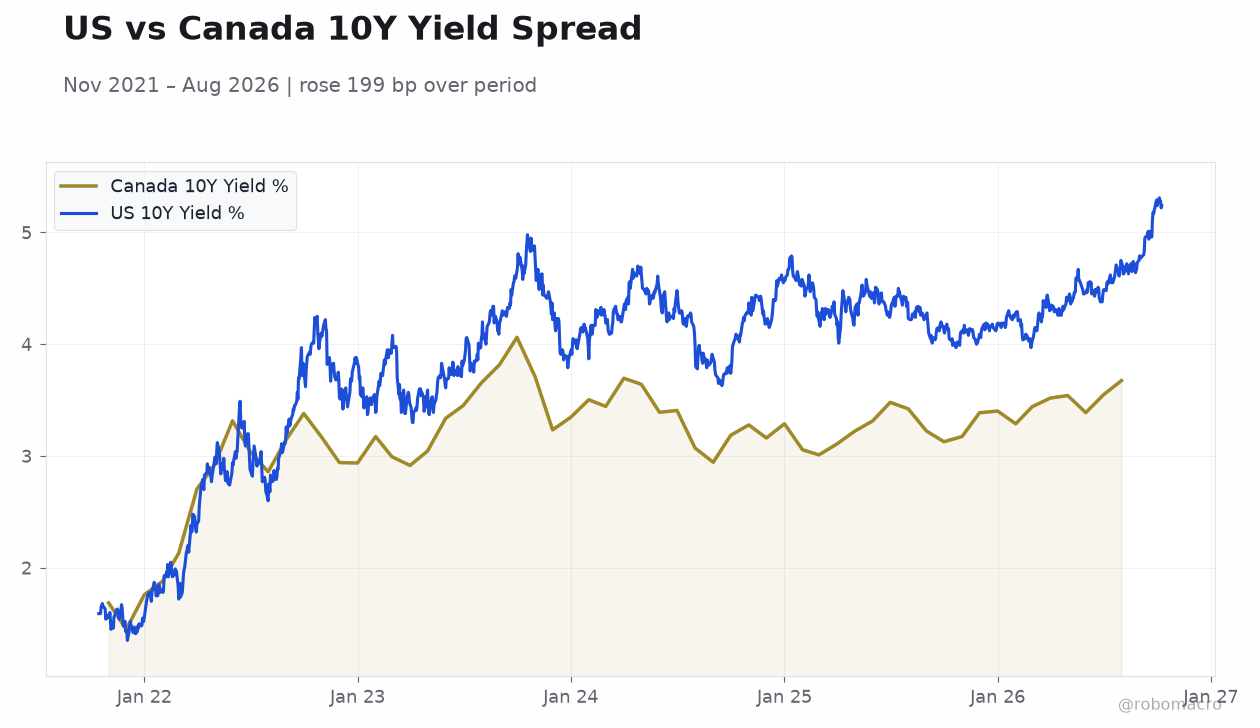 US vs Canada 10Y Yield Spread | Type: macro_line | Canada 10Y Yield %: 3.675 (2026-08-01) | Range: 1.45–4.062 | Trend(6pt): 1.686,2.938,3.444,3.221,3.547,3.675 | US 10Y Yield %: 5.24 (2026-10-09) | Range: 1.35–5.31 | Trend(6pt): 1.59,3.53,4.5,4.43,5.22,5.24
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-10-15) | |||
| BoC Rogers Speech | - | - | 05:00 |
| Friday (2026-10-16) | |||
| BoC Gov Macklem Speech | - | - | 00:15 |
| Housing Starts Level | 229,000 | 232,500 | 08:15 |
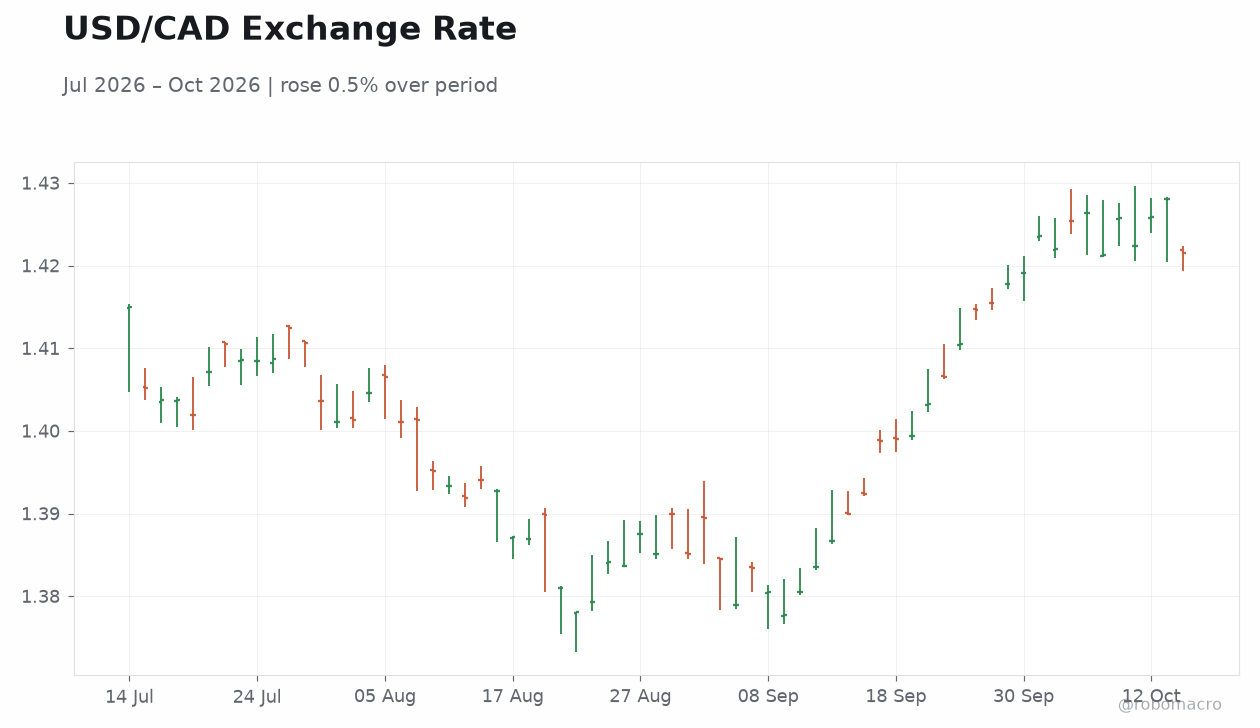
- The S&P/TSX gained 0.90% to 35,984 while USD/CAD slipped 0.44% to 1.42, with the loonie holding near 18-month lows against a broadly firm dollar.
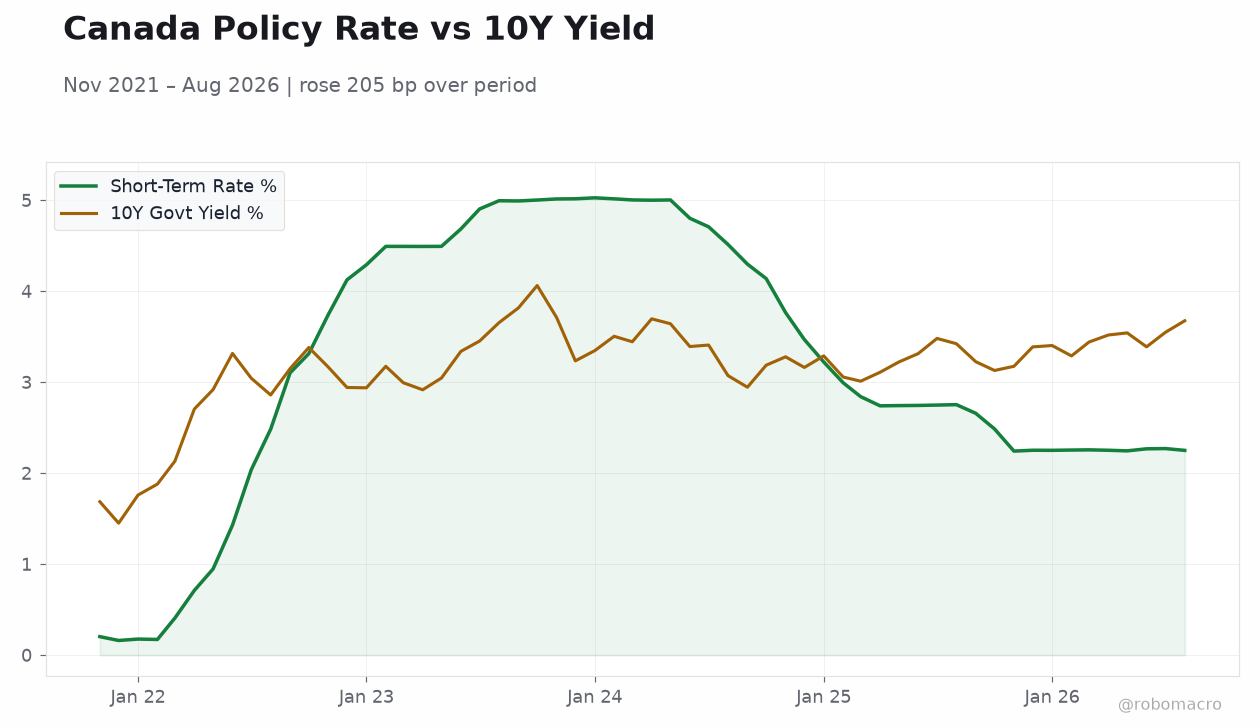
- Government of Canada yields eased across the curve, with the 2-year down 6 bp to 3.18% and the 10-year down 7 bp to 3.86%, as markets trim tightening odds after soft labour data.
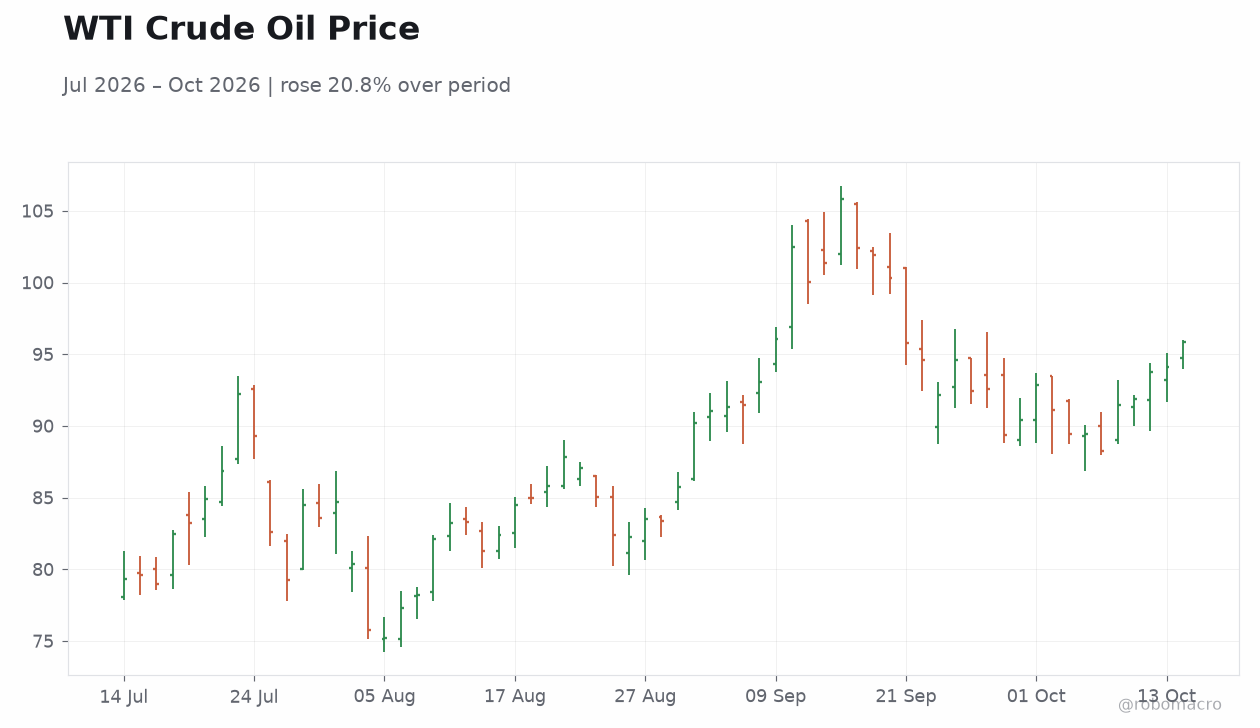
- WTI crude rallied 1.84% to $95.87, lending support to the energy-heavy TSX, while BoC speakers dominate the week's calendar.
Yesterday's Recap
Canadian markets caught a bid on Tuesday despite a thin domestic data calendar. The S&P/TSX advanced 0.90% to 35,984, led by energy names as WTI crude surged 1.84% to $95.87 and Brent added 0.58% to $106.30. The Canadian dollar strengthened, with USD/CAD falling 0.44% to 1.42 and EUR/CAD easing 0.25% to 1.59, though the loonie remains close to April 2025 lows against a resilient greenback.
Fixed income rallied alongside equities in a risk-on configuration: the 2-year yield declined 6 bp to 3.18% and the 10-year fell 7 bp to 3.86%. Gold retreated 0.37% to $4,161.80, while natural gas slipped 0.73% to $3.26. Bitcoin edged up 0.30% to $83,343.
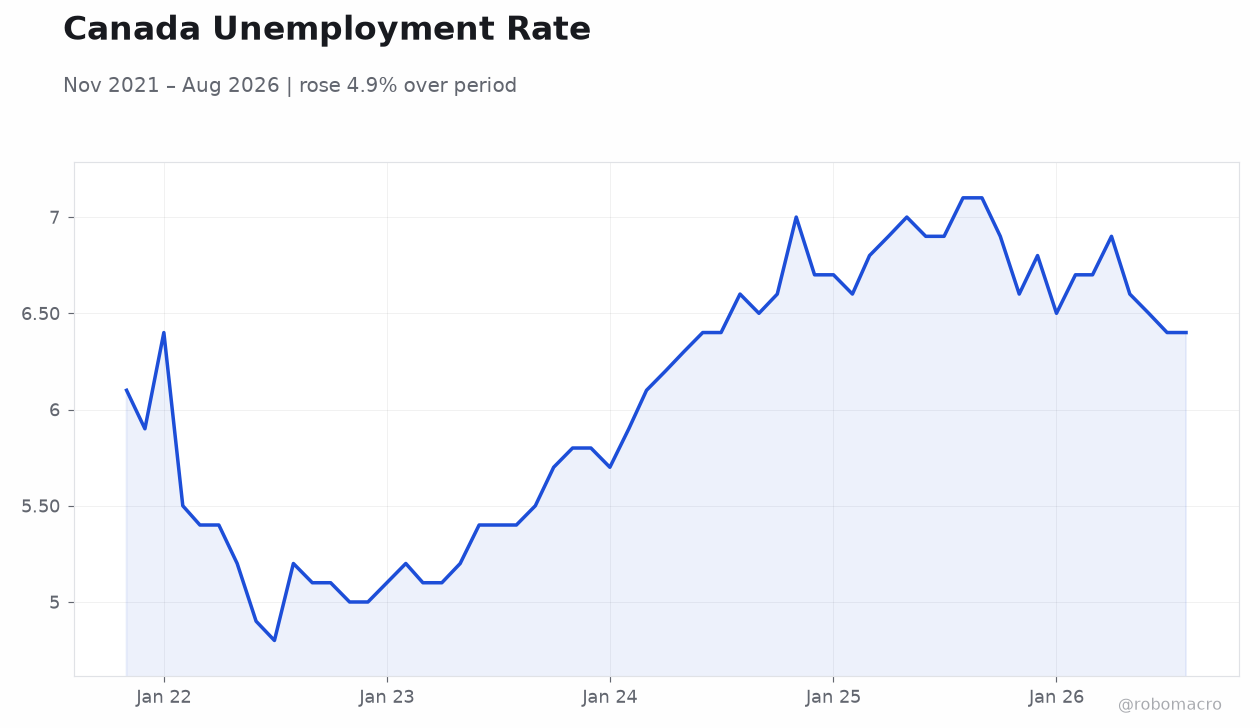
On the policy front, BoC Governor Tiff Macklem spoke overnight, with his remarks parsed for signals on the path from the current 2.25% policy rate. The session's tone reflected growing conviction that the Bank of Canada is in an extended holding pattern following recent job losses that pushed October hike odds down to roughly 25% in market pricing.
The Day Ahead
The calendar turns heavier through the balance of the week. Senior Deputy Governor Carolyn Rogers speaks Thursday at 05:00 ET, offering another window into the Governing Council's thinking on the inflation outlook and the appropriate length of the pause. Friday brings two domestic items: Governor Macklem returns to the podium at 00:15 ET, a high-impact appearance likely to move front-end pricing, and Housing Starts at 08:15 ET, where consensus looks for 232,500 annualized units versus the prior 229,000.
Housing data will be scrutinized for evidence of how higher mortgage costs are filtering through residential construction, a key channel in the BoC's tightening transmission. With no major Canadian CPI or GDP prints until later in the month, this week's speeches carry outsized weight for rate expectations. Traders will also watch US CPI for spillover effects on USD/CAD.
Other Economic Notes
Structural labour dynamics are coming into focus, with Bank of Canada research flagging demographic changes that will shrink Canada's workforce — a supply-side constraint with implications for potential growth and the neutral rate debate. ↓ p.2