Canada Macro Daily(Beta Mode)
BoC Set for First Rate Hike Since 2023
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,788.20 | -0.52% |
| USD/CAD | 1.40 | +0.08% |
| EUR/CAD | 1.57 | -0.15% |
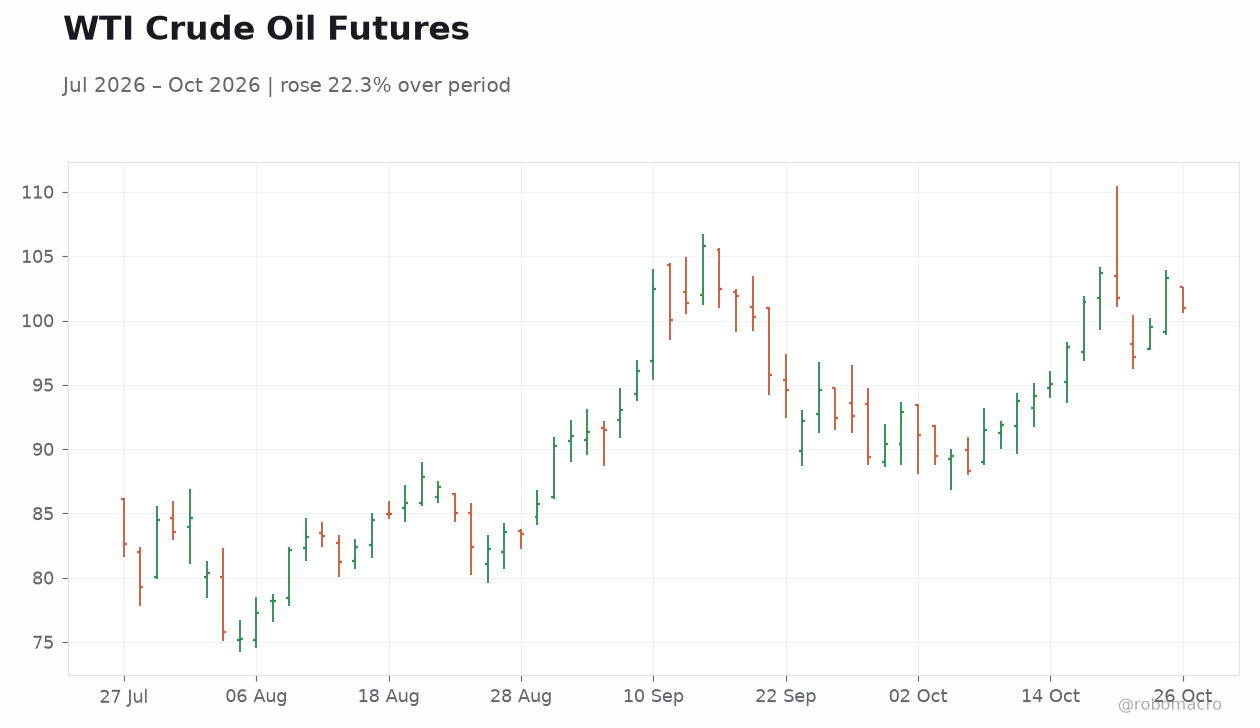
| WTI Crude | 101.08 | -2.12% |
| Natural Gas | 3.02 | +14.32% |
| Gold | 4,025.00 | +0.43% |
| Brent Crude | 109.94 | -5.81% |
| Bitcoin | 80,221.90 | +0.25% |
| Canada 2Y Govt Yield | 3.22% | -10 bp |
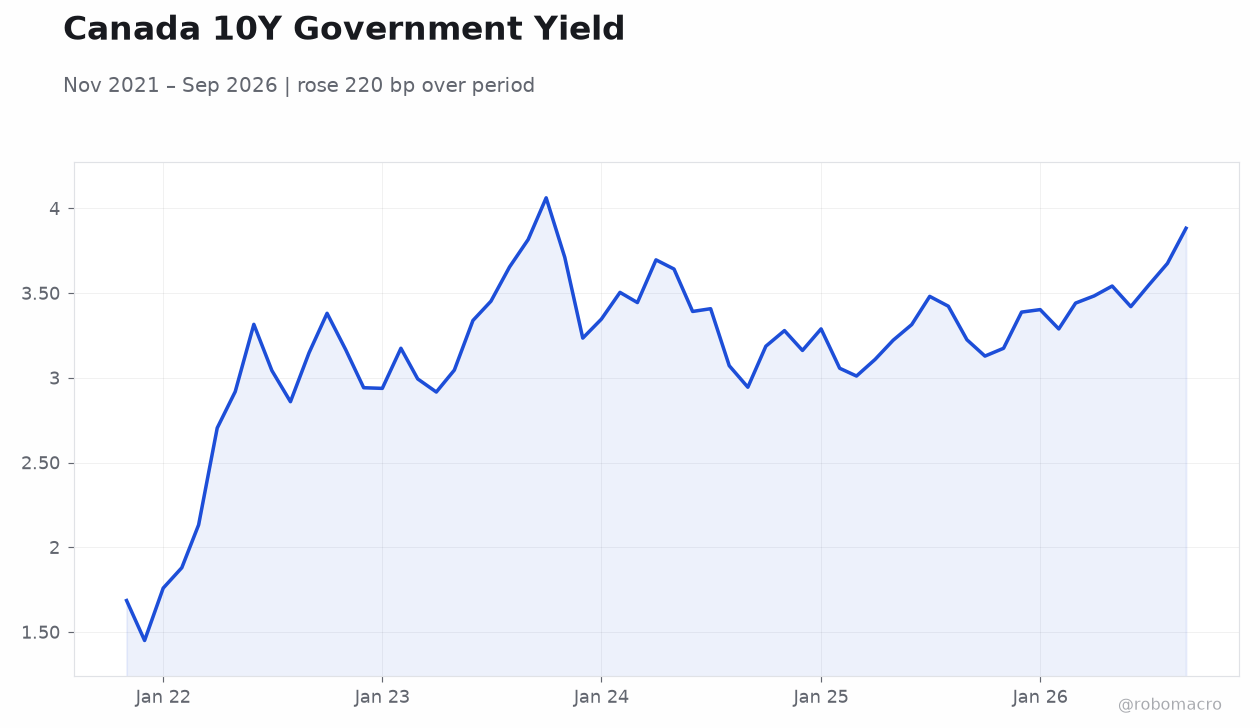
| Canada 10Y Govt Yield | 3.78% | -12 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
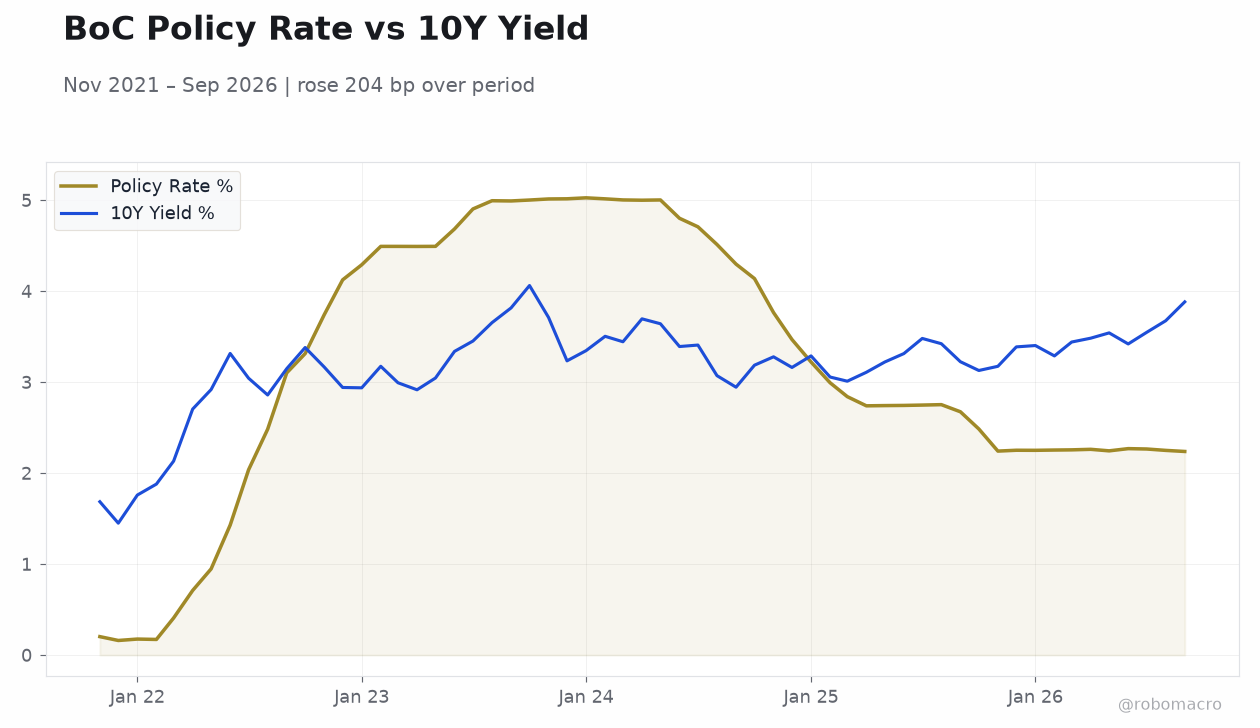 BoC Policy Rate vs 10Y Yield | Type: macro_line | Policy Rate %: 2.238 (2026-09-01) | Range: 0.1604–5.026 | Trend(6pt): 0.2027,4.29,5.003,2.742,2.265,2.238 | 10Y Yield %: 3.882 (2026-09-01) | Range: 1.45–4.062 | Trend(6pt): 1.686,2.938,3.444,3.221,3.547,3.882
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-10-28) | |||
| BoC Interest Rate Decision | 2.25 | 2.50 | 09:45 |
| BoC Monetary Policy Report | - | - | 09:45 |
| BoC Press Conference | - | - | 10:30 |
| Friday (2026-10-30) | |||
| GDP Month-over-Month | 0 | 0.20 | 08:30 |
| GDP Month-over-Month Prel | - | - | 08:30 |
- Markets price full 25 bp BoC hike on October 28 amid energy-driven inflation pressures.
- Canadian yields fell sharply last week while the loonie held gains despite softer oil.
- Weak growth backdrop clashes with rising CPI, forcing BoC into preemptive tightening.
Yesterday's Recap
Canadian markets closed lower on October 25 with the S&P/TSX declining 0.52 percent to 35,788.20. The 2-year Government of Canada yield eased 10 basis points to 3.22 percent while the 10-year yield dropped 12 basis points to 3.78 percent. USD/CAD rose 0.08 percent to 1.40 as the Canadian dollar posted modest gains against a softer greenback.
WTI crude fell 2.12 percent to 101.08 dollars per barrel and Brent dropped 5.81 percent, yet natural gas surged 14.32 percent to 3.02 dollars. Gold advanced 0.43 percent to 4,025.00 dollars per ounce. No major Canadian data releases occurred, leaving price action driven by positioning ahead of the Bank of Canada decision and ongoing Middle East energy supply concerns.
The Day Ahead
The Bank of Canada will announce its interest rate decision at 9:45 a.m. ET on October 28, followed immediately by the Monetary Policy Report and a press conference at 10:30 a.m. Markets fully price a 25 basis point increase that would lift the policy rate to 2.50 percent from the current 2.25 percent level.
Attention will center on revised staff projections for inflation and growth contained in the MPR. Two days later, Statistics Canada will release September GDP at 8:30 a.m. ET on October 30, with consensus calling for a 0.2 percent month-over-month gain after a flat August print.
Traders will also monitor any follow-through comments from Governing Council members on the inflation outlook.
Other Economic Notes
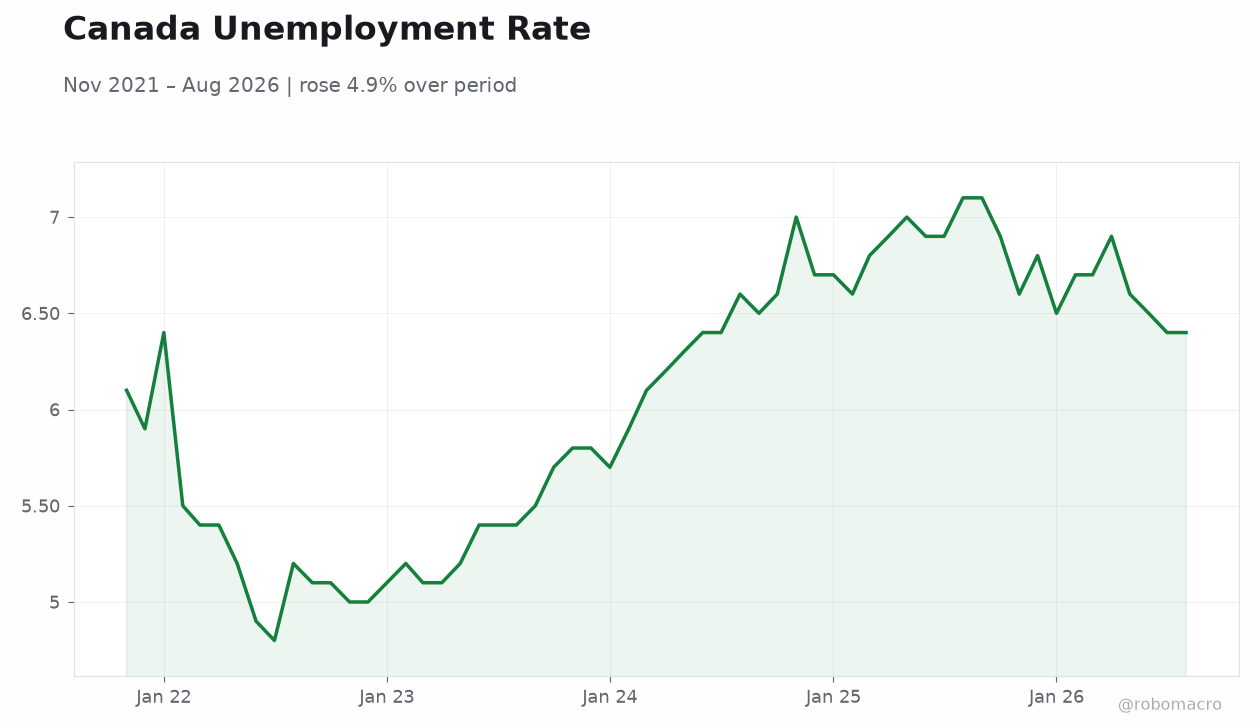
Canada’s economy remains soft yet faces building price pressures from elevated energy costs linked to geopolitical tensions. The September CPI reading of 3.09 percent year-over-year already exceeds the Bank of Canada’s 2 percent target, prompting debate over whether weak demand justifies further accommodation. Business Outlook Survey results released last week showed firms reporting higher selling prices and persistent cost pressures, reinforcing the case for earlier tightening.
Bond markets have responded with a steepening curve as short-term yields price faster policy normalization while longer-term yields reflect growth concerns. ↓ p.2