Canada Macro Daily(Beta Mode)
BoC Hikes to 2.50%, Signals More Possible
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 36,204.86 | -0.17% |
| USD/CAD | 1.40 | -0.28% |
| EUR/CAD | 1.56 | -0.33% |
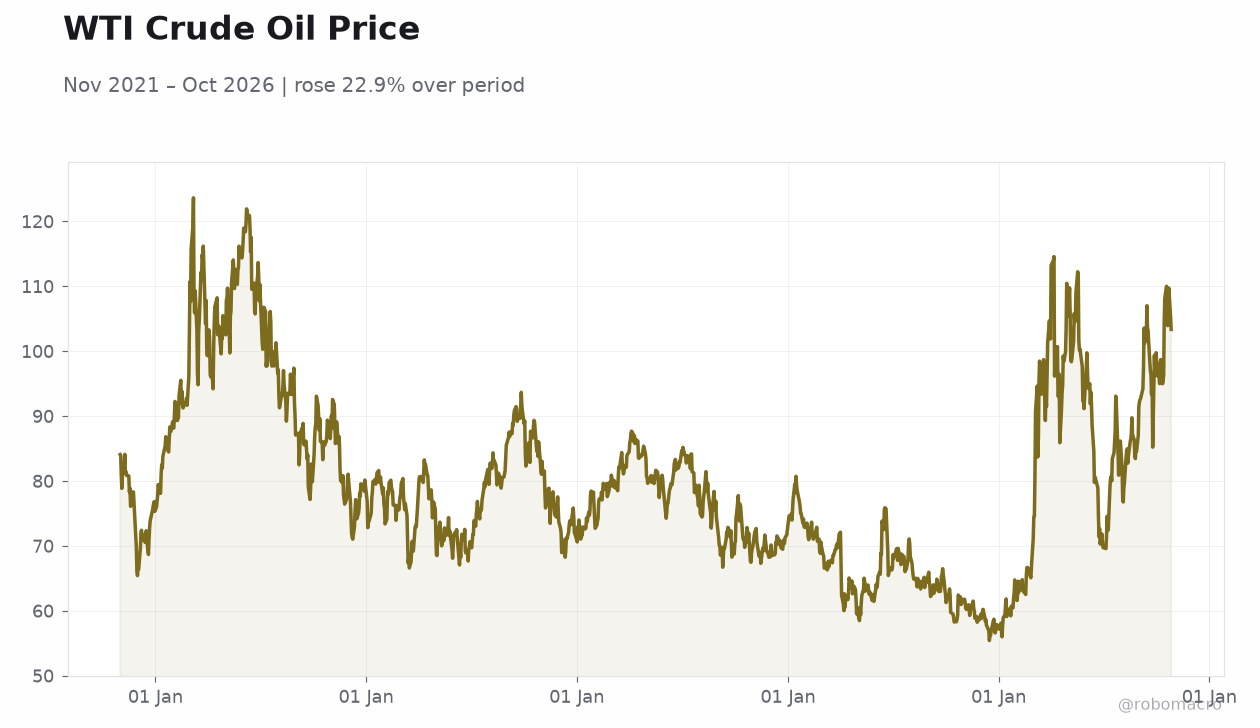
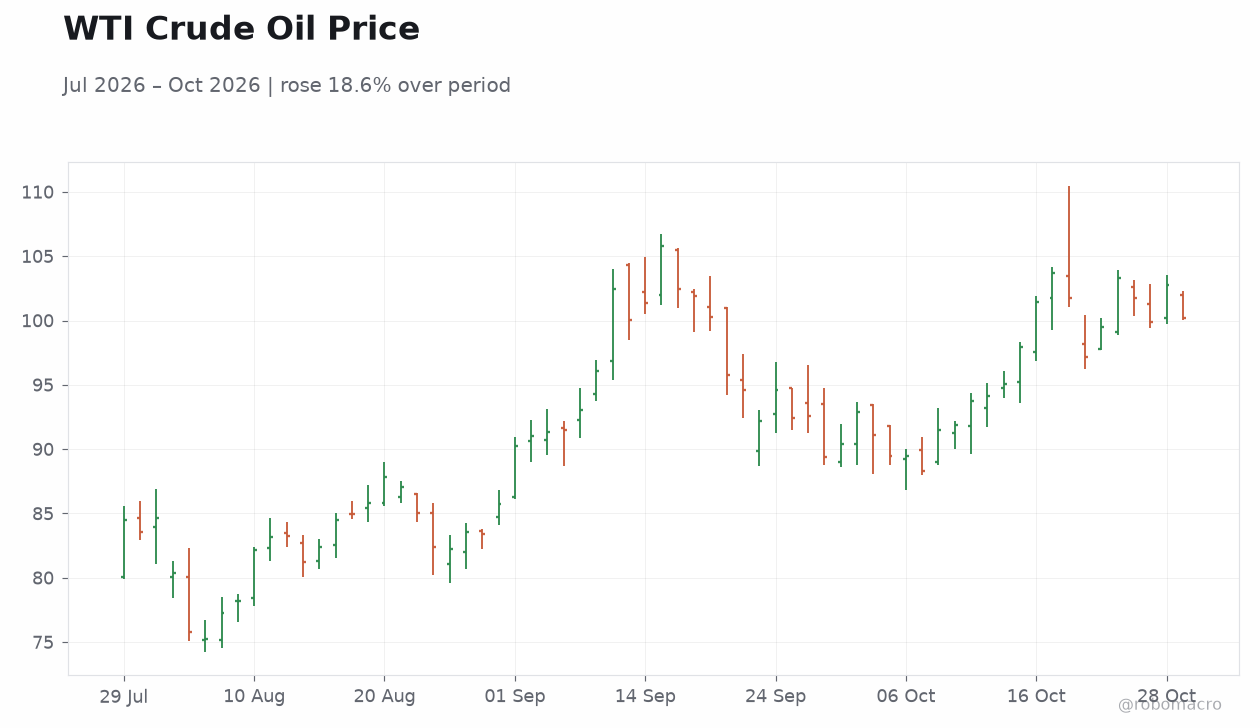
| WTI Crude | 100.09 | -2.62% |
| Natural Gas | 2.94 | +4.51% |
| Gold | 4,045.10 | -0.16% |
| Brent Crude | 109.27 | -5.25% |
| Bitcoin | 79,836.53 | -1.76% |
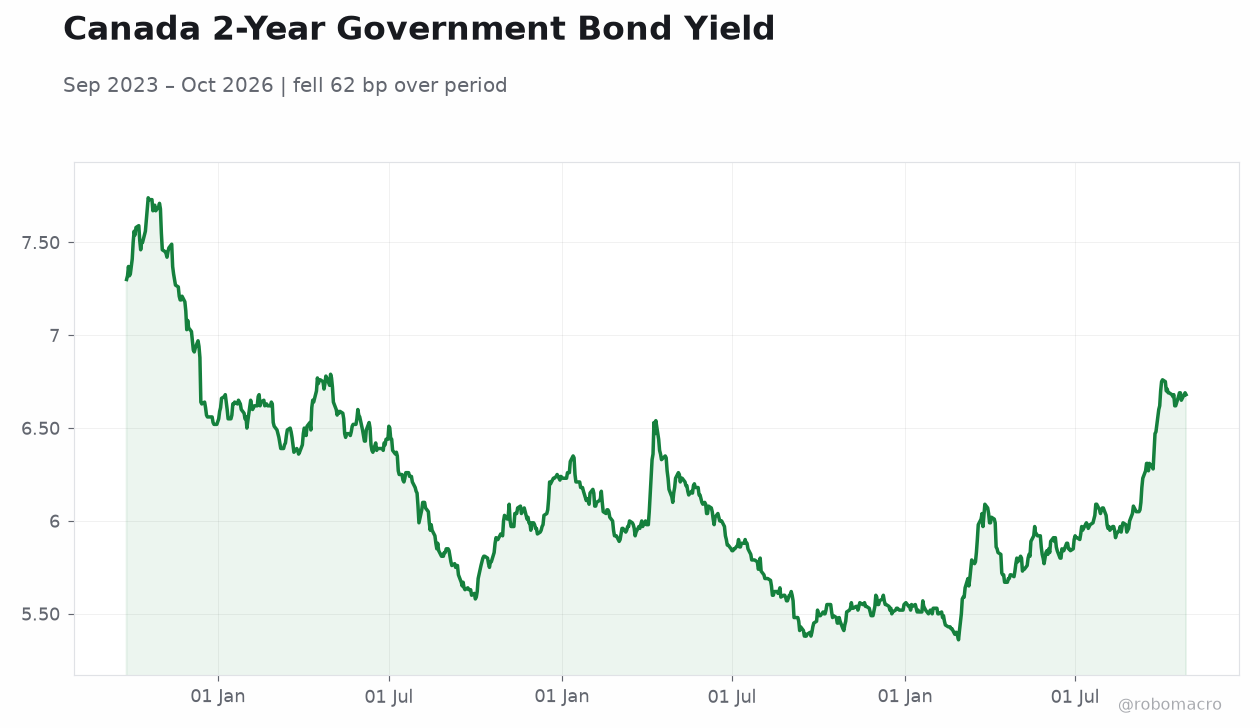
| Canada 2Y Govt Yield | 3.41% | +5 bp |
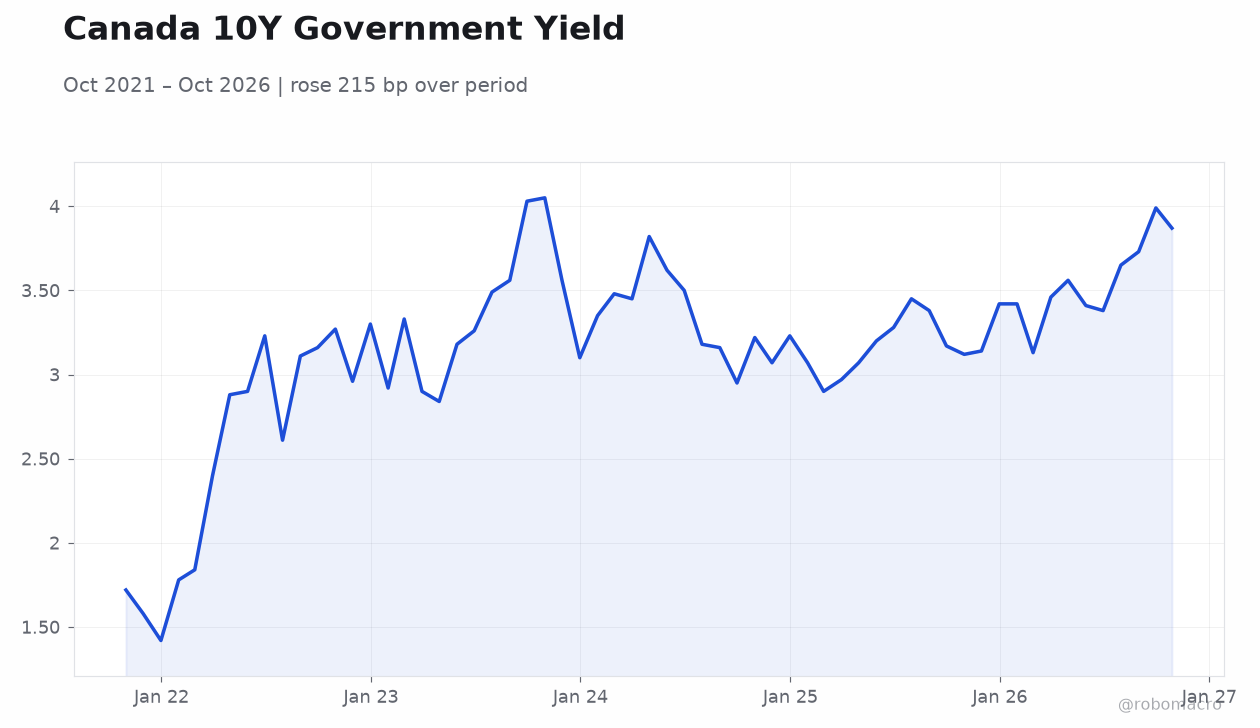
| Canada 10Y Govt Yield | 3.87% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoC Interest Rate Decision | 2.25 | 2.50 | 2.50 |
| BoC Monetary Policy Report | - | - | - |
| BoC Rate Statement | - | - | - |
| BoC Press Conference | - | - | - |
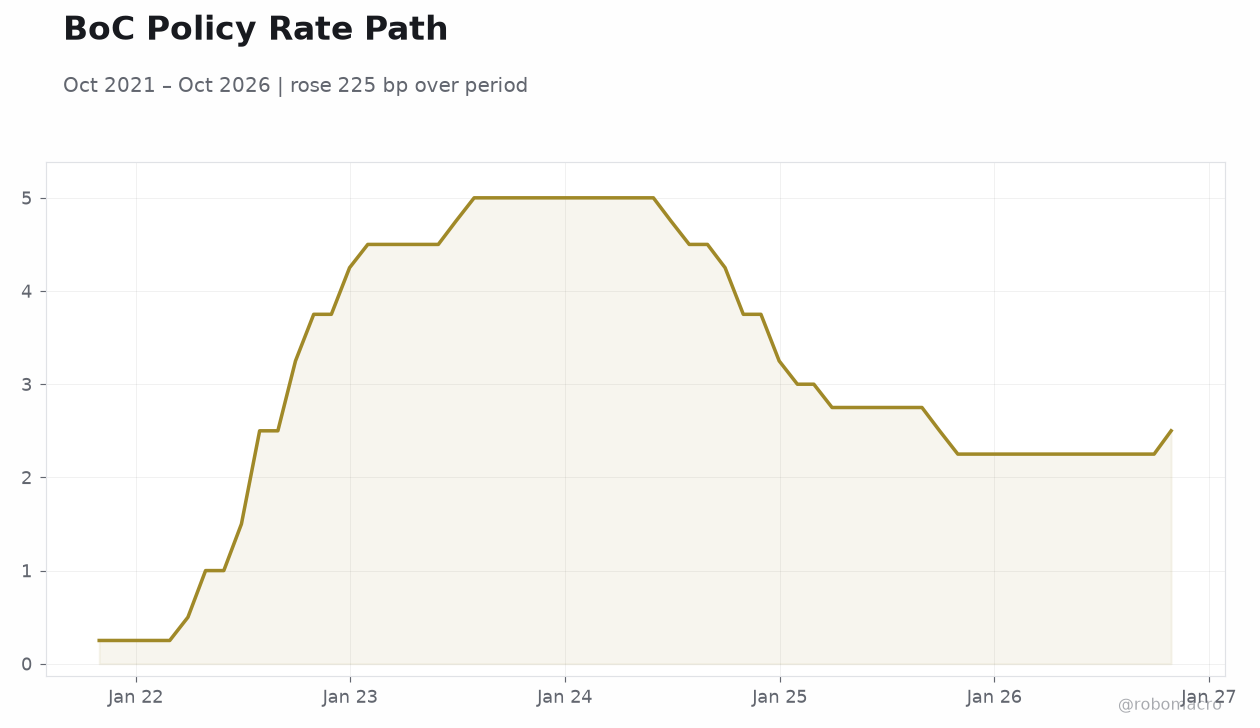 BoC Policy Rate Path | Type: macro_line | Policy Rate (%): 2.5 (2026-10-29) | Range: 0.25–5 | Trend(5pt): 0.25,4.5,5,2.75,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Friday (2026-10-30) | |||
| GDP Month-over-Month | 0 | 0.20 | 08:30 |
| GDP Month-over-Month Prel | - | - | 08:30 |
- Bank of Canada raised its overnight rate 25 bp to 2.50% on Oct 28, its first hike since 2023, and flagged further tightening may be needed
- Canadian 2Y and 10Y yields rose 5 bp and 4 bp respectively as markets repriced the policy path; CAD firmed modestly against USD
- Oil slumped sharply (Brent -5.25%, WTI -2.62%) even as Middle East supply risks linger; TSX slipped 0.17%
Yesterday's Recap
The Bank of Canada delivered a 25 bp increase to its overnight rate, lifting the policy rate to 2.50% from 2.25% — the first hike since July 2023 — matching consensus expectations of 2.50%. Alongside the decision, the BoC published its Monetary Policy Report and Rate Statement, with the accompanying press conference reinforcing a hawkish tilt and explicitly noting another hike remains possible. Markets responded in textbook fashion: the Canada 2Y yield climbed 5 bp to 3.41% and the 10Y rose 4 bp to 3.87%, steepening modestly as front-end repricing led.
USD/CAD fell 0.28% to 1.40, reflecting a firmer loonie on the hawkish surprise relative to prior guidance, while EUR/CAD slipped 0.33% to 1.56. Equities were softer, with the S&P/TSX down 0.17% to 36,204.86 as rate-sensitive sectors — housing and utilities — absorbed the hike. Energy was the dominant cross-asset story: Brent collapsed 5.25% to $109.27 and WTI fell 2.62% to $100.09, even as natural gas jumped 4.51% to $2.94.
Gold eased 0.16% to $4,045.10 and Bitcoin dropped 1.76% to 79,836.53.
The Day Ahead
The Canadian calendar is light Thursday, with no tier-one domestic releases scheduled; attention shifts to Friday's GDP Month-over-Month print at 08:30 ET, where consensus looks for 0.2% following a flat 0.0% prior. The preliminary GDP estimate is also due at the same time, giving markets an early read on momentum into Q4. With the BoC's hike now in the tape, traders will parse the GDP detail for evidence on whether the economy can absorb further tightening without stalling.
Government of Canada bond markets will also take their cue from the prior day's yield backup and any follow-through in CAD crosses. Absent domestic catalysts, TSX direction will hinge on energy pricing and the overnight tone from U.S. futures.
Other Economic Notes
The hike lands against a backdrop of sticky inflation — CPI running at 3.09% year-over-year as of September — and a housing market already under strain, with Bloomberg noting the rate rise "kicks Canada's housing market when it's down." Regional dynamics are diverging: Alberta's oil-linked economy is framed as a balancing act, while Ontario Premier Doug Ford publicly criticized the hike, underscoring the political sensitivity of tightening into a cost-of-living squeeze. ↓ p.2