Canada Macro Daily(Beta Mode)
Inflation Steady, Macklem to Exit
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 35,722.10 | -1.06% |
| USD/CAD | 1.43 | +0.23% |
| EUR/CAD | 1.57 | -0.09% |
| WTI Crude | 86.25 | +0.62% |
| Natural Gas | 3.13 | +0.22% |
| Gold | 3,870.90 | +0.46% |
| Brent Crude | 92.87 | +0.47% |
| Bitcoin | 64,799.85 | -0.09% |
| Canada 2Y Govt Yield | 3.37% | +4 bp |
| Canada 10Y Govt Yield | 3.85% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 3.10 | 3.20 | 3.10 |
| Core Inflation Rate Year-over-Year | 2.20 | - | 2 |
| Inflation Rate Month-over-Month | 0.10 | 0.40 | 0.20 |
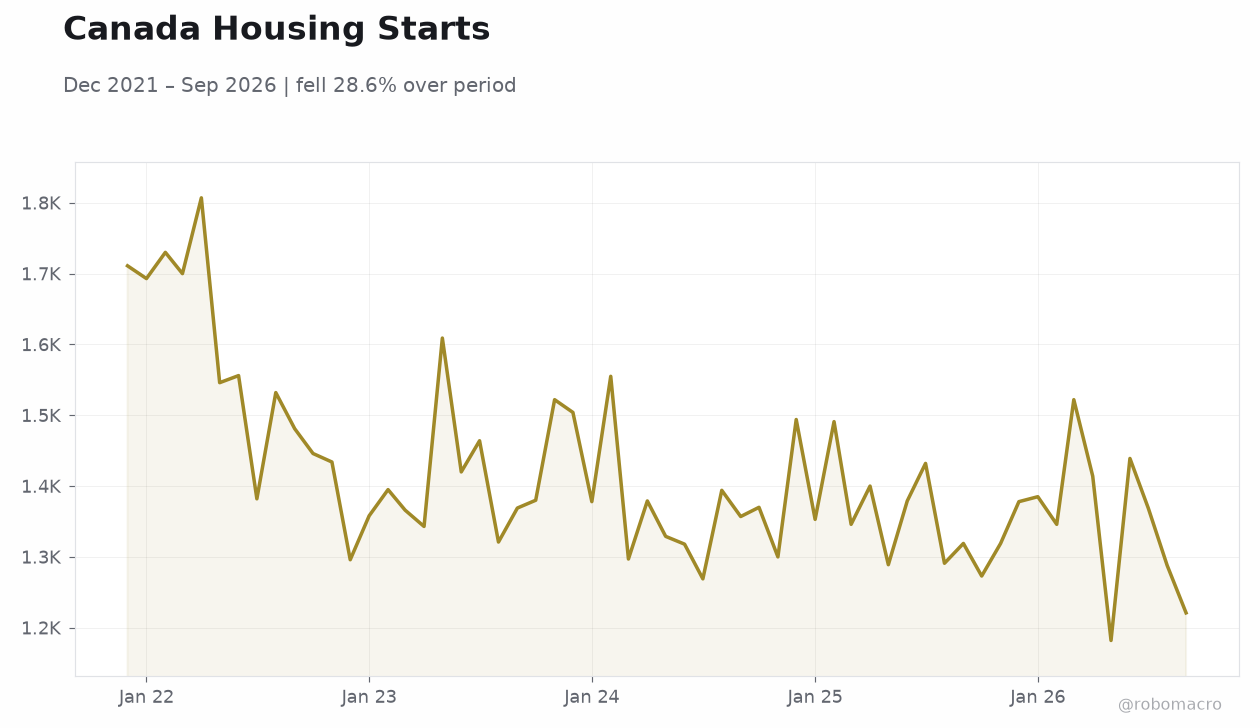 Canada Housing Starts | Type: macro_line | Housing Starts (000s): 1221 (2026-09-01) | Range: 1182–1807 | Trend(6pt): 1711,1395,1379,1379,1288,1221
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Housing Starts Level | 250,000 | 238,000 | 08:15 |
| Wednesday (2026-11-18) | |||
| New Housing Price Index Month-over-Month | -0.20 | 0.10 | 08:30 |
| Friday (2026-11-20) | |||
| Retail Sales Excluding Autos Month-over-Month | 1.20 | 0.70 | 08:30 |
| Retail Sales Month-over-Month Final | 1.20 | 0.70 | 08:30 |
| Retail Sales Month-over-Month Prel | - | - | 08:30 |
- October CPI held at 3.1% y/y as gasoline prices offset easing elsewhere; core slowed to 2.0% y/y
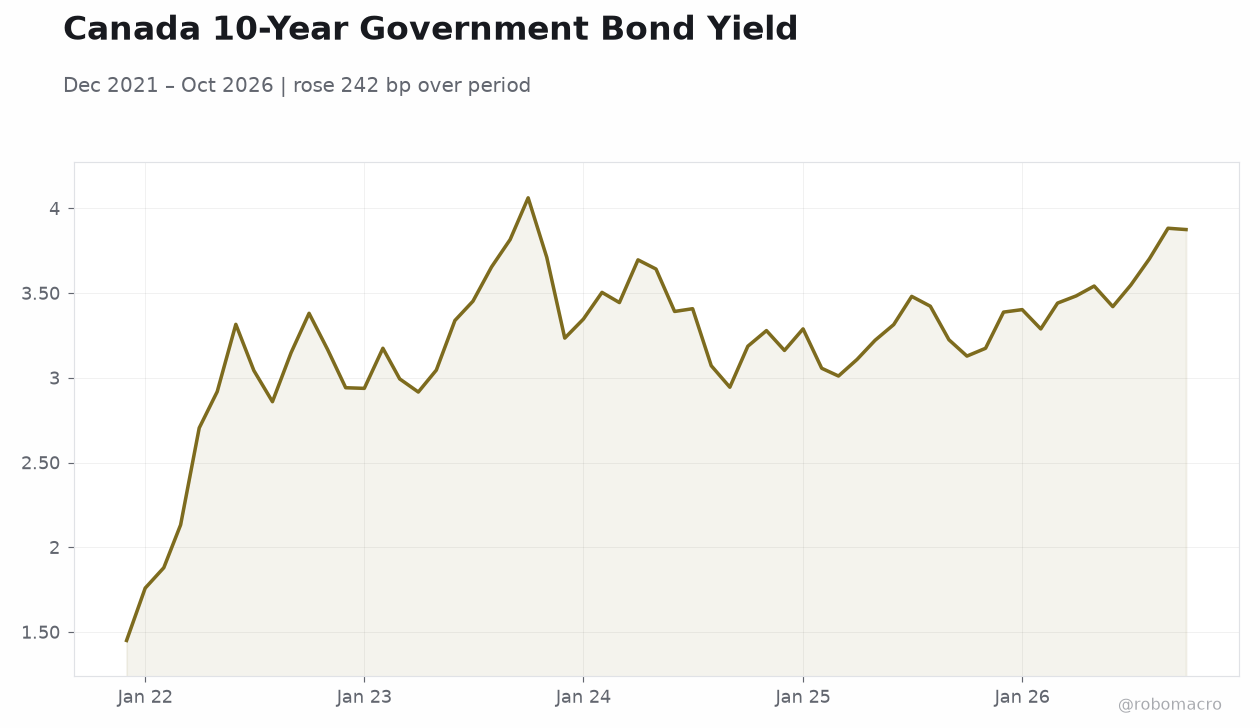
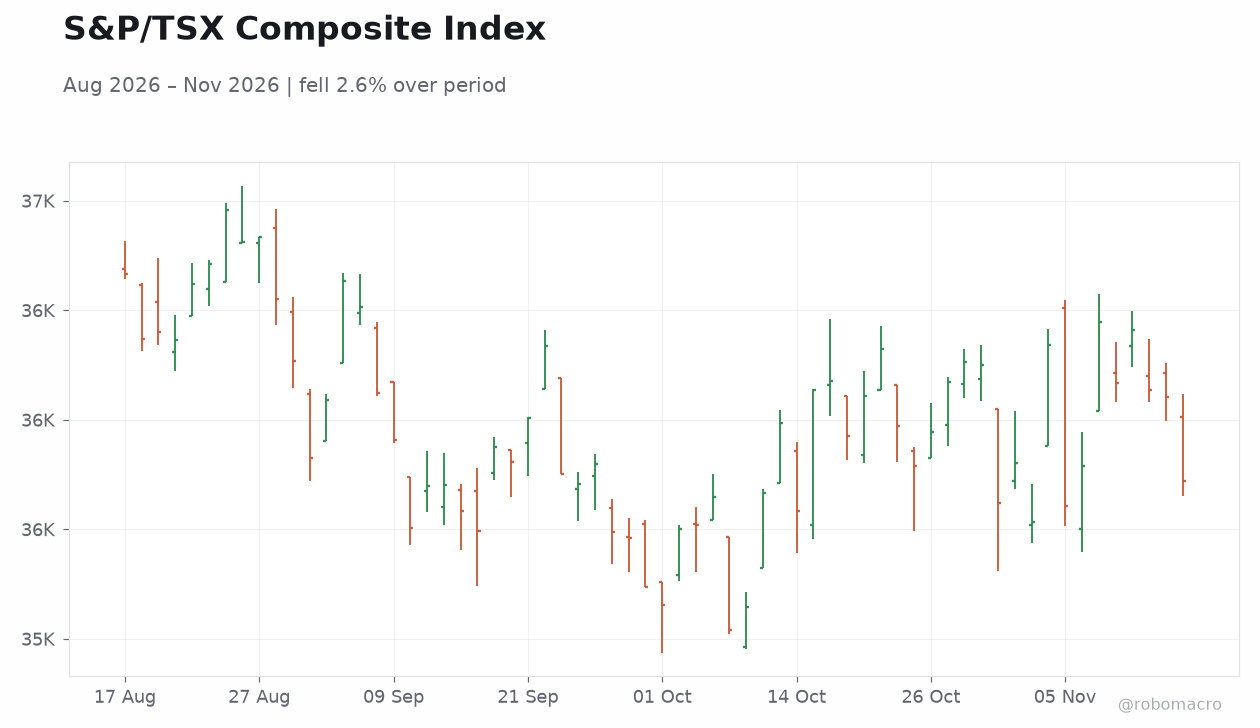
- GoC curve steepened: 10-year yield +7 bp to 3.85%, 2-year +4 bp to 3.37%; TSX fell 1.06%
- USD/CAD rose to 1.43 (+0.23%) as the loonie hit its lowest since 2025; Macklem will not seek a second term
Yesterday's Recap
Canada's October CPI printed at 3.1% y/y, matching the prior month and coming in one tick below consensus of 3.2%, as surging gasoline prices offset easing in other categories. Core inflation slowed to 2.0% y/y, and the month-over-month headline rose 0.2%, below the 0.4% consensus. Markets read the softer core and in-line headline as reducing pressure on the Bank of Canada to move at its December 9 decision.
The GoC curve steepened, with the 10-year yield rising 7 bp to 3.85% and the 2-year up 4 bp to 3.37%. The S&P/TSX fell 1.06% to 35,722.10, while USD/CAD rose 0.23% to 1.43 as the loonie touched its lowest level since 2025 on the inflation print and Fed rate-hike expectations. WTI crude gained 0.62% to $86.25 and gold rose 0.46% to $3,870.90.
The Day Ahead
Housing Starts for November are due at 08:15 ET, with consensus at 238,000 versus a previous 250,000, a modest expected cooling in residential construction activity. On Wednesday, November 18, New Housing Price Index m/m for November is scheduled for 08:30 ET, with consensus at 0.1% following a prior -0.2%, a signal on whether new-home pricing is stabilizing. Also Wednesday, Deputy Governor Toni Gravelle speaks before the Edmonton Chamber of Commerce, a venue to watch for any refinement of the Bank's reaction function after the flat inflation data.
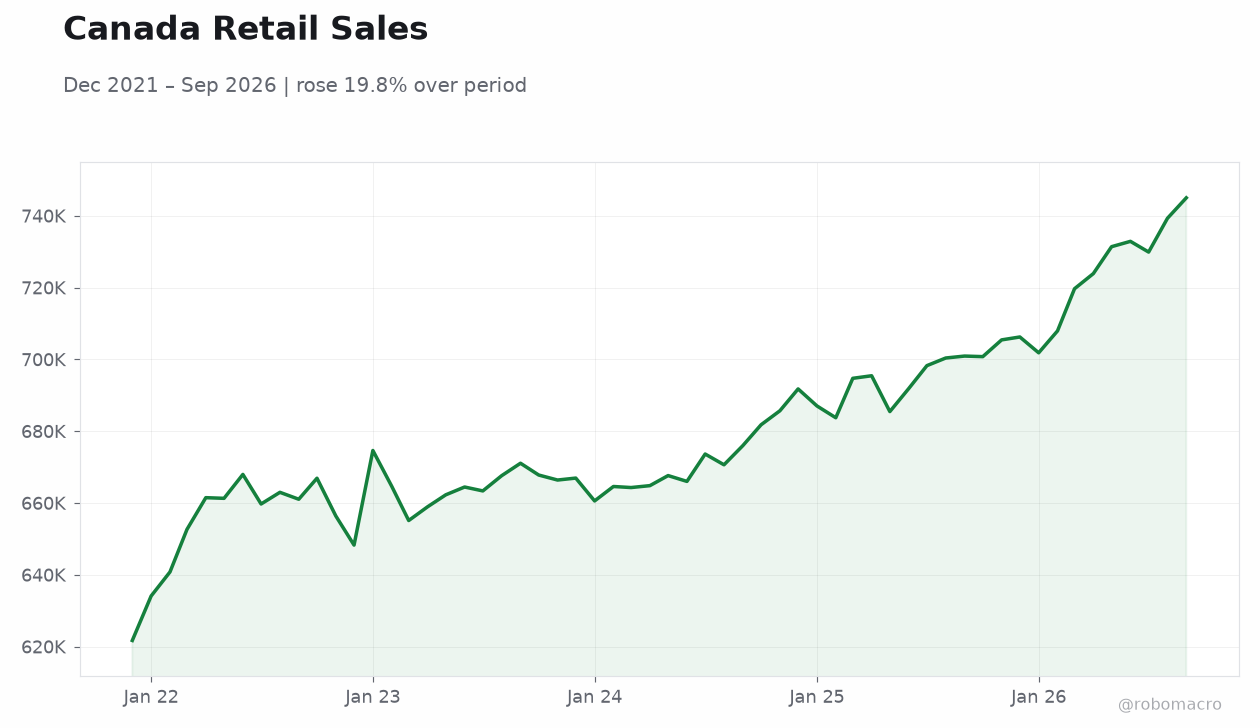
Friday brings Retail Sales for November at 08:30 ET, with both the excluding-autos and headline m/m measures expected at 0.7% versus a prior 1.2%, plus the preliminary estimate for the following month. Retail momentum will be a key input for the December 9 policy decision.
Other Economic Notes
The October CPI composition matters more than the headline: energy-driven pressure masked disinflation in core goods and services, with cell phone plans cited as an easing factor. Core at 2.0% y/y sits at the midpoint of the Bank's target range, giving the Governing Council room to argue that underlying inflation is contained even as headline runs above target. Housing activity is the soft spot to monitor, with starts expected to pull back and new home prices only tentatively stabilizing.
↓ p.2