Canada Macro Daily(Beta Mode)
Inflation Cools, Retail Sales Eyed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P/TSX | 34,028.70 | -1.59% |
| USD/CAD | 1.43 | -0.05% |
| EUR/CAD | 1.57 | -0.13% |
| WTI Crude | 82.58 | -0.76% |
| Natural Gas | 3.57 | +9.12% |
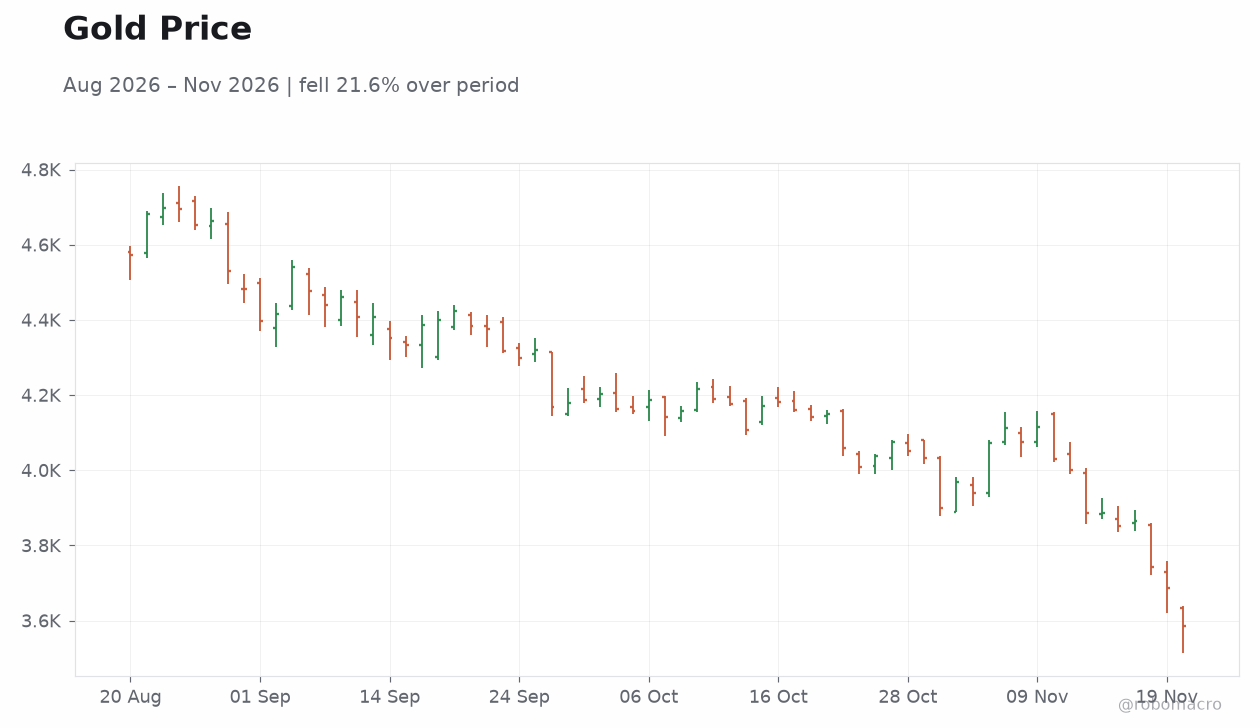
| Gold | 3,586.50 | -2.69% |
| Brent Crude | 89.31 | -2.90% |
| Bitcoin | 61,780.44 | -0.20% |
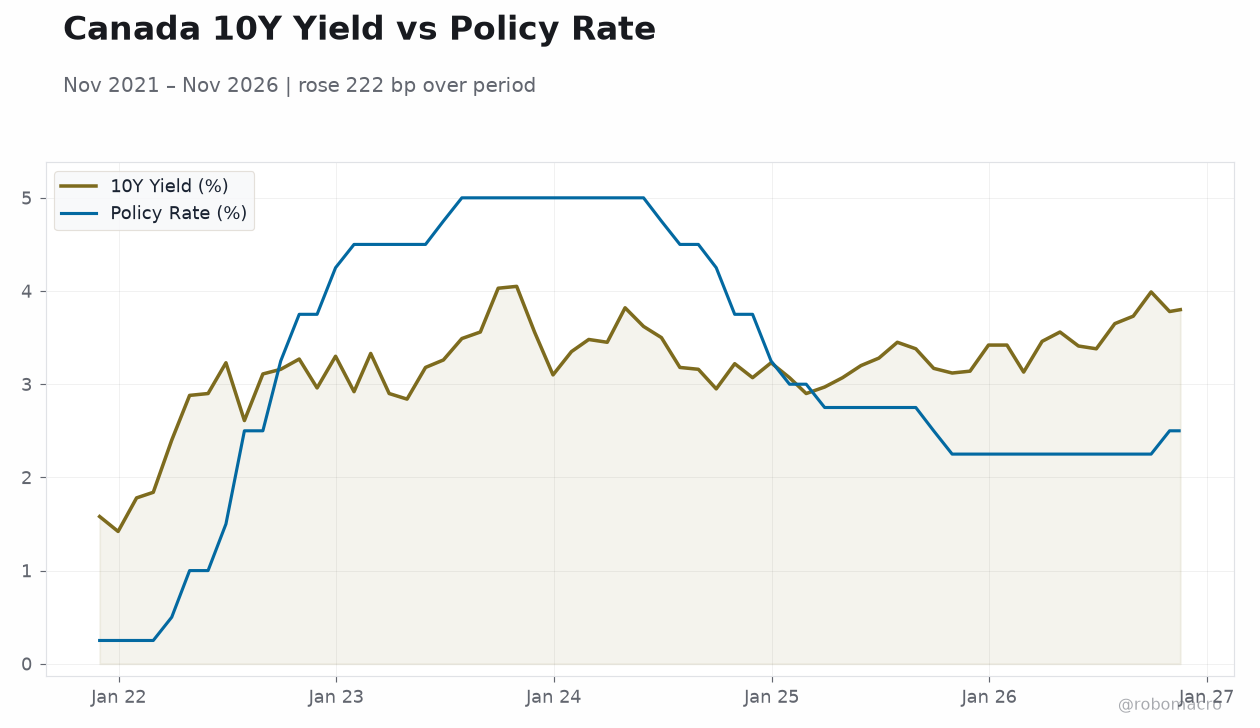
| Canada 2Y Govt Yield | 3.30% | 0 bp |
| Canada 10Y Govt Yield | 3.80% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 3.10 | 3.20 | 3.10 |
| Core Inflation Rate Year-over-Year | 2.20 | - | 2 |
| Inflation Rate Month-over-Month | 0.10 | 0.40 | 0.20 |
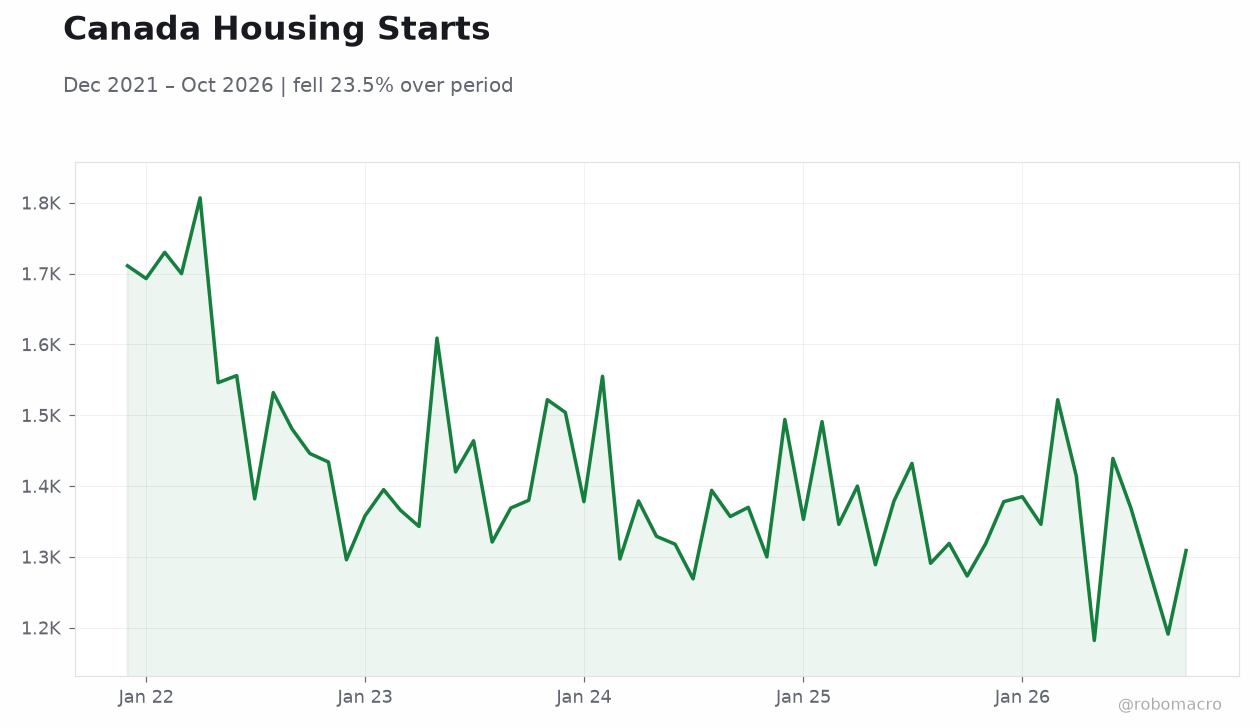
| Housing Starts Level | 250,000 | 238,000 | 244,600 |
| New Housing Price Index Month-over-Month | -0.20 | 0.10 | -0.20 |
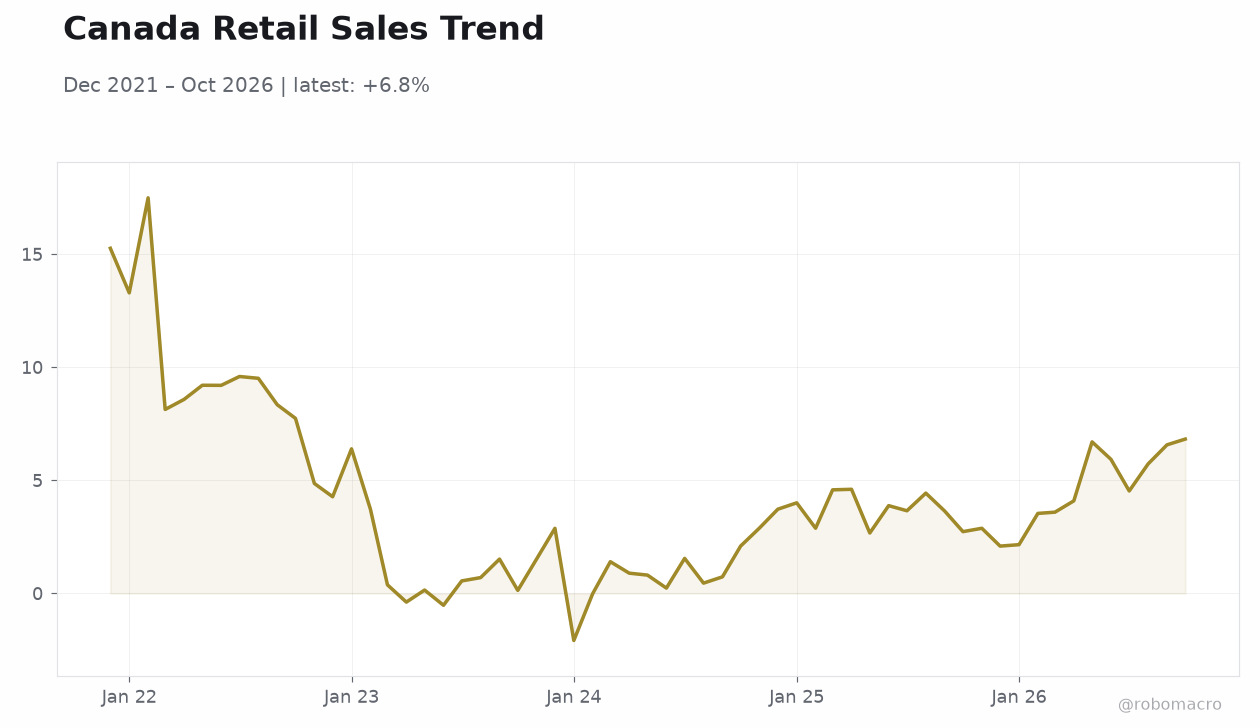 Canada Retail Sales Trend | Type: macro_line | Retail Sales: 6.823 (2026-10-01) | Range: -2.082–17.49 | Trend(6pt): 15.26,3.726,0.8947,3.88,5.725,6.823
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Retail Sales Excluding Autos Month-over-Month | 1.20 | 0.70 | 08:30 |
| Retail Sales Month-over-Month Final | 1.20 | 0.70 | 08:30 |
| Retail Sales Month-over-Month Prel | - | - | 08:30 |
- October CPI held at 3.1% y/y, with core at 2.0% and m/m at 0.2%, undershooting the 0.4% consensus
- TSX fell 1.59% to 34,028.70 as gold slid 2.69% and Brent dropped 2.90%; CAD held near 1.43
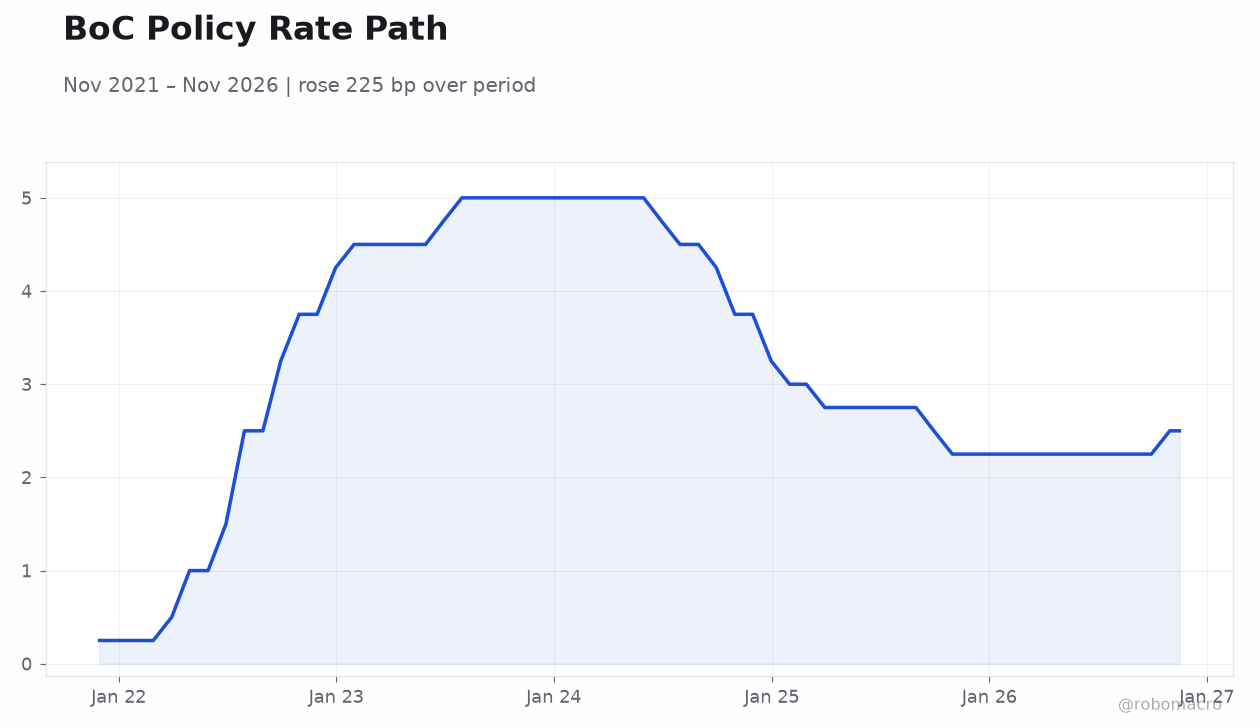
- November retail sales print at 08:30 ET, consensus +0.7% m/m, with Macklem speaking Nov 24 ahead of the Dec 9 decision
Yesterday's Recap
October CPI printed at 3.1% y/y, matching the prior reading and landing a touch below the 3.2% consensus, while core inflation slowed to 2.0% y/y and the month-over-month figure came in at 0.2% versus a 0.4% consensus — a softer-than-expected outcome that reinforces disinflation momentum. Housing starts for the reference period came in at 244,600, above the 238,000 consensus estimate but below the prior 250,000 reading. The New Housing Price Index for the reference month held at -0.2% m/m, missing the +0.1% consensus and signaling continued softness in new home pricing.
Markets delivered a risk-off session: the S&P/TSX dropped 1.59% to 34,028.70, with financials under pressure as RBC fell 3.107% and National Bank dropped 2.161% on November 18. Commodities were mixed — WTI eased 0.76% to $82.58, Brent fell 2.90% to $89.31, gold tumbled 2.69% to $3,586.50, while natural gas surged 9.12% to $3.57. USD/CAD held near 1.43 (-0.05%), with the loonie still near 19-month lows, and Government of Canada yields were little changed — the 2-year at 3.30% (flat) and the 10-year at 3.80% (-1 bp).
The Day Ahead
The focus turns to Canadian retail sales at 08:30 ET, with month-over-month final and preliminary prints alongside the ex-autos series, all carrying a +0.7% consensus versus a prior +1.2%. The ex-autos reading will be scrutinized for underlying consumer resilience given the softer inflation backdrop. No other tier-one Canadian releases are scheduled, leaving the retail data as the sole domestic catalyst.
South of the border, attention stays on Fed communication and oil price volatility tied to Strait of Hormuz tanker attacks. With the December 9 BoC decision approaching, today's consumer spending data will feed directly into the Governing Council's growth assessment.
Other Economic Notes
The October inflation report underscores a bifurcated picture — headline stuck at 3.1% while core decelerated to 2.0%, suggesting underlying price pressures are easing even as energy and shelter components keep the headline elevated. Housing activity remains soft, with starts at 244,600 and new home prices contracting 0.2% m/m, pointing to a persistent drag from the residential construction channel. Consumer spending is the next test, with retail sales consensus at +0.7% m/m following a strong +1.2% prior.
↓ p.2