Emerging Europe Macro Daily(Beta Mode)
Poland Signals Hikes as Yields Slide
Market Snapshot
| Asset | Level | Change |
|---|---|---|
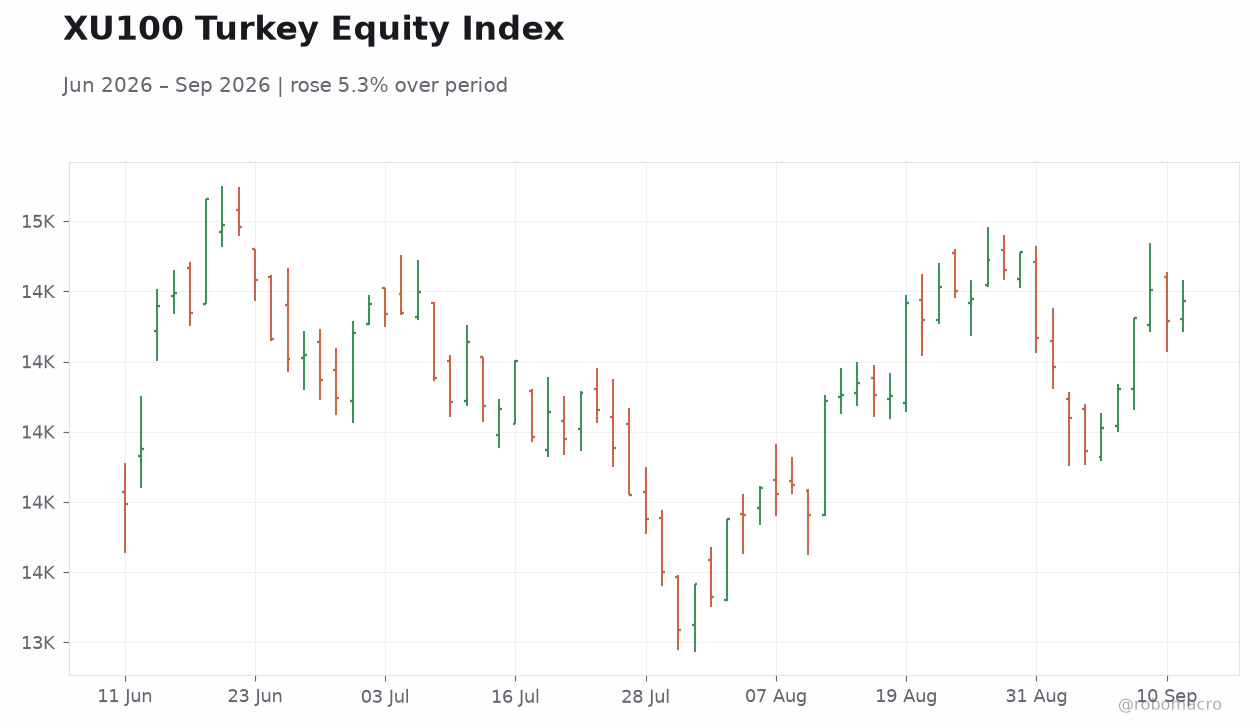
| BIST 100 | 14,467.30 | +0.51% |
| iShares Poland | 45.56 | +0.91% |
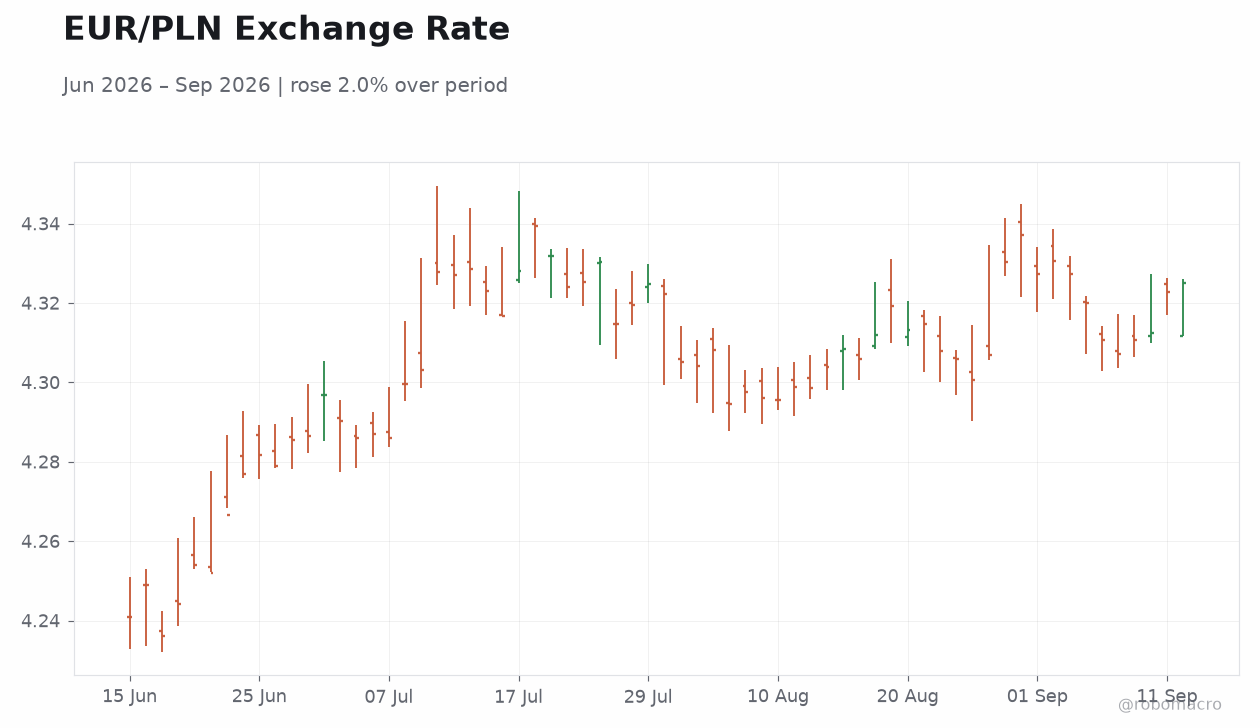
| EUR/PLN | 4.32 | +0.05% |
| EUR/HUF | 364.14 | -0.19% |
| EUR/CZK | 24.25 | +0.07% |
| USD/TRY | 48.61 | +0.05% |
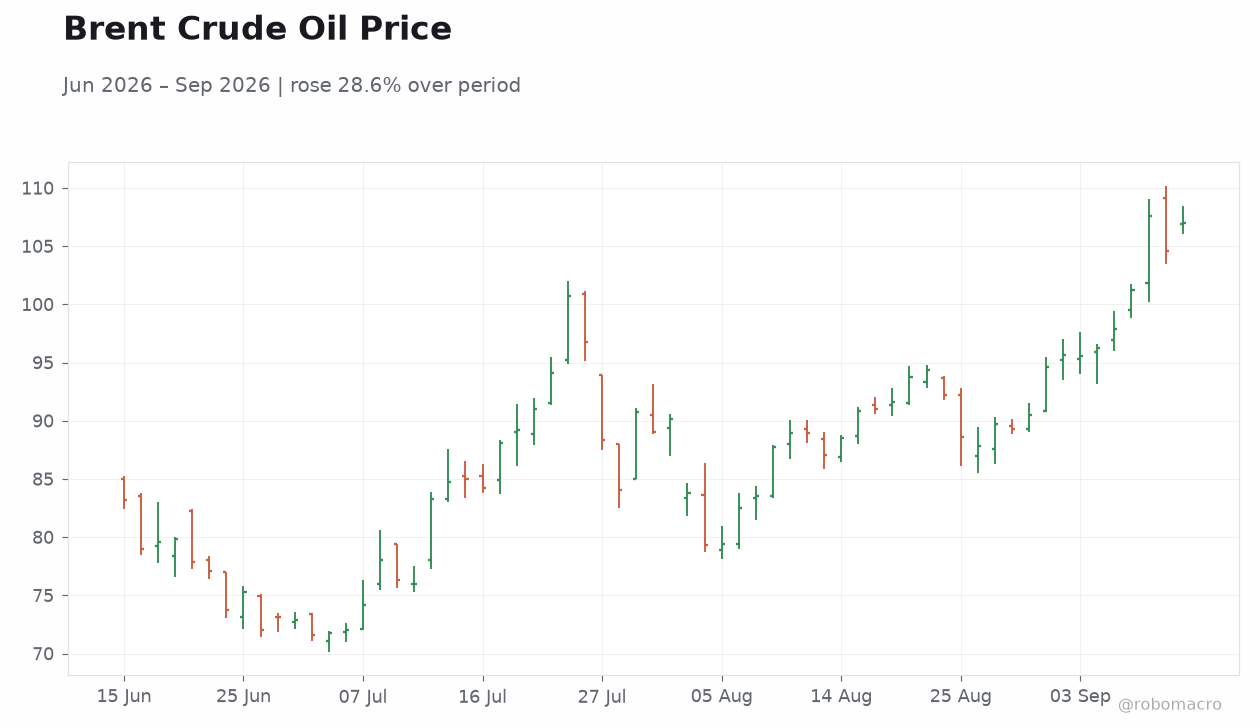
| Brent Crude | 107.03 | +2.31% |
| Gold | 4,376.60 | +0.24% |
| Bitcoin | 77,728.70 | +0.59% |
| Poland 10Y Govt Yield | 5.51% | -4.01% |
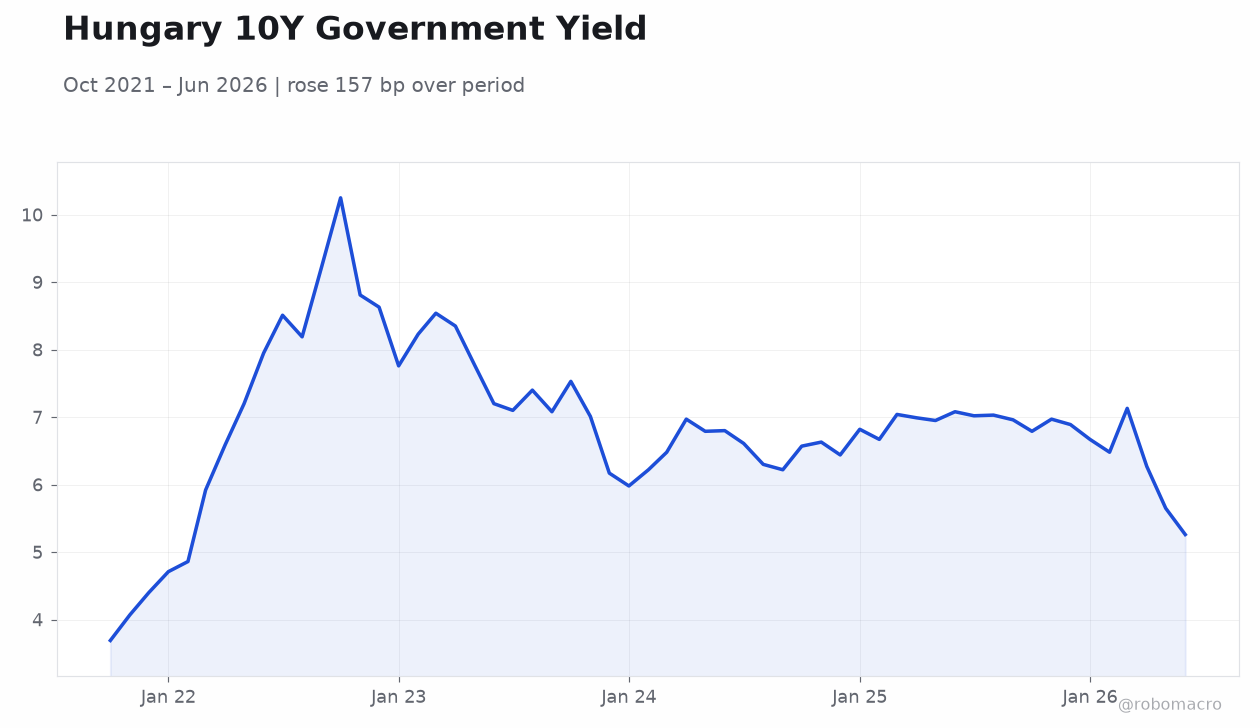
| Hungary 10Y Govt Yield | 5.26% | -6.90% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
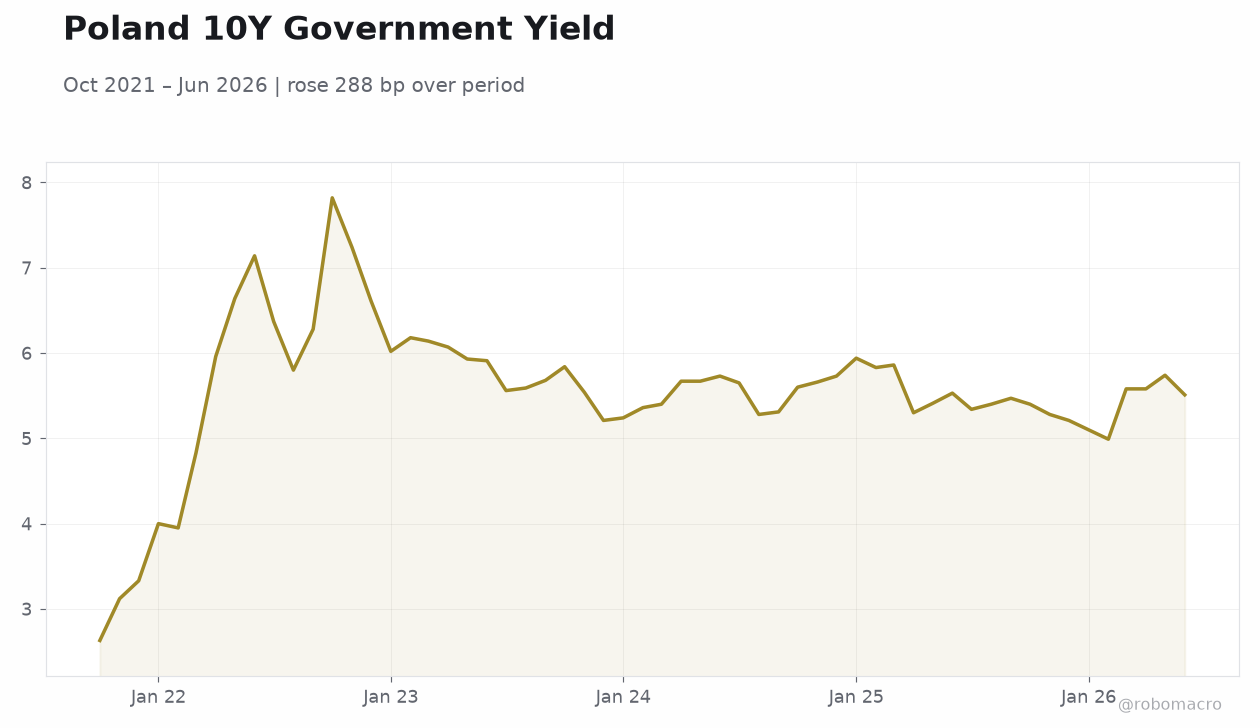 Poland 10Y Government Yield | Type: macro_line | Yield %: 5.51 (2026-06-01) | Range: 2.63–7.82 | Trend(5pt): 2.63,6.61,5.36,5.3,5.51
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Poland signals possible NBP rate hikes if inflation stays above 4%, while regional equities and bonds rally on thin data.
- BIST 100 rises 0.51% and iShares Poland gains 0.91%; Poland and Hungary 10-year yields fall 4.01% and 6.90%.
- Russian drone strike near Poland-Ukraine border raises geopolitical risk without immediate market disruption.
Yesterday's Recap
No macroeconomic releases occurred across Poland, Czech Republic, Hungary, Romania or Turkey on September 13. Polish authorities indicated the NBP could raise rates if inflation remains above 4%, providing the sole policy signal. BIST 100 advanced 0.51% to 14,467.30 while iShares Poland climbed 0.91% to 45.56.
Poland’s 10-year yield dropped 4.01% to 5.51% and Hungary’s fell 6.90% to 5.26%. EUR/PLN edged 0.05% higher to 4.32, EUR/HUF declined 0.19% to 364.14 and EUR/CZK rose 0.07% to 24.25. USD/TRY ticked up 0.05% to 48.61 amid Brent crude’s 2.31% surge to 107.03.
A Russian drone strike on a train near the Ukraine-Poland border drew condemnation from Warsaw and Kyiv but produced no immediate market reaction. The incident occurred shortly after foreign officials departed the area, underscoring spillovers into NATO territory without disrupting regional asset prices.
The Day Ahead
The calendar for September 14-15 shows zero scheduled releases or central-bank meetings in the five countries. Markets will monitor any follow-up comments from Polish officials on the inflation threshold for rate action. Regional FX and bond trading may stay light absent fresh data.
Geopolitical developments along the Poland-Ukraine border remain a potential volatility source. Energy-price moves will continue to influence Hungary and Turkey inflation outlooks given their import dependence. Brent above 107 highlights shared exposure for all five economies, while stable EUR crosses support limited near-term pressure on CEE currencies.
Other Economic Notes
Sharp declines in Polish and Hungarian government yields reflect reduced term premia amid stable EUR crosses and supportive global risk sentiment. Poland’s largest CEE economy status amplifies any NBP signal across the region, while Hungary’s euro-convergence path supports further yield compression. Turkey’s structurally higher inflation and distinct policy framework keep USD/TRY moves decoupled from CEE peers.
Energy-import vulnerability remains a shared exposure for all five economies, with Brent above 107 underscoring the risk. No data were supplied for WIG20, PX, BUX, Turkey 10-year yields or CDS spreads, leaving the observed moves in Polish and Hungarian bonds as the clearest indicators of improved sentiment.