Emerging Europe Macro Daily(Beta Mode)
BIST Drops as CEE Yields Slide on Quiet Day
Market Snapshot
| Asset | Level | Change |
|---|---|---|
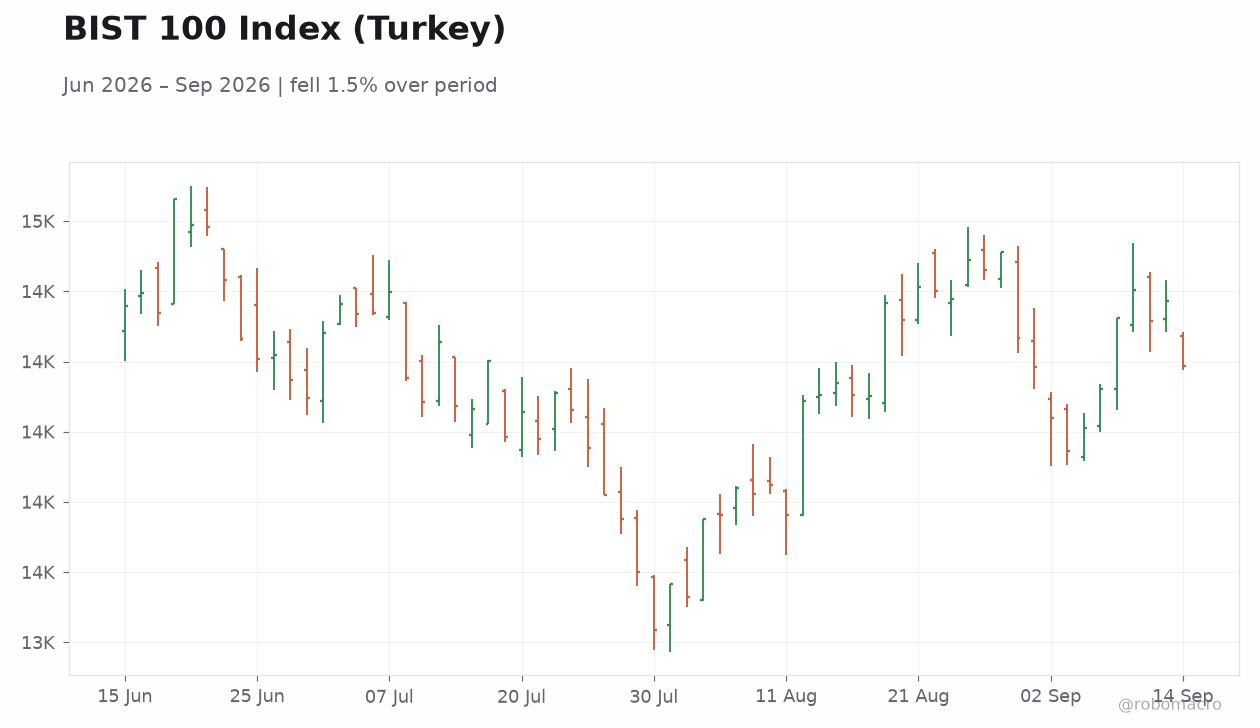
| BIST 100 | 14,235.80 | -1.60% |
| iShares Poland | 45.14 | -0.92% |
| EUR/PLN | 4.32 | -0.08% |
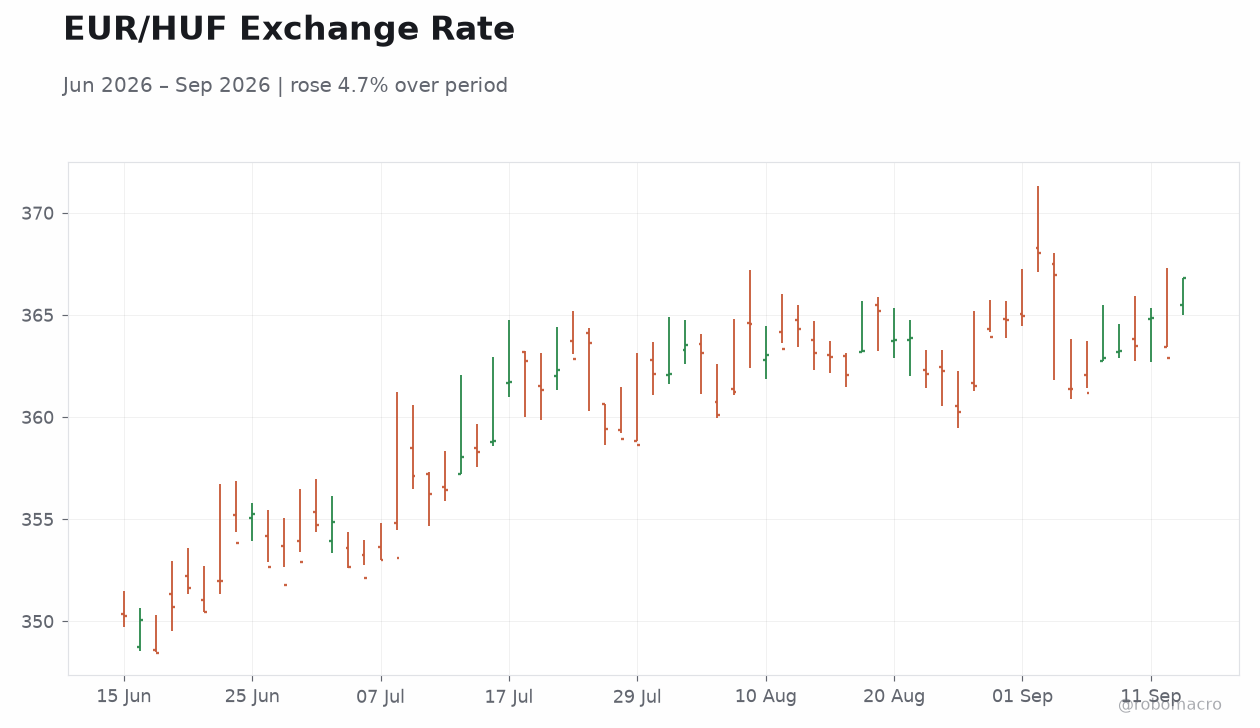
| EUR/HUF | 366.83 | +1.09% |
| EUR/CZK | 24.29 | +0.30% |
| USD/TRY | 48.64 | +0.06% |
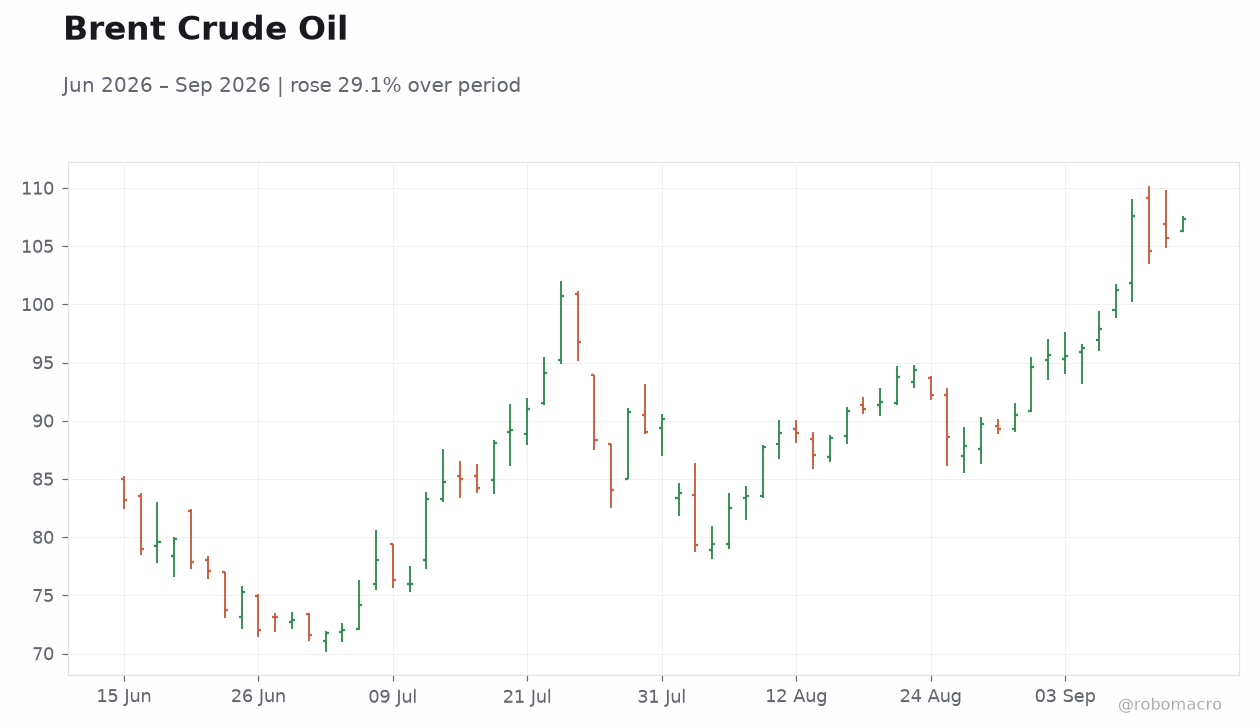
| Brent Crude | 107.36 | +1.59% |
| Gold | 4,331.50 | -0.47% |
| Bitcoin | 77,373.94 | +0.70% |
| Poland 10Y Govt Yield | - | - |
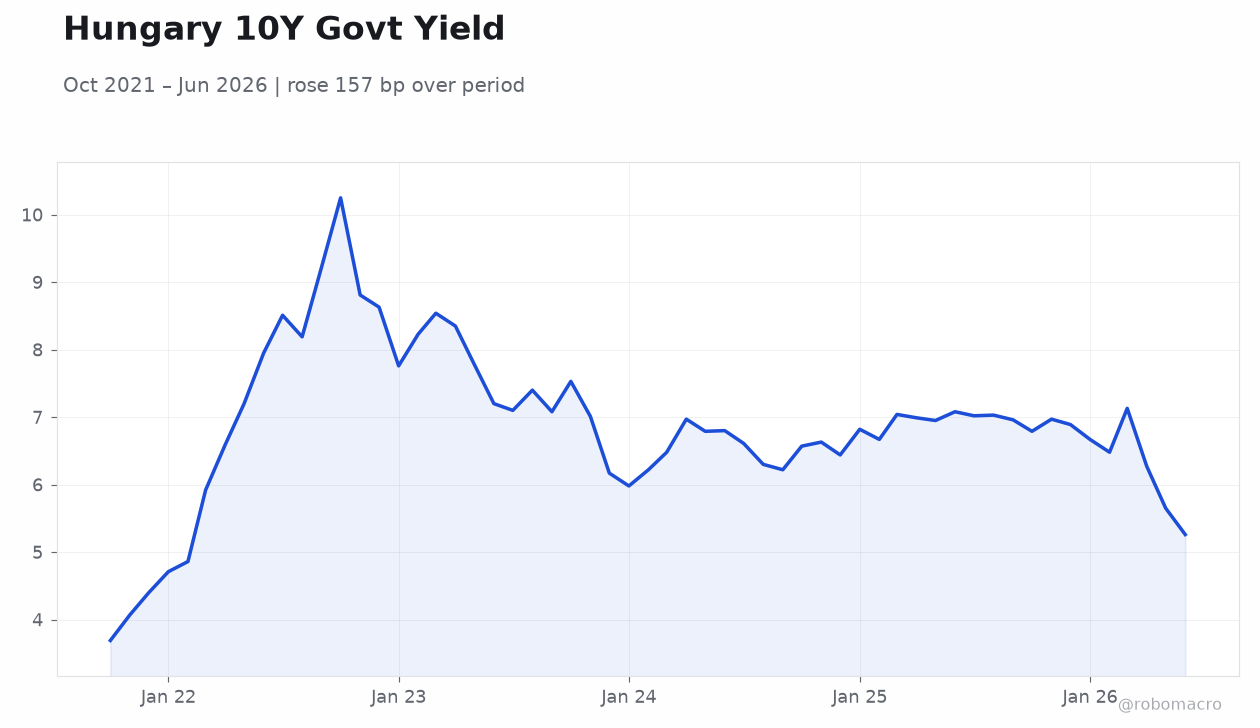
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
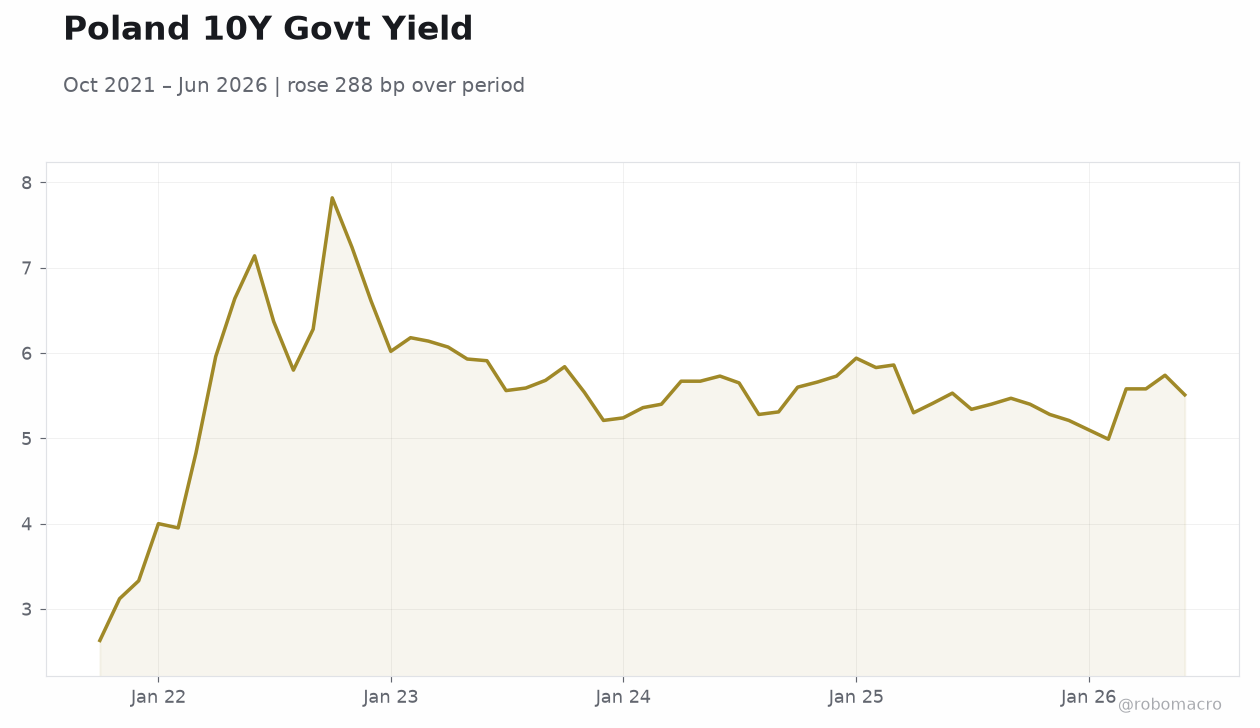 Poland 10Y Govt Yield | Type: macro_line | Yield %: 5.51 (2026-06-01) | Range: 2.63–7.82 | Trend(5pt): 2.63,6.61,5.36,5.3,5.51
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Business Confidence | 102.80 | - | 03:00 |
| Consumer Confidence Index | 90.80 | - | 03:00 |
- BIST 100 dropped 1.60% while Polish equities eased 0.92% amid thin regional flows
- Hungarian forint weakened 1.09% against the euro on higher oil prices and geopolitics
- No macro releases occurred across Poland, Czech Republic, Hungary, Romania or Turkey yesterday
Yesterday's Recap
Equity markets in Emerging Europe closed lower on 14 September. The BIST 100 fell 1.60% to 14,235.80 while iShares Poland declined 0.92% to 45.14. Currency moves were mixed: EUR/PLN eased 0.08% to 4.32, EUR/HUF rose 1.09% to 366.83 and EUR/CZK gained 0.30% to 24.29.
USD/TRY edged 0.06% higher to 48.64. Brent crude advanced 1.59% to 107.36, supporting forint pressure via higher energy import costs. Sovereign yields declined sharply, with Poland’s 10-year yield were unavailable from the daily warehouse and Hungary’s 10-year yield were unavailable from the daily warehouse.
A Russian drone strike near the Ukraine-Poland border occurred shortly after European officials departed the area, though no casualties were reported and no immediate market reaction followed. No economic data prints were released for any of the five countries.
The Day Ahead
Turkey will publish Business Confidence on 21 September and the Consumer Confidence Index on 22 September, both carrying medium impact. No sovereign bond auctions or central-bank meetings are scheduled for Poland, Czech Republic, Hungary or Romania in the immediate window. Markets will continue to track external drivers including ECB policy signals and Brent crude above $107.
Regional FX volatility may persist given the forint’s sensitivity to oil and dollar strength. No EU fund disbursement decisions or convergence updates are expected this week for the four EU members.
Other Economic Notes
Poland’s family-office sector continues to expand as domestic wealth rises, though employment schemes for Ukrainian workers remain fragmented and largely informal. Energy import dependence on Russian gas continues to expose all five economies to price spikes, with Brent at $107.36 amplifying current-account pressure in Hungary and Turkey. EU convergence criteria for euro adoption remain unchanged for Czech Republic and Romania, with no fresh inflation prints to assess progress against the 3.30% Eurozone CPI benchmark.
Broader capital-flow dynamics stay sensitive to the ECB Deposit Rate at 2.25%.
Global Macro News
The dollar held steady ahead of Fed and BOJ meetings while the yen traded near a seven-month high. ↓ p.2