Emerging Europe Macro Daily(Beta Mode)
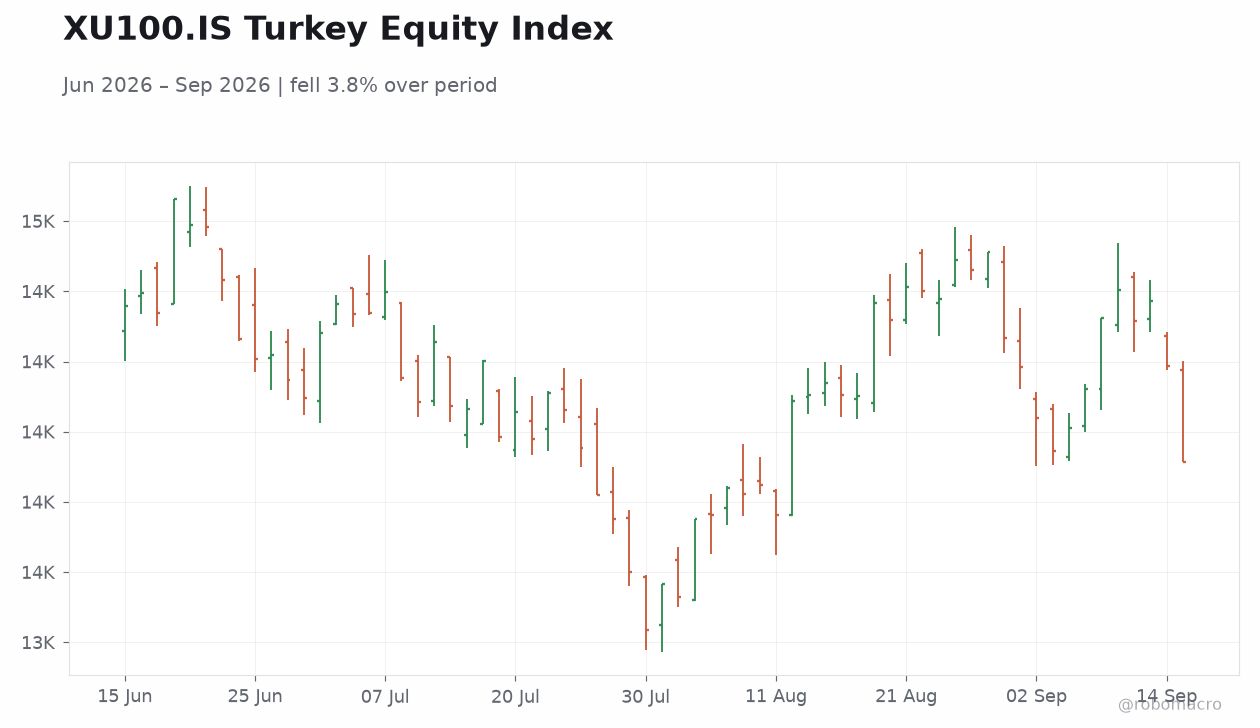
BIST 100 Slides 2.4% as Regional Equities Ease
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 13,892.30 | -2.41% |
| iShares Poland | 44.86 | -0.62% |
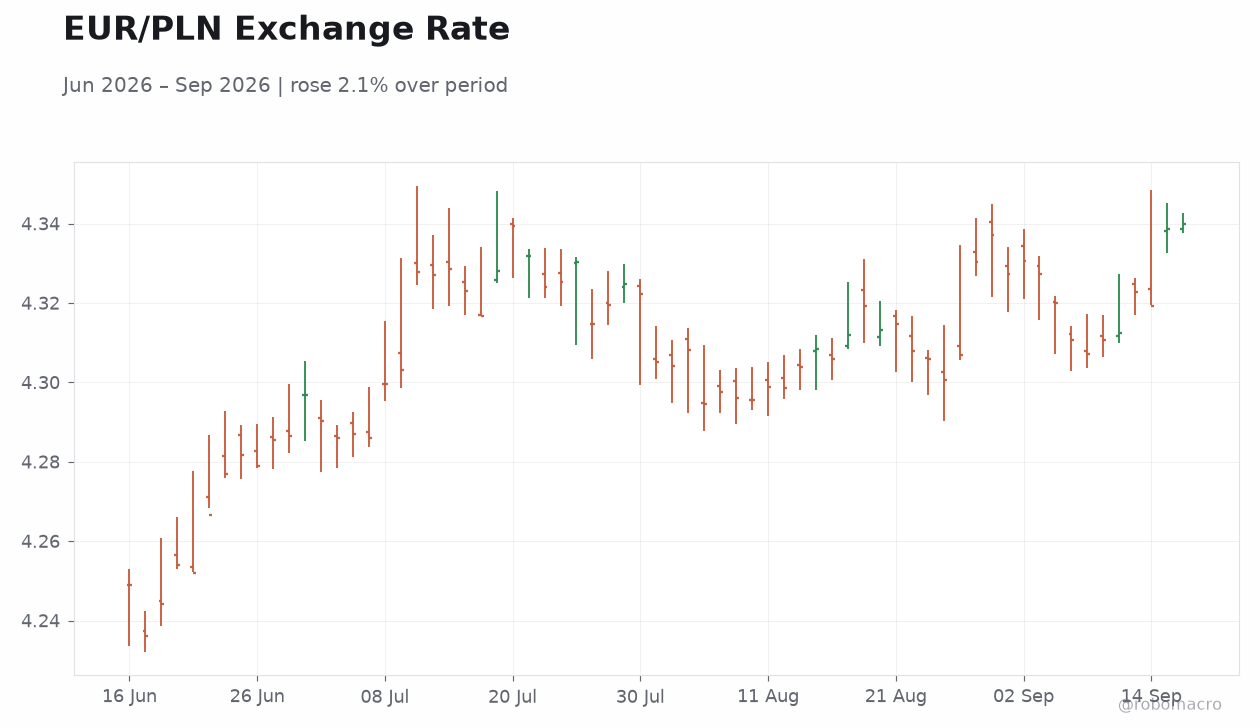
| EUR/PLN | 4.34 | +0.04% |
| EUR/HUF | 364.77 | +0.10% |
| EUR/CZK | 24.25 | -0.04% |
| USD/TRY | 48.62 | +0.03% |
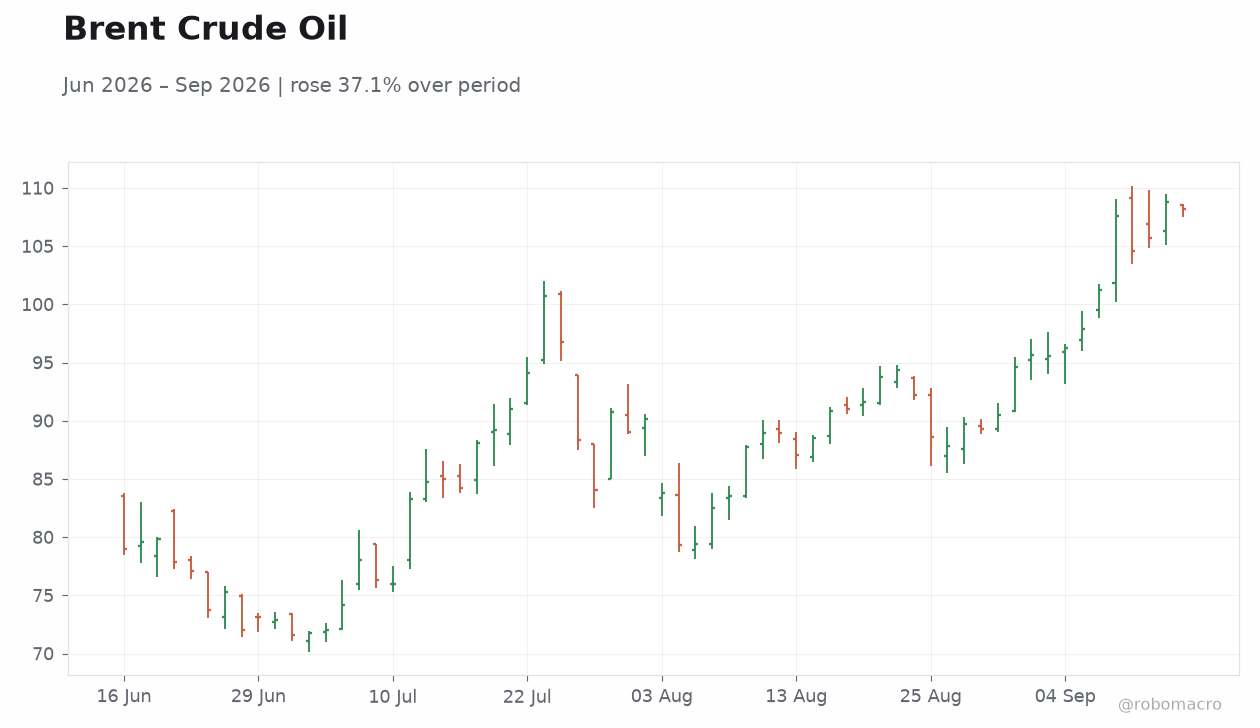
| Brent Crude | 108.07 | -0.63% |
| Gold | 4,367.10 | +0.79% |
| Bitcoin | 75,879.98 | -2.92% |
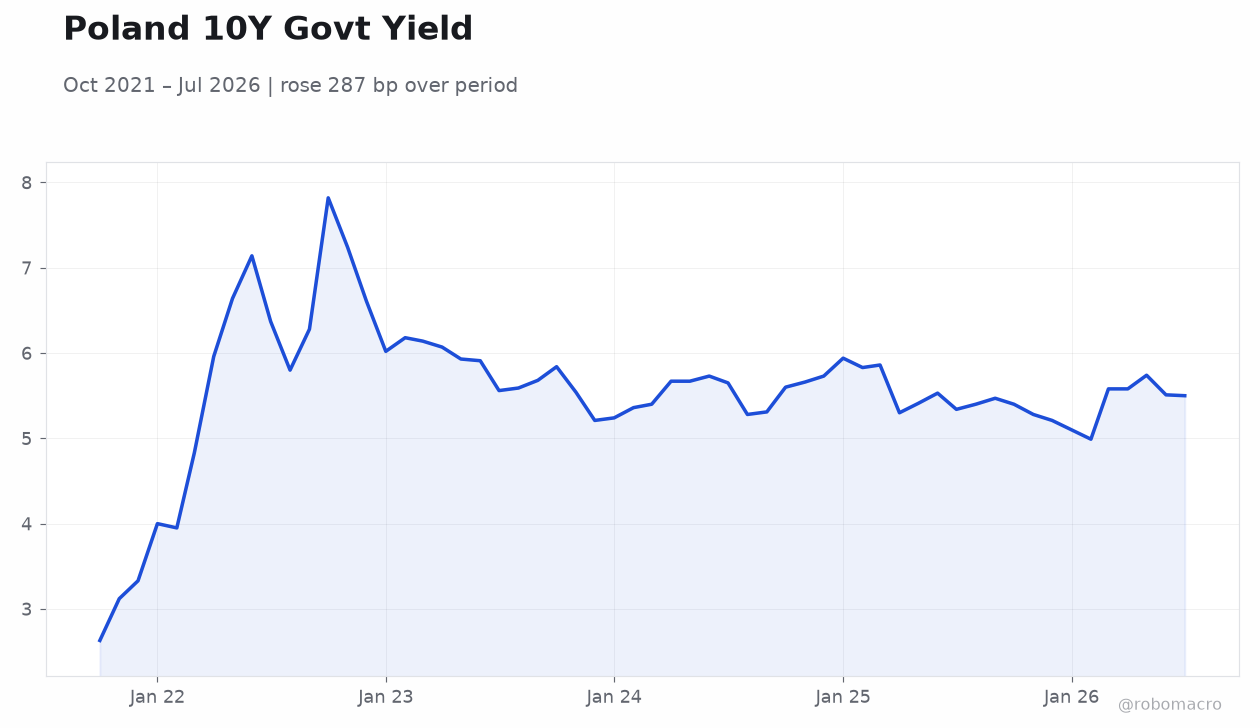
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
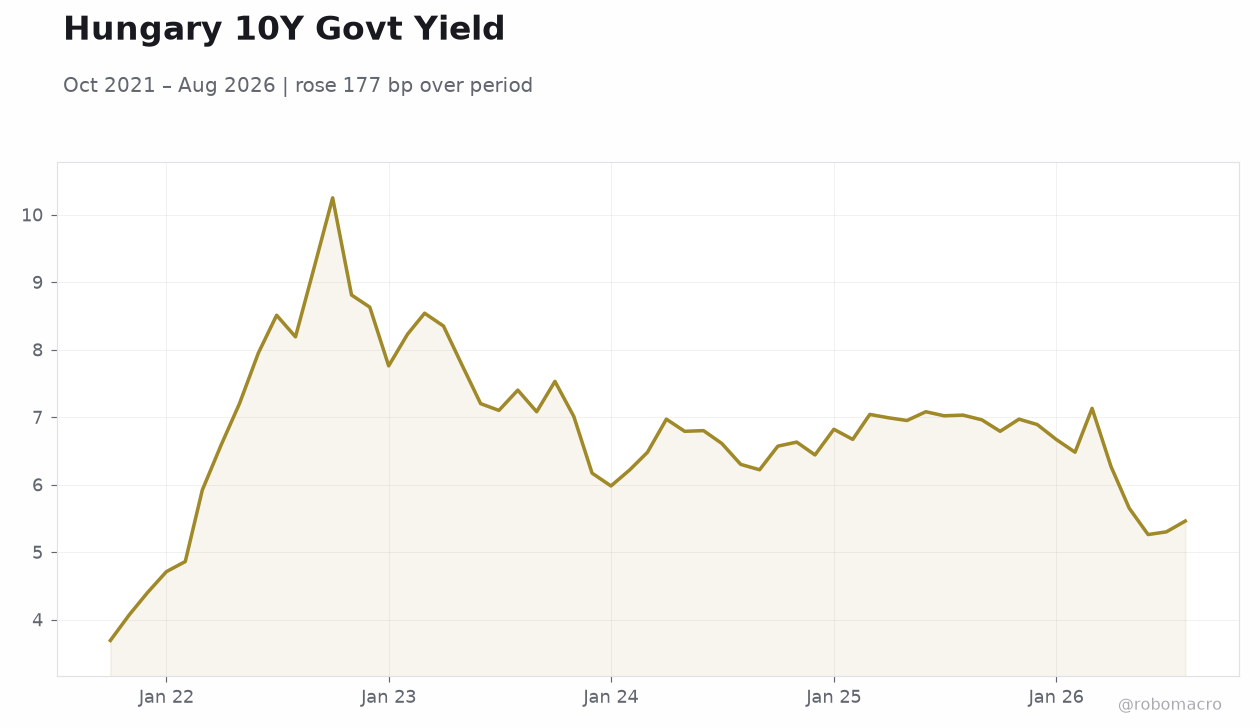 Hungary 10Y Govt Yield | Type: macro_line | Yield %: 5.46 (2026-08-01) | Range: 3.69–10.25 | Trend(6pt): 3.69,8.63,6.22,6.99,5.26,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Business Confidence | 102.80 | - | 03:00 |
| Consumer Confidence Index | 90.80 | - | 03:00 |
| Unemployment Rate | 5.80 | - | 03:30 |
- BIST 100 fell 2.41% while iShares Poland declined 0.62% on limited news flow.
- EUR/PLN edged 0.04% higher to 4.34 with other CEE FX pairs little changed.
- No macro releases occurred across Poland, Czech Republic, Hungary, Romania or Turkey.
Yesterday's Recap
Equity markets across Emerging Europe closed lower on 15 September. The BIST 100 dropped 2.41% to 13,892.30 while the iShares Poland ETF fell 0.62% to 44.86. Foreign-exchange moves remained contained, with EUR/PLN rising 0.04% to 4.34, EUR/HUF advancing 0.10% to 364.77 and EUR/CZK easing 0.04% to 24.25.
USD/TRY ticked 0.03% higher to 48.62. Brent crude declined 0.63% to 108.07 while gold rose 0.79% to 4,367.10 and Bitcoin fell 2.92% to 75,879.98. No economic data prints were recorded for any of the five countries.
Market participants focused on external factors rather than domestic releases. A past Polish attempt to purchase Venezuelan oil via cryptocurrency resurfaced in headlines but carried no immediate market impact.
The Day Ahead
Three medium-impact indicators are scheduled over the coming week. Turkey will publish Business Confidence on 21 September and the Consumer Confidence Index on 22 September, both carrying the same release time of 03:00 ET. Poland will release its Unemployment Rate on 23 September at 03:30 ET.
No central-bank meetings or sovereign bond auctions are listed for the immediate horizon. Markets will monitor these prints for any early signals on Turkish sentiment and Polish labour-market resilience ahead of the October policy round. The absence of fresh data today leaves regional assets sensitive to global risk sentiment and commodity swings.
Other Economic Notes
Poland remains the largest EU member among the five economies and maintains the closest trade linkages with the euro area. Energy-import dependence continues to shape fiscal and external balances across the region, particularly for Hungary and the Czech Republic. Turkey operates under separate inflation dynamics and geopolitical constraints that limit policy convergence with the other four central banks.
EU fund disbursements and rule-of-law milestones remain key variables for Poland, Hungary and Romania. No new accession-related developments emerged in the latest session. Broader European growth differentials, illustrated by multinational AI spending in Ireland, may influence capital allocation toward Poland and the Czech Republic in coming quarters.