Emerging Europe Macro Daily(Beta Mode)
Poland CPI Climbs to 3.4% as BIST Drops 5.5%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
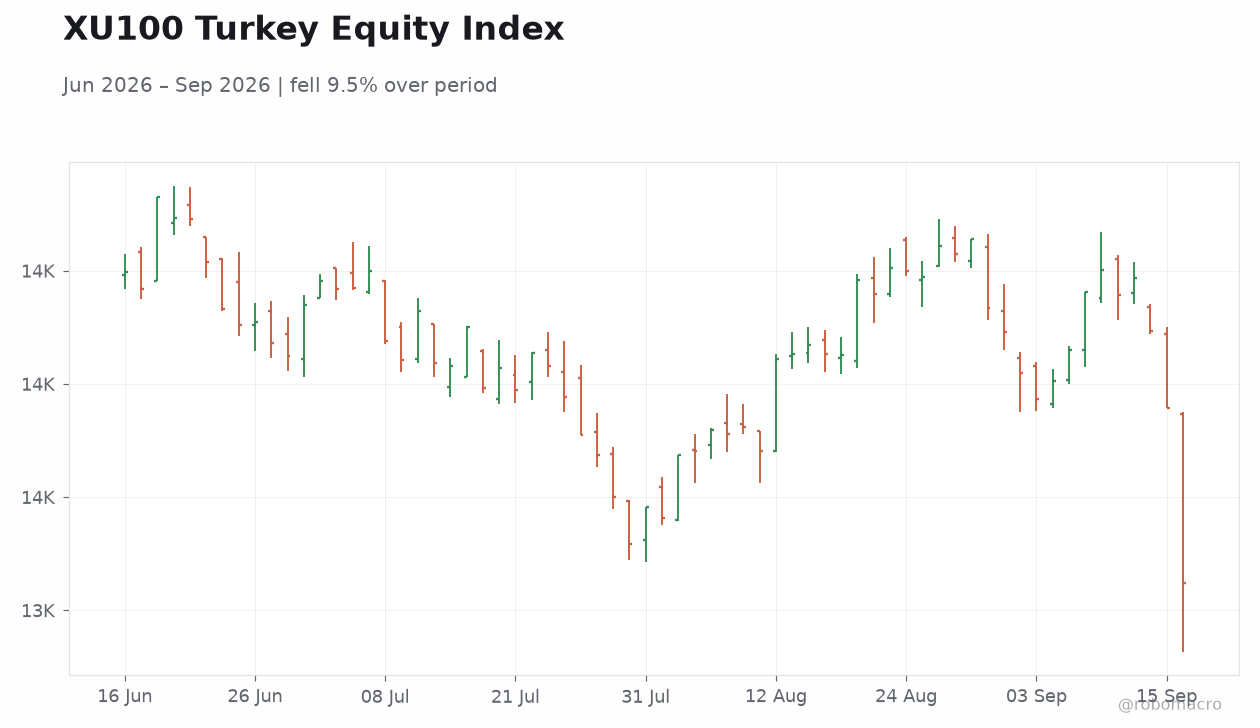
| BIST 100 | 13,122.60 | -5.54% |
| iShares Poland | 44.17 | -1.54% |
| EUR/PLN | 4.36 | +0.63% |
| EUR/HUF | 364.74 | +0.02% |
| EUR/CZK | 24.32 | +0.16% |
| USD/TRY | 48.66 | +0.06% |
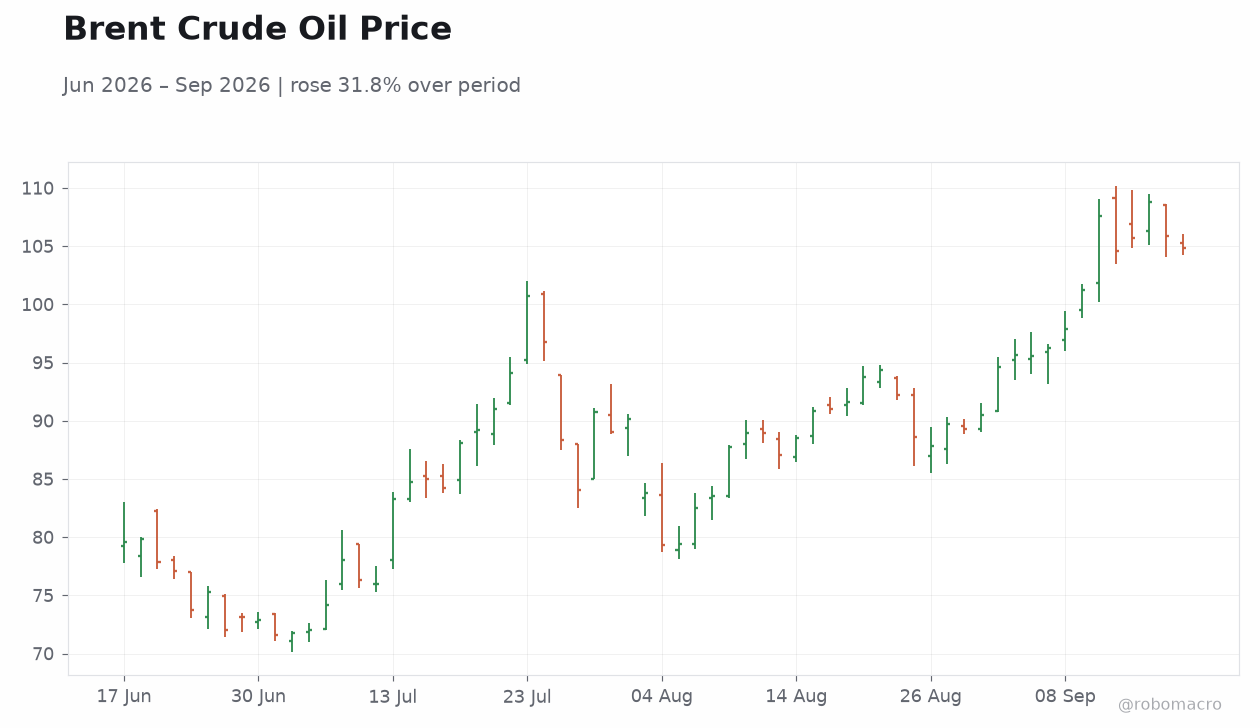
| Brent Crude | 104.98 | -0.80% |
| Gold | 4,342.90 | -1.02% |
| Bitcoin | 76,355.94 | +0.98% |
| Poland 10Y Govt Yield | - | - |
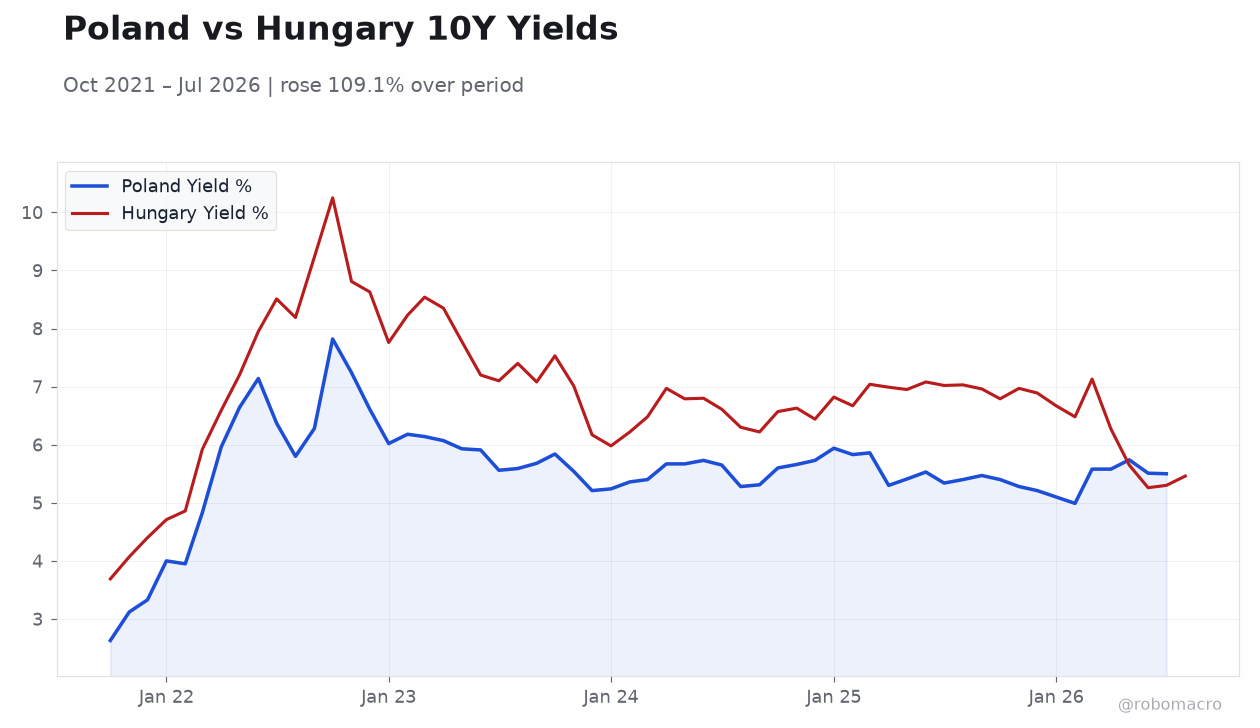
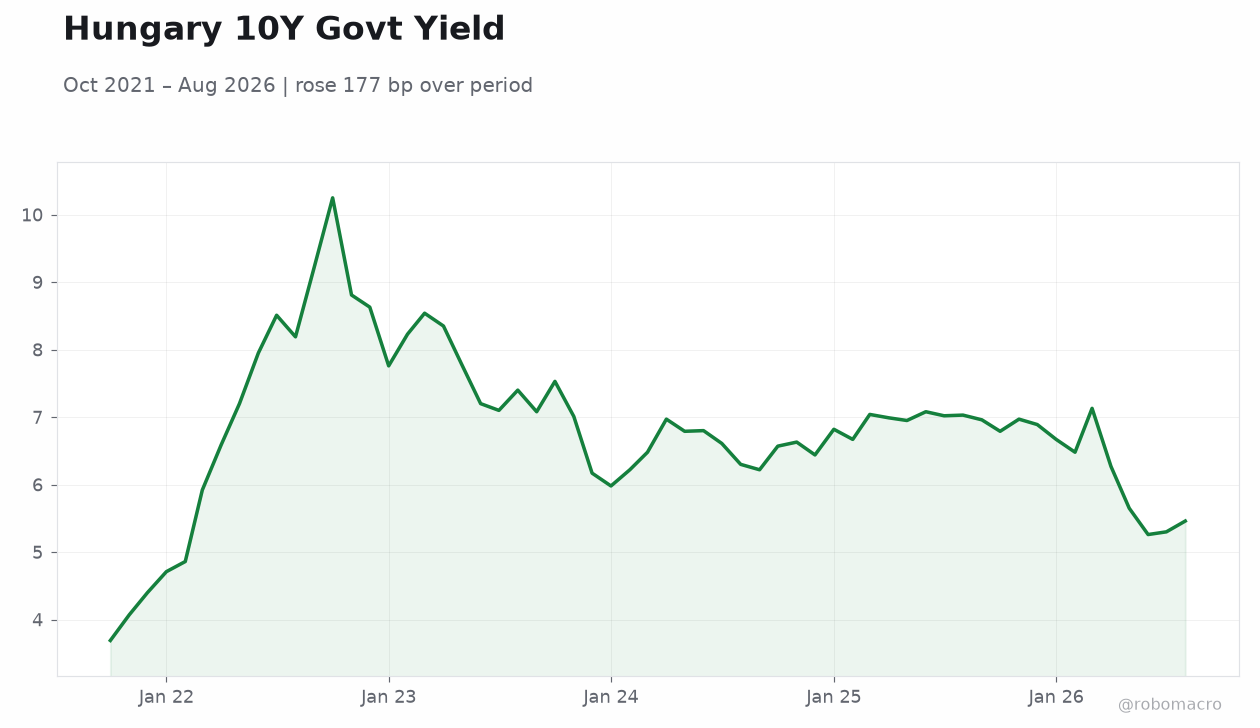
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
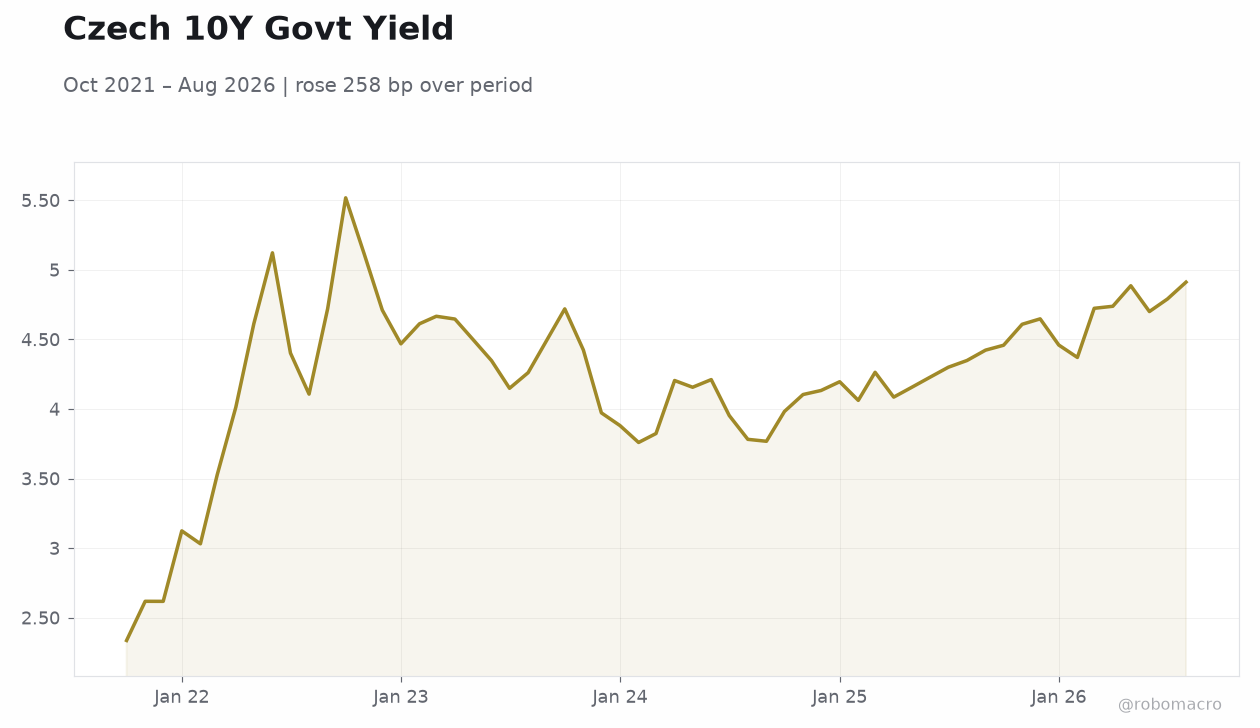 Czech 10Y Govt Yield | Type: macro_line | Yield %: 4.912 (2026-08-01) | Range: 2.336–5.518 | Trend(6pt): 2.336,4.711,3.76,4.085,4.701,4.912
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Business Confidence | 102.80 | - | 03:00 |
| Consumer Confidence Index | 90.80 | - | 03:00 |
| Unemployment Rate | 5.80 | - | 03:30 |
- Poland August CPI rose to 3.4% y/y with core at 3.3%, keeping NBP on hold.
- BIST 100 plunged 5.54% while EUR/PLN gained 0.63% to 4.36.
- Turkey Business Confidence and Poland Unemployment Rate headline the week ahead.
Yesterday's Recap
Poland’s statistical office reported August CPI accelerating to 3.4% y/y from 3.0% in July, with the rise tied to energy costs amid regional tensions. Core inflation excluding food and energy climbed to 3.3%, confirming persistent underlying pressures that will likely delay any NBP easing. The NBP published matching core readings, reinforcing the stickiness message.
Equity markets reflected the data and risk-off mood, with the iShares Poland ETF falling 1.54%. BIST 100 dropped 5.54% to 13,122.60 as Turkish assets faced separate selling pressure. EUR/PLN rose 0.63% to 4.36, while EUR/HUF and EUR/CZK posted smaller gains.
A Russian drone carrying an explosive warhead was recovered off Poland’s coast, adding geopolitical caution without immediate pricing impact. The ECB’s 2.50% deposit rate and Eurozone CPI of 3.30% y/y continue to anchor capital-flow expectations across the region.
The Day Ahead
Market focus turns to Turkey’s Business Confidence survey due September 21 and the Consumer Confidence Index the following day. Poland’s Unemployment Rate for August is scheduled for release on September 23. No central-bank meetings, EU summits or sovereign bond auctions are listed for the immediate horizon.
These prints will offer fresh readings on Turkish sentiment and Polish labor-market slack. Regional FX and equity flows will also track any follow-through from yesterday’s Polish inflation surprise and Turkish equity weakness. Energy-price volatility remains a key variable for imported inflation across Poland, Czechia, Hungary and Romania.
Other Economic Notes
Czech policymakers are poised to hold rates for a second consecutive meeting as surging oil prices and a widening budget deficit raise tightening bets. The ECB’s 2.50% deposit rate and Eurozone CPI of 3.30% y/y continue to anchor capital-flow and convergence expectations across the four EU members in the region. Hungary’s new government is moving quickly to dismantle prior institutional structures, which could alter fiscal-monetary coordination and EU-fund absorption.
Shared energy-import vulnerabilities remain a key macro risk for Poland, Czechia, Hungary and Romania. Brent crude at 104.98 offers modest relief but does not remove the underlying exposure.