Emerging Europe Macro Daily(Beta Mode)
US-Poland Base Talks Lift BIST, Forint Gains
Market Snapshot
| Asset | Level | Change |
|---|---|---|
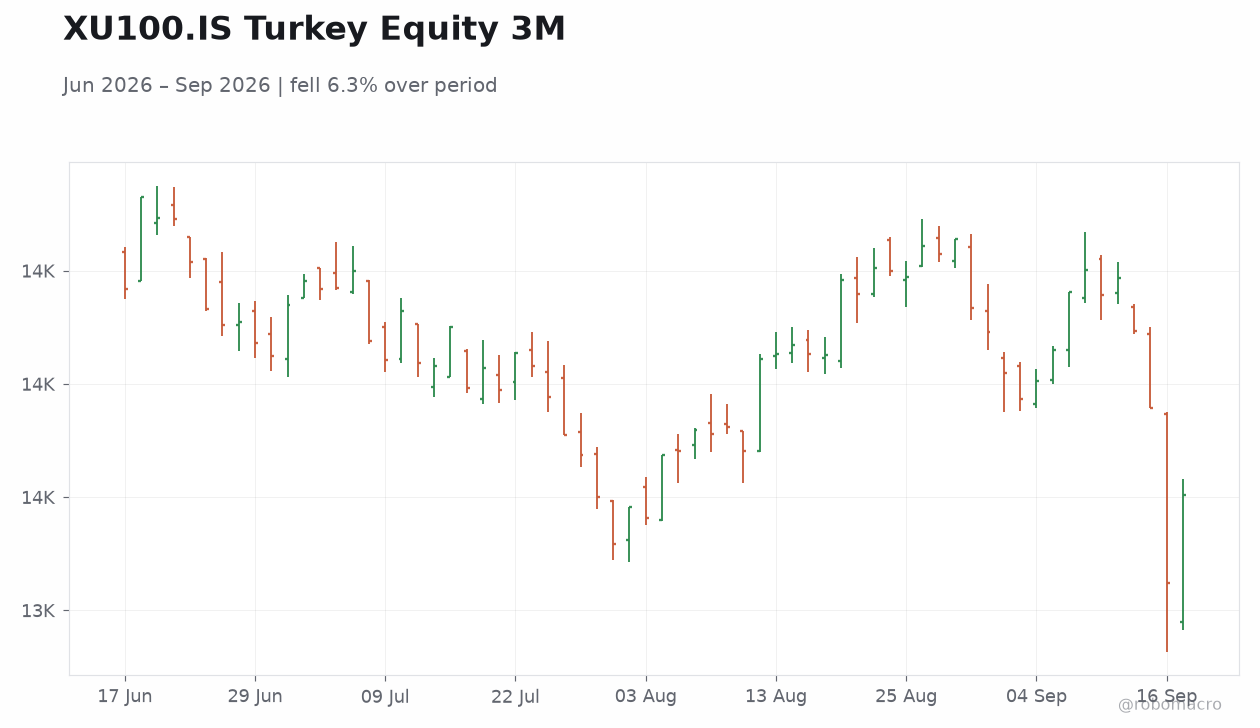
| BIST 100 | 13,509.80 | +2.95% |
| iShares Poland | 44.78 | +1.38% |
| EUR/PLN | 4.35 | -0.10% |
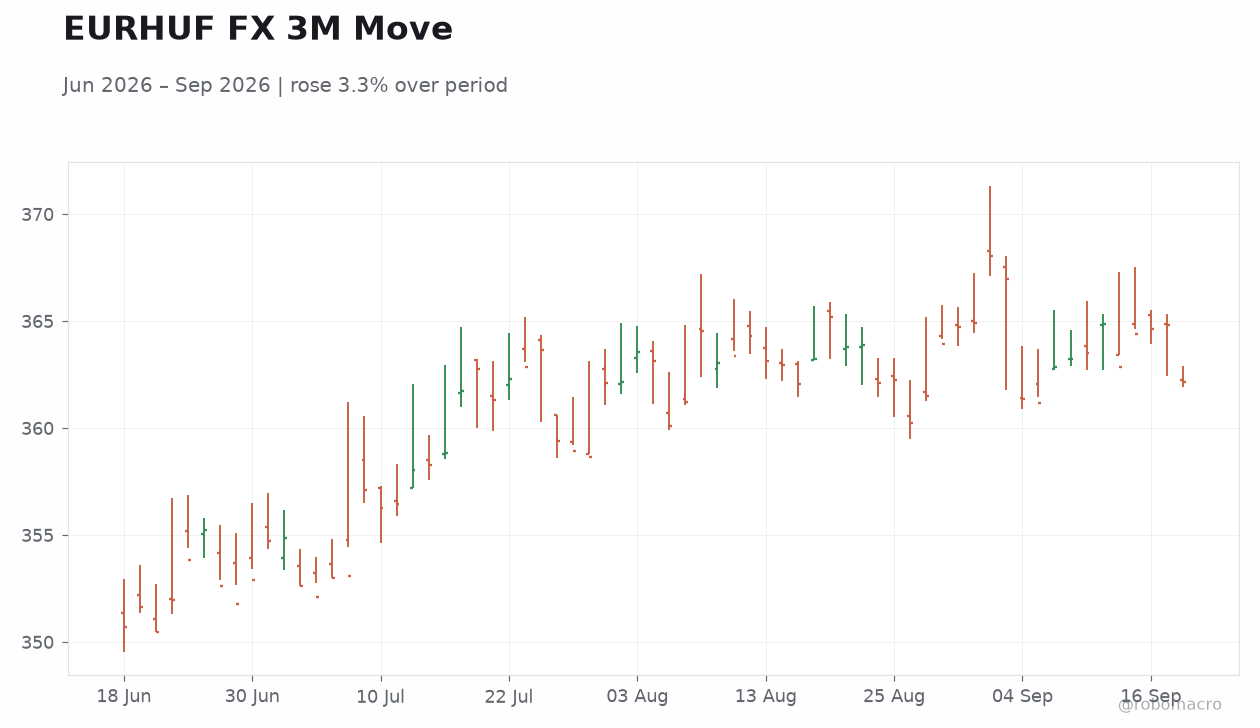
| EUR/HUF | 362.25 | -0.70% |
| EUR/CZK | 24.31 | +0.02% |
| USD/TRY | 48.78 | +0.23% |
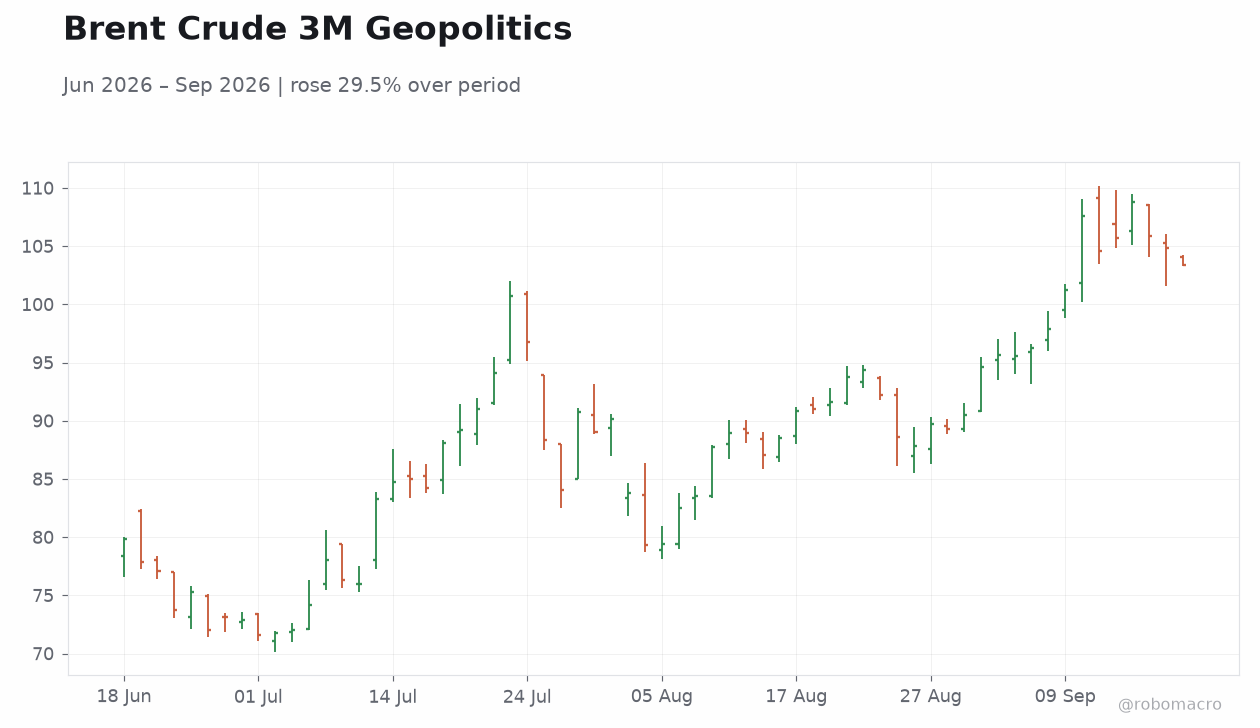
| Brent Crude | 103.54 | -1.22% |
| Gold | 4,426.30 | +0.60% |
| Bitcoin | 77,423.40 | +1.67% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
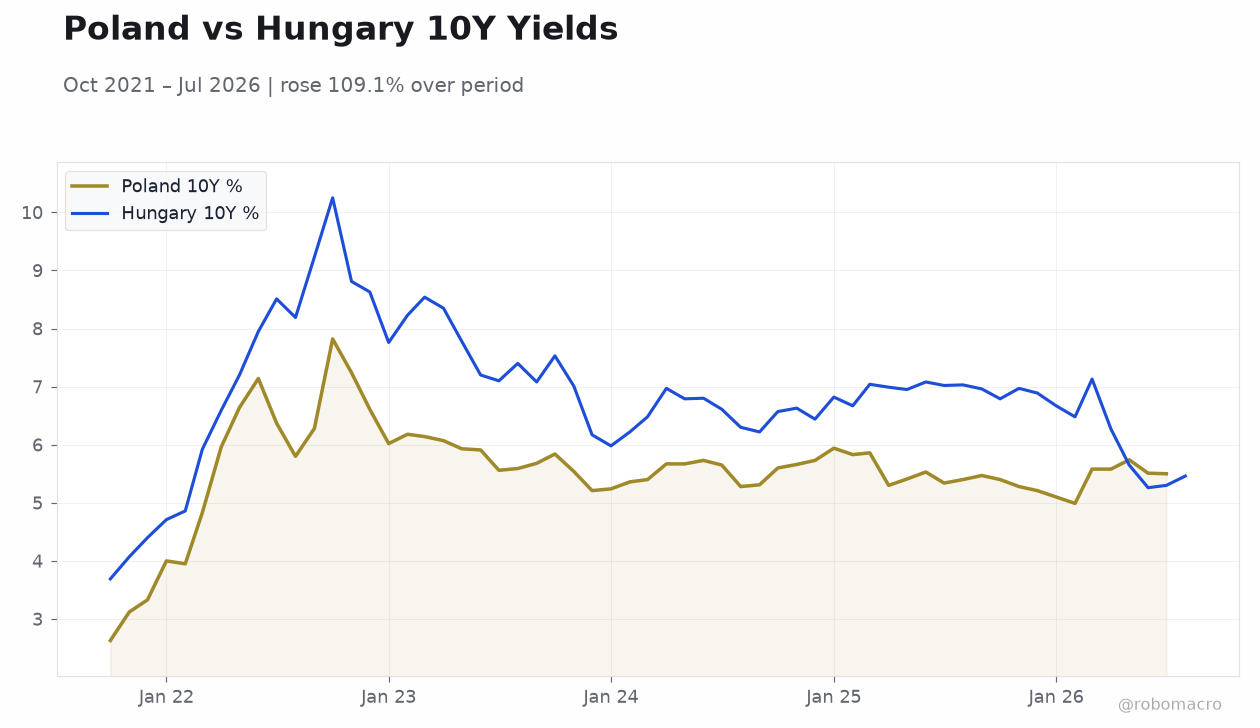 Poland vs Hungary 10Y Yields | Type: macro_line | Poland 10Y %: 5.5 (2026-07-01) | Range: 2.63–7.82 | Trend(6pt): 2.63,6.61,5.36,5.3,5.51,5.5 | Hungary 10Y %: 5.46 (2026-08-01) | Range: 3.69–10.25 | Trend(6pt): 3.69,8.63,6.22,6.99,5.26,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Poland advances US army base agreement, supporting regional equities and defense exports
- BIST 100 surges 2.95% while forint strengthens 0.70% against euro on Fed decision
- Empty data calendar leaves focus on NBP benchmark transition and CNB rate hold signals
Yesterday's Recap
No macroeconomic releases emerged from Poland, Czech Republic, Hungary, Romania or Turkey on 17 September, leaving market moves driven by geopolitics and external policy signals. BIST 100 climbed 2.95% to 13,509.80 while iShares Poland gained 1.38% to 44.78. EUR/HUF fell 0.70% to 362.25 and EUR/PLN eased 0.10% to 4.35, with EUR/CZK rising just 0.02% to 24.31 and USD/TRY adding 0.23% to 48.78.
President Trump stated the United States and Poland are close to finalising an American army base deal, reversing earlier Pentagon withdrawal plans and reinforcing bilateral security ties. Poland’s Black Hawk helicopter delivery to the Philippines also opened avenues for further Warsaw defence exports. NBP urged allowance of a correcting spread for banks during the WIBOR-to-POLSTR transition in legacy contracts, without shifting the policy-rate outlook.
Brent crude dropped 1.22% to 103.54 while gold rose 0.60% to 4,426.30.
The Day Ahead
The calendar remains empty for 18-19 September across Poland, Czech Republic, Hungary, Romania and Turkey, with no central-bank meetings, auctions or EU summits scheduled. Markets will therefore track external drivers including any follow-through on US-Poland base negotiations and euro-area inflation prints. Regional FX and equity flows may respond to ECB commentary on the 2.50% deposit rate amid 3.20% Eurozone CPI.
Energy price volatility could influence Hungary and Turkey import costs given shared exposure to global oil moves. Traders will also monitor any updates on Czech state-asset sales plans under the new investment push.
Other Economic Notes
Poland’s defence diplomacy provides a growth-supportive channel through potential US troop spending and export orders, distinct from pure trade linkages. Czech policymakers face tightening bets from energy-price and budget-deficit risks even as they prepare to hold rates again. Hungary’s forint benefited from the Fed’s 25-basis-point hike to the 3.75-4.00% range, illustrating sensitivity to dollar strength in a high-debt environment.
Romania and Turkey remain on divergent paths, with the latter’s political constraints limiting conventional inflation targeting despite structurally elevated price pressures. Shared EU-member energy import dependence continues to transmit global commodity shocks into domestic inflation dynamics.