Emerging Europe Macro Daily(Beta Mode)
MNB Rate Hold Looms as Polish Jobs Data Due
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 13,337.70 | +0.40% |
| iShares Poland | 45.67 | +2.84% |
| EUR/PLN | 4.35 | -0.24% |
| EUR/HUF | 361.74 | -0.66% |
| EUR/CZK | 24.32 | -0.02% |
| USD/TRY | 48.81 | +0.08% |
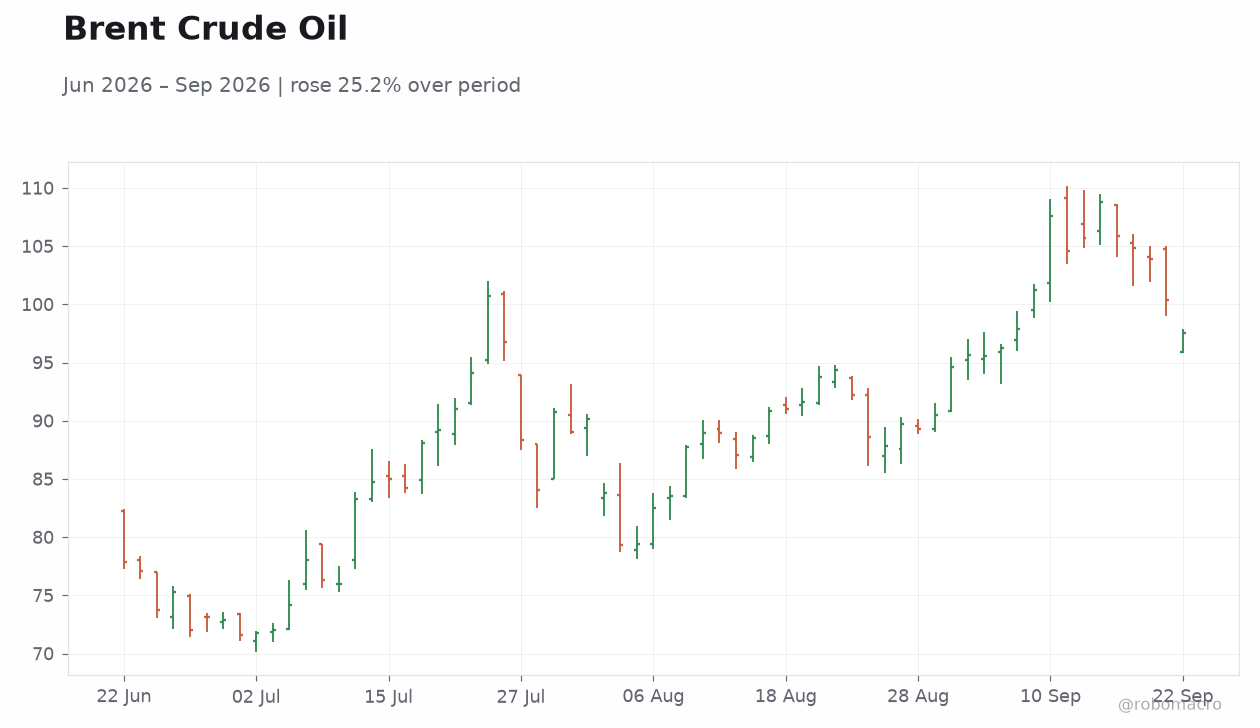
| Brent Crude | 97.63 | -2.70% |
| Gold | 4,356.00 | -0.64% |
| Bitcoin | 85,450.02 | +5.31% |
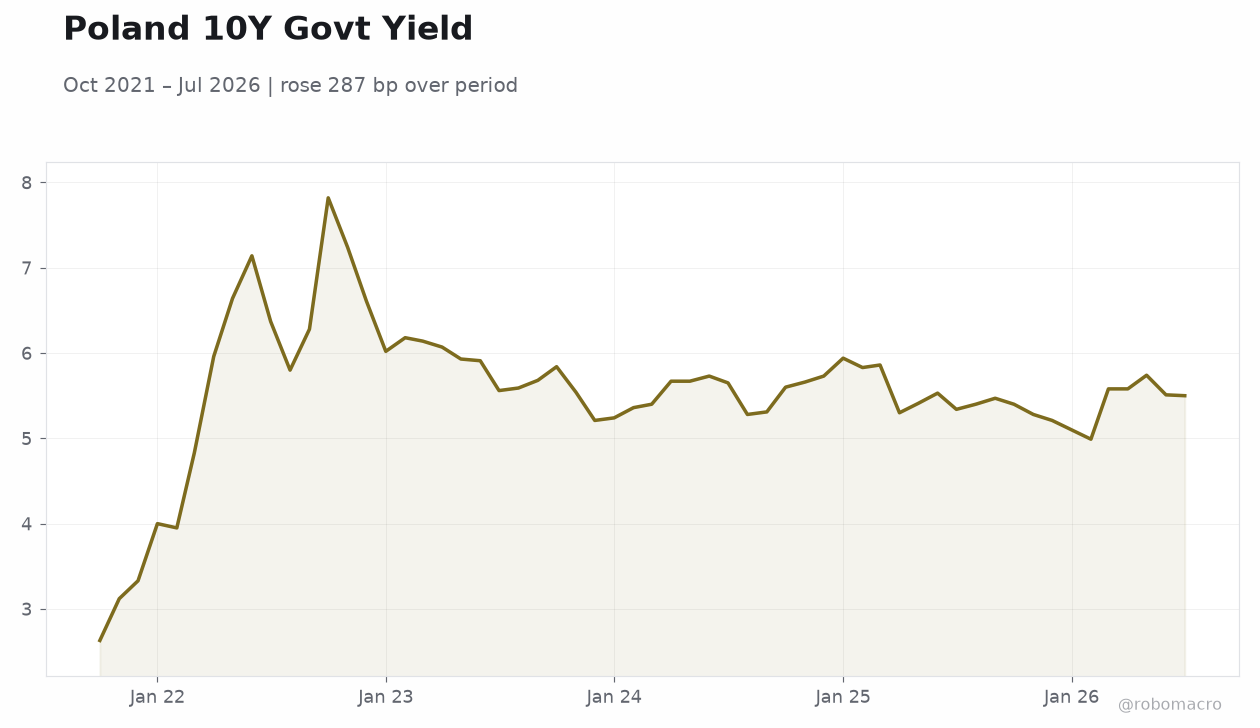
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Business Confidence | 102.80 | - | 102 |
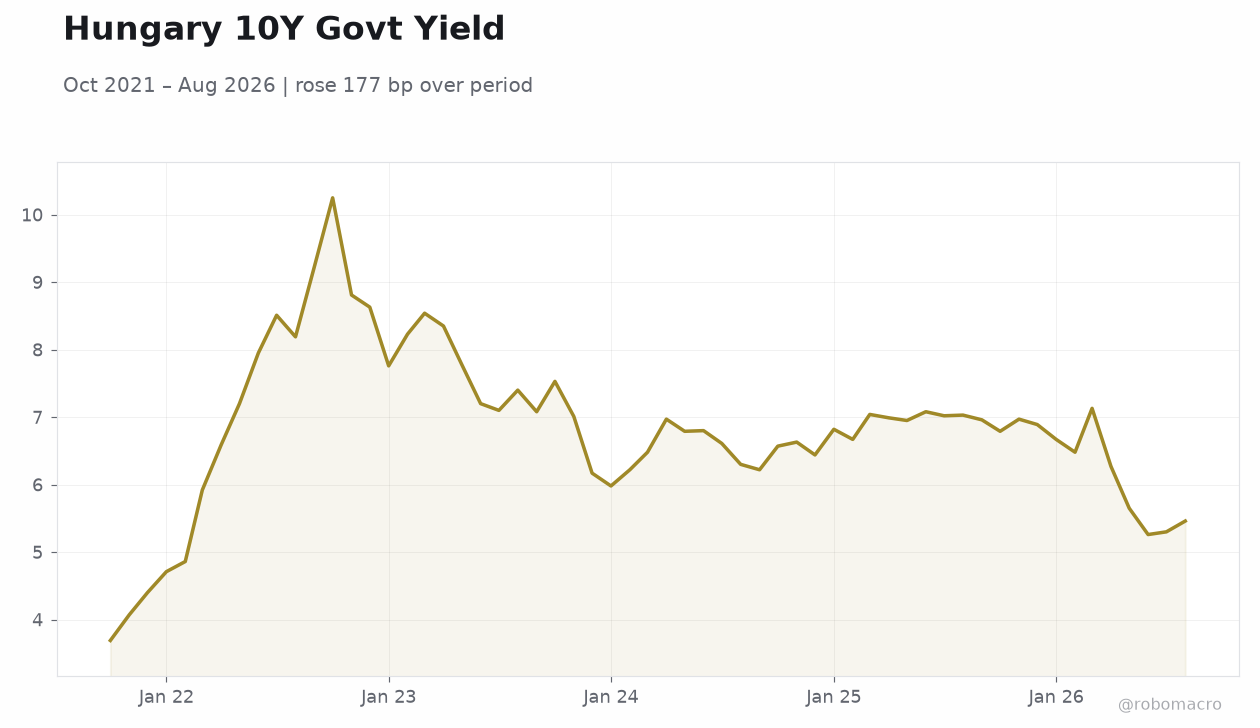 Hungary 10Y Govt Yield | Type: macro_line | Yield %: 5.46 (2026-08-01) | Range: 3.69–10.25 | Trend(6pt): 3.69,8.63,6.22,6.99,5.26,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Consumer Confidence Index | 90.80 | - | 23:00 |
| Central Bank Interest Rate Decision | 5.50 | 5.50 | 04:00 |
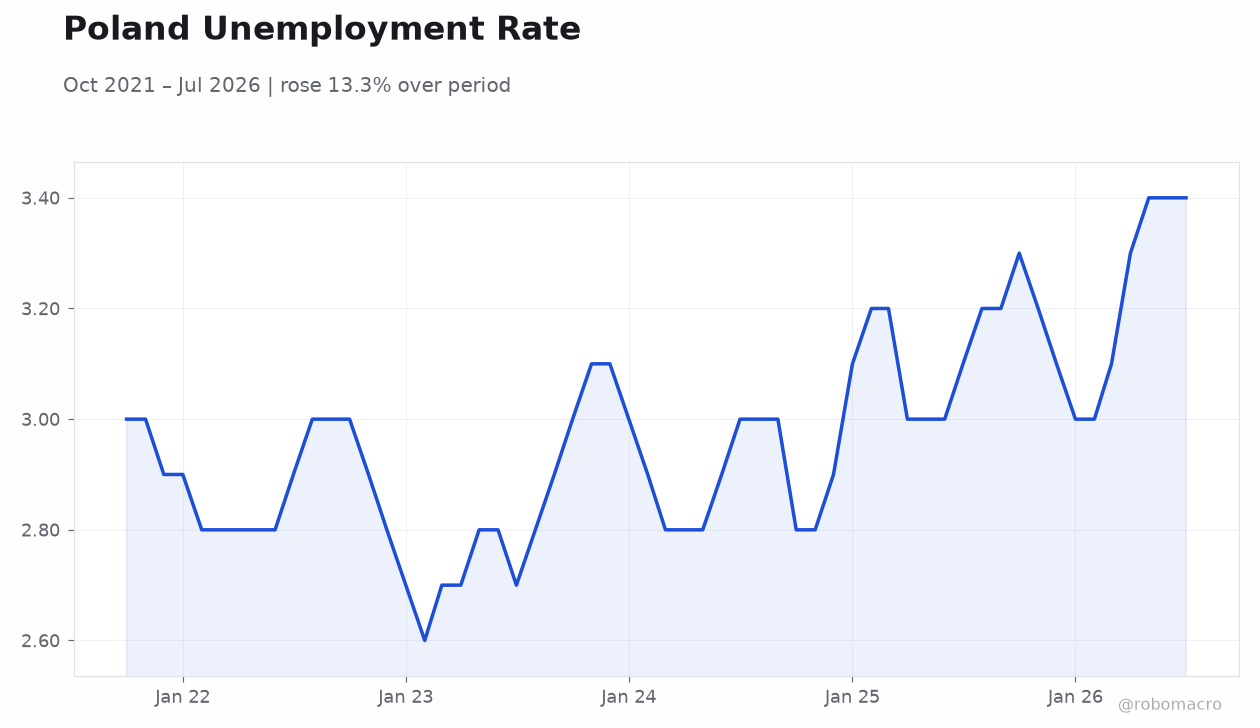
| Unemployment Rate | 5.80 | 5.90 | 23:30 |
- Hungary’s MNB set to hold policy rate at 5.5% amid stable inflation outlook.
- Turkey business confidence slipped to 102.0 while Polish unemployment edges higher.
- Regional equities advanced with iShares Poland up 2.84% and BIST 100 gaining 0.40%.
Yesterday's Recap
Turkey’s Business Confidence Index fell to 102.0 in August from 102.8, signaling softening sentiment ahead of today’s consumer reading. Equity markets posted gains, with BIST 100 rising 0.40% to 13,337.70 and iShares Poland surging 2.84% to 45.67. Currencies moved modestly, as EUR/PLN declined 0.24% to 4.35 and EUR/HUF dropped 0.66% to 361.74 while USD/TRY edged 0.08% higher to 48.81.
Brent crude fell 2.70% to 97.63, easing energy import costs for the region. NBP continued gold purchases in August, staying on track for its 700-ton target and bolstering reserve diversification. No CPI or industrial production releases emerged from Poland, Czech Republic, Hungary or Romania.
The modest Turkish confidence dip left near-term inflation expectations largely unchanged across the five economies.
The Day Ahead
Hungary’s MNB will announce its policy rate decision at 04:00 ET, with consensus pointing to an unchanged 5.5% level after three prior cuts. Turkey releases its Consumer Confidence Index at 23:00 ET, following yesterday’s business-sentiment decline. Poland publishes its August unemployment rate at 23:30 ET, with the consensus at 5.9% versus the prior 5.8%.
No sovereign bond auctions or EU fund-disbursement events are scheduled. Markets will watch the Hungarian decision for any shift in the cautious stance that has kept forint volatility contained. The Polish labor print offers the next local signal on wage pressures feeding into NBP policy deliberations.
Other Economic Notes
Energy import dependence remains a shared vulnerability for Poland, Hungary and the Czech Republic despite lower Brent prices. EU fund flows continue to support fiscal positions in Romania and Poland, though rule-of-law reviews have not produced new disbursements. Regional equity outperformance versus broader emerging-market indices reflects improved risk appetite after the latest ECB signals.
Inflation dynamics diverge sharply, with Turkey’s structurally higher rate path contrasting the more contained readings in the EU members. Gold accumulation by NBP underscores ongoing reserve diversification amid geopolitical uncertainty.