Emerging Europe Macro Daily(Beta Mode)
MNB Holds at 5.5% as Polish Fuel Shock Hits
Market Snapshot
| Asset | Level | Change |
|---|---|---|
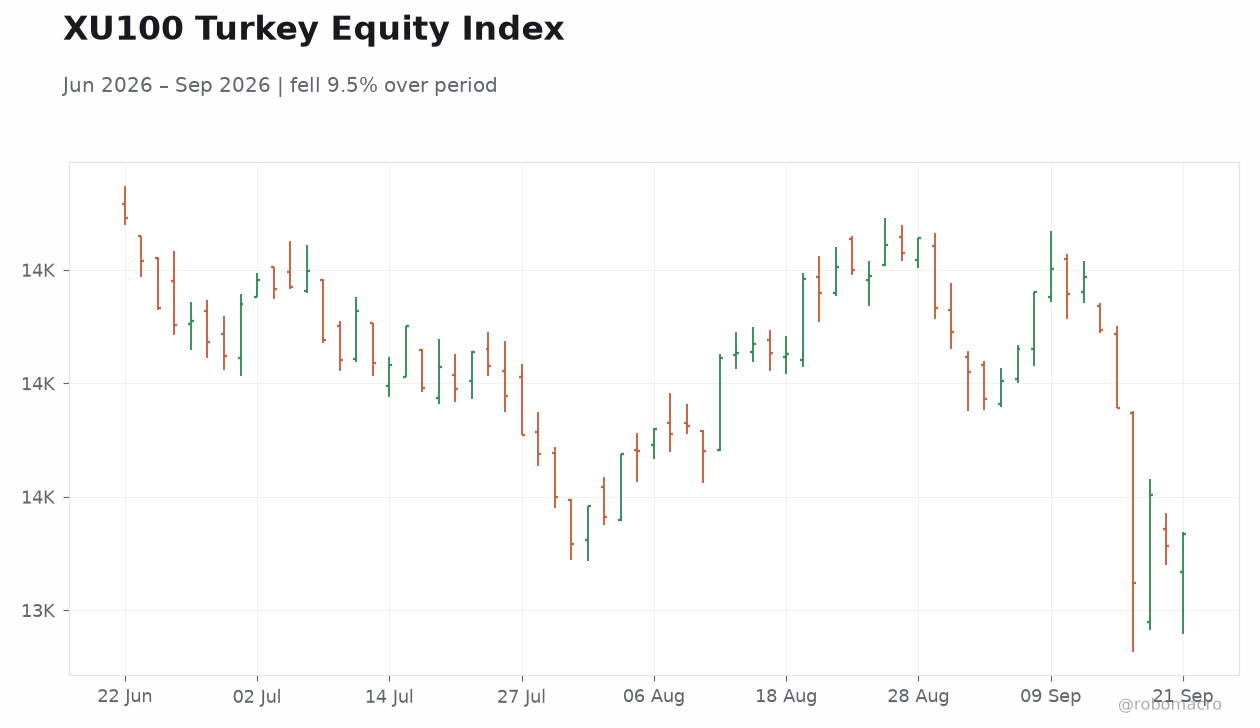
| BIST 100 | 13,337.70 | +0.40% |
| iShares Poland | 45.38 | -0.63% |
| EUR/PLN | 4.35 | +0.16% |
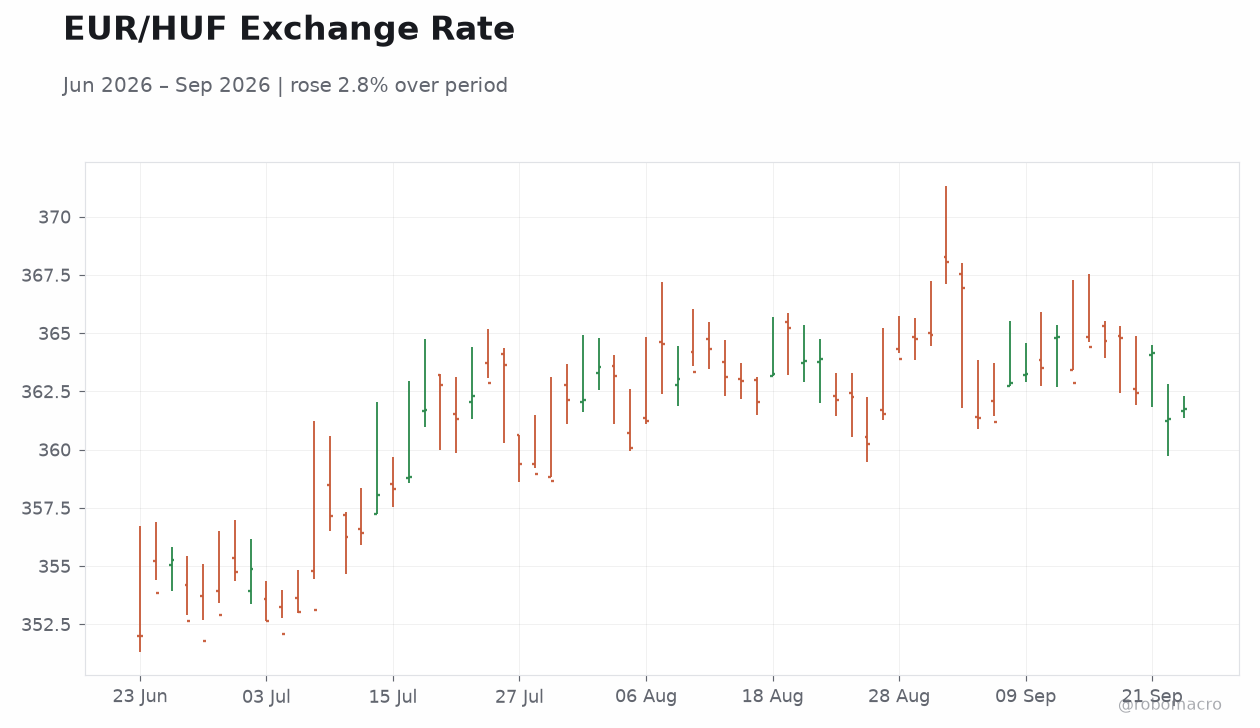
| EUR/HUF | 361.73 | +0.11% |
| EUR/CZK | 24.34 | +0.15% |
| USD/TRY | 48.83 | +0.05% |
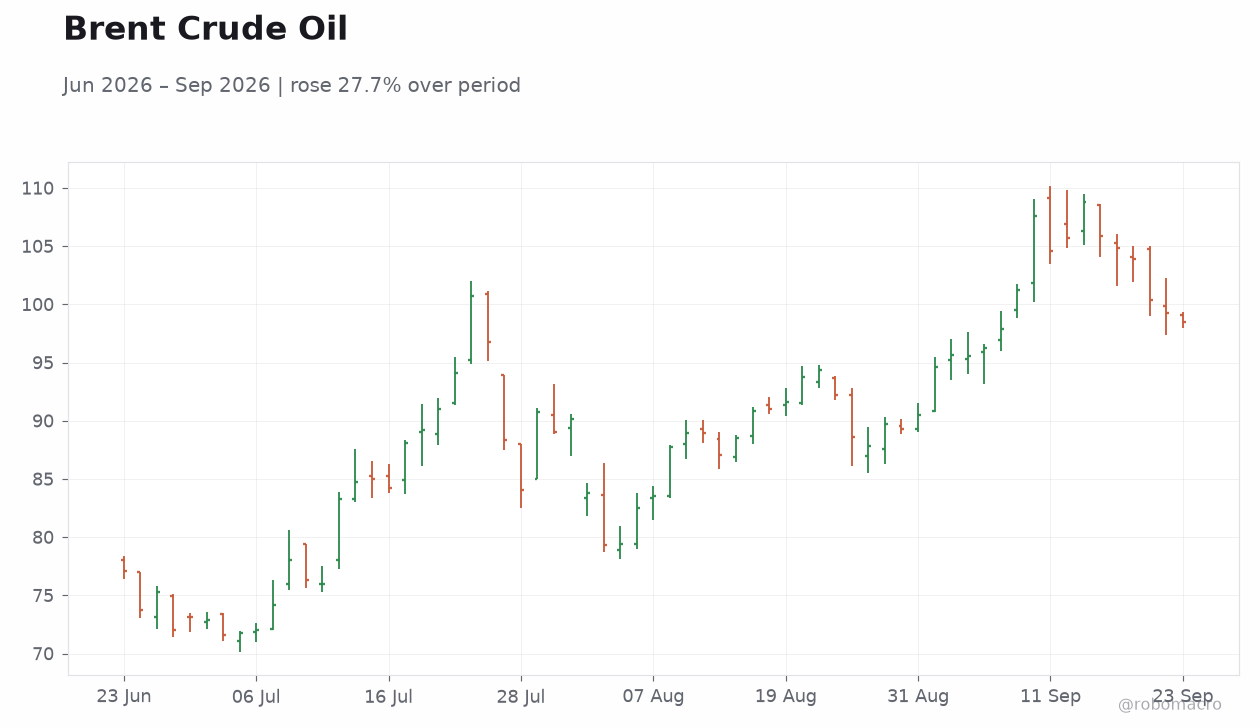
| Brent Crude | 98.39 | -0.87% |
| Gold | 4,379.70 | +0.08% |
| Bitcoin | 86,811.52 | +0.24% |
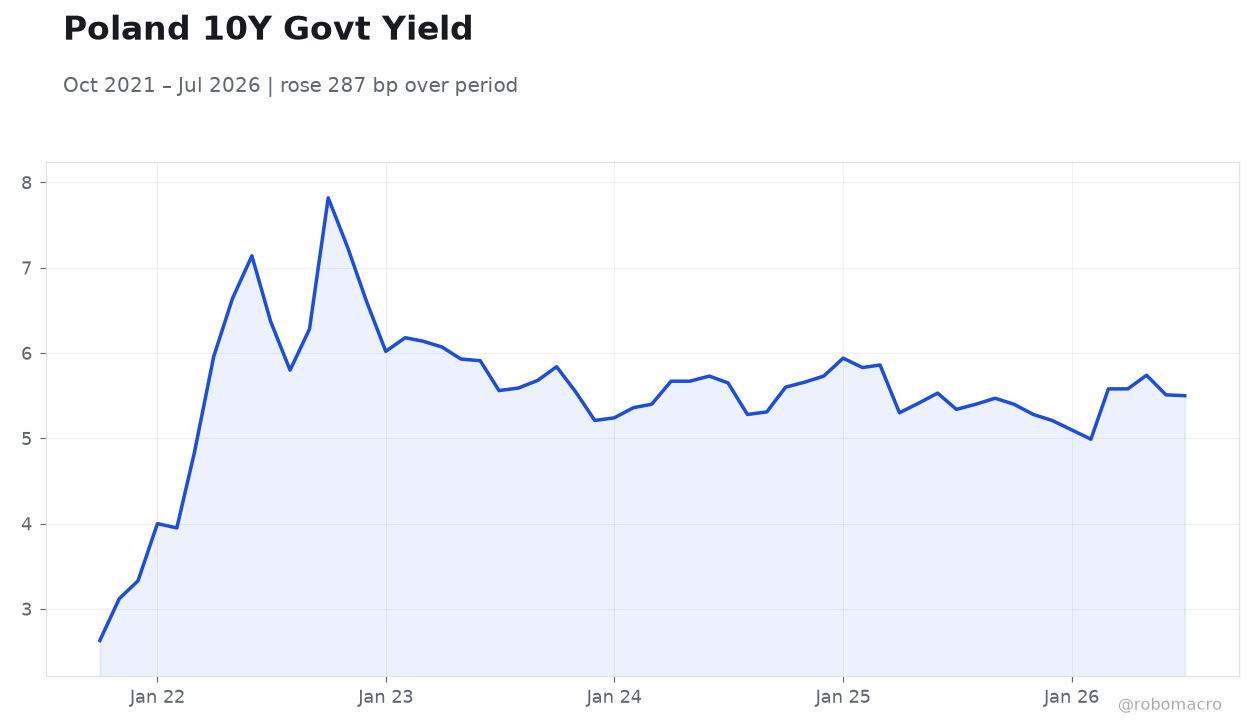
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
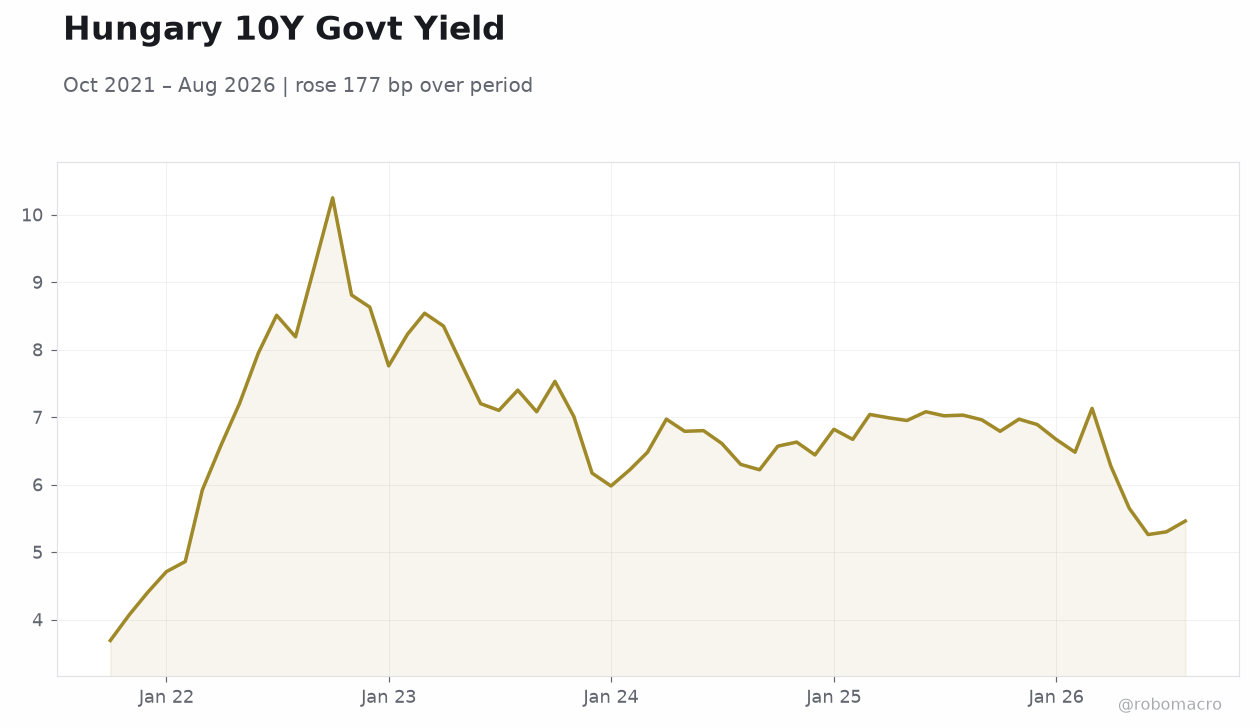 Hungary 10Y Govt Yield | Type: macro_line | Yield %: 5.46 (2026-08-01) | Range: 3.69–10.25 | Trend(6pt): 3.69,8.63,6.22,6.99,5.26,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MNB kept base rate at 5.5% and released updated forecasts while analysts noted the pause after summer easing
- Diesel prices reached PLN 8 per litre in Poland, spreading cost pressures through transport and industry amid no fresh data releases
- BIST 100 rose 0.40% while iShares Poland fell 0.63% and regional currencies weakened modestly against the euro
Yesterday's Recap
Hungary’s central bank held its policy rate at 5.5% and released fresh macroeconomic forecasts, ending the summer easing cycle as the committee cited stable inflation risks. Polish diesel prices hit PLN 8 per litre, with reports highlighting the direct hit to logistics costs and broader price transmission across the economy. The 34th International Defense Industry Fair in Kielce featured Turkish participation and bilateral messaging on defense cooperation.
BIST 100 advanced 0.40% to 13,337.70 while iShares Poland declined 0.63% to 45.38. EUR/PLN rose 0.16% to 4.35, EUR/HUF gained 0.11% to 361.73 and EUR/CZK added 0.15% to 24.34, with USD/TRY edging 0.05% higher to 48.83. Brent crude fell 0.87% to 98.39 while gold ticked up 0.08%.
No macroeconomic releases occurred in any of the five markets, leaving investors focused on the MNB statement and Polish energy prices.
The Day Ahead
The calendar remains empty for 23-24 September across Poland, Czech Republic, Hungary, Romania and Turkey, with zero scheduled data prints or policy meetings. Traders will monitor any follow-up comments from MNB officials after yesterday’s decision and forecast update. Polish fuel-price developments may generate further domestic commentary on cost-of-living pressures.
Regional FX desks will watch ECB speakers for signals that could influence forint and zloty positioning ahead of month-end flows. No sovereign auctions or EU-related disbursements are listed.
Other Economic Notes
Poland’s diesel surge underscores the region’s continued exposure to imported energy costs despite diversified supply routes. Hungary’s decision to pause easing while updating forecasts signals greater medium-term credibility ambitions. The absence of releases leaves markets reliant on external drivers such as euro-area growth and global commodity trends.
EU fund flows and rule-of-law milestones remain quiet, keeping convergence narratives on hold for the four EU members. Turkey’s distinct inflation and FX dynamics continue to set it apart from the CEE group.