Emerging Europe Macro Daily(Beta Mode)
MNB Holds at 5.5%, CEE FX Strengthens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 12,899.40 | +0.09% |
| iShares Poland | 44.85 | +0.29% |
| EUR/PLN | 4.34 | -0.72% |
| EUR/HUF | 364.79 | -0.13% |
| EUR/CZK | 24.31 | -0.33% |
| USD/TRY | 48.92 | -0.07% |
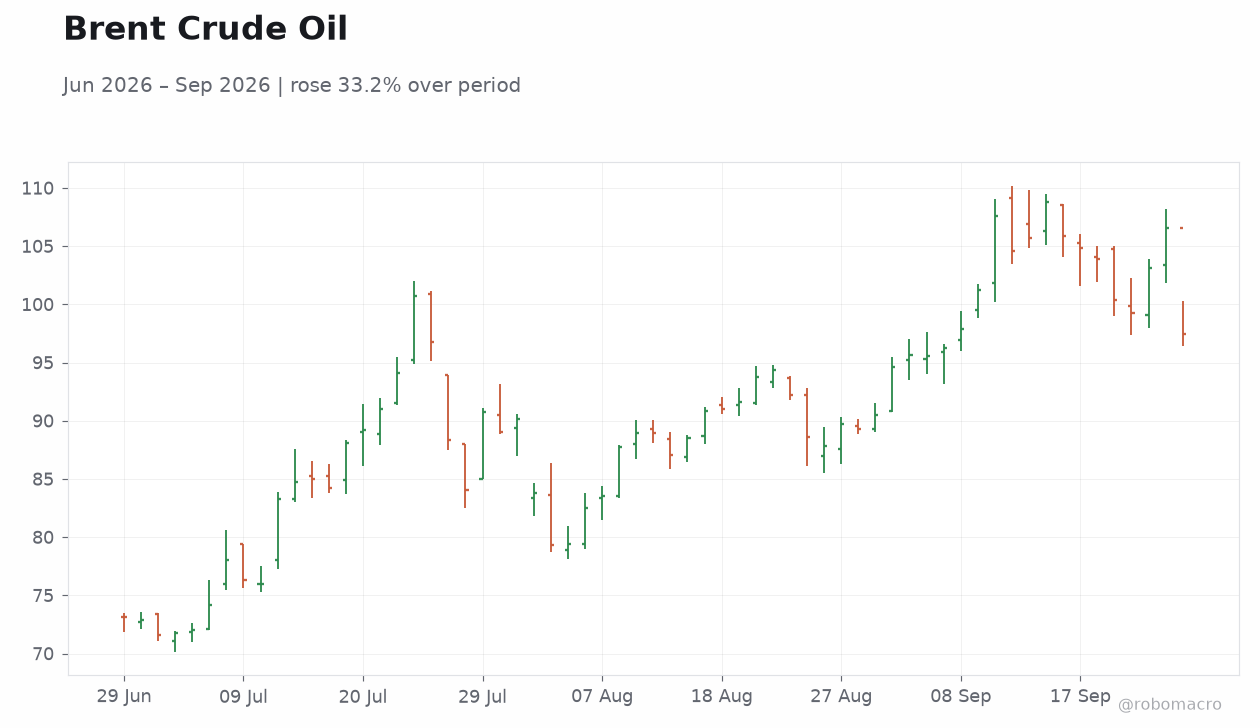
| Brent Crude | 97.44 | -8.59% |
| Gold | 4,321.20 | +0.54% |
| Bitcoin | 84,495.39 | +0.11% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Business Confidence Index | 102.80 | - | 102 |
| Consumer Confidence Index | 90.80 | - | 91.90 |
| Central Bank Interest Rate Decision | 5.50 | 5.50 | 5.50 |
| Headline Unemployment Rate | 5.80 | 5.90 | 5.80 |
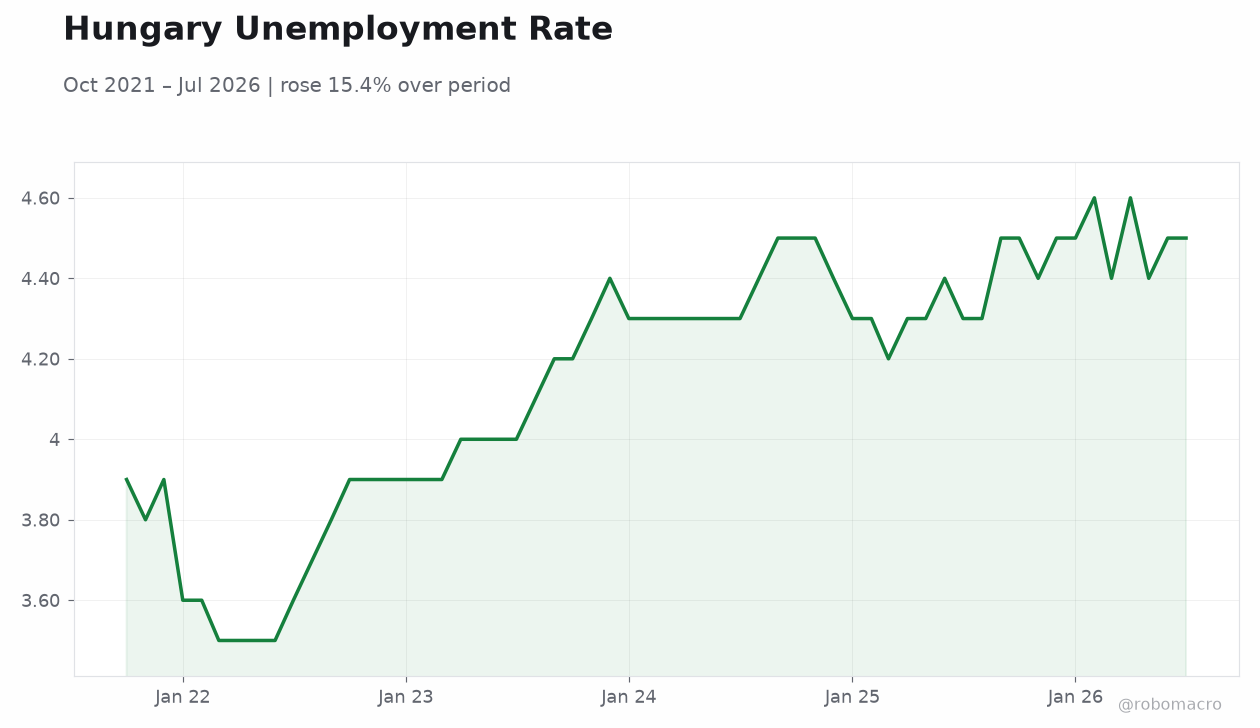
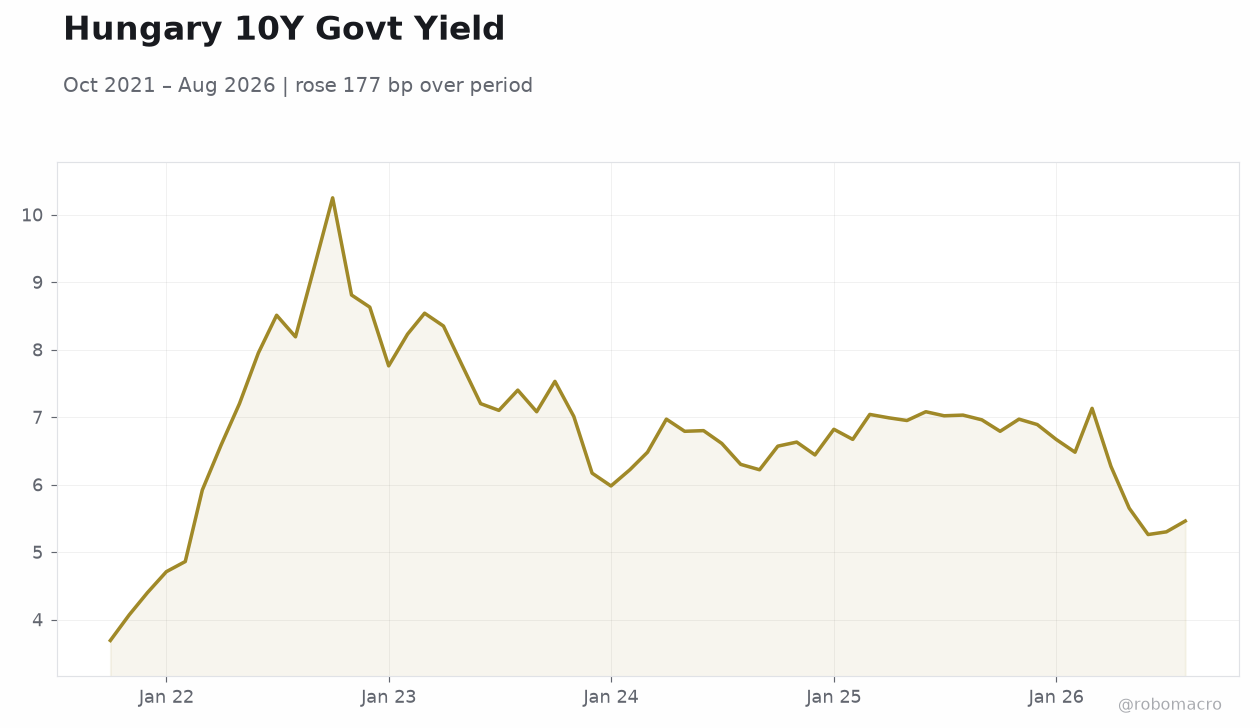 Hungary 10Y Govt Yield | Type: macro_line | Yield %: 5.46 (2026-08-01) | Range: 3.69–10.25 | Trend(6pt): 3.69,8.63,6.22,6.99,5.26,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MNB holds policy rate at 5.5% as expected, keeping Hungary aligned with ECB path
- Turkey posts mixed confidence readings with consumer index rising to 91.9 while business falls to 102.0
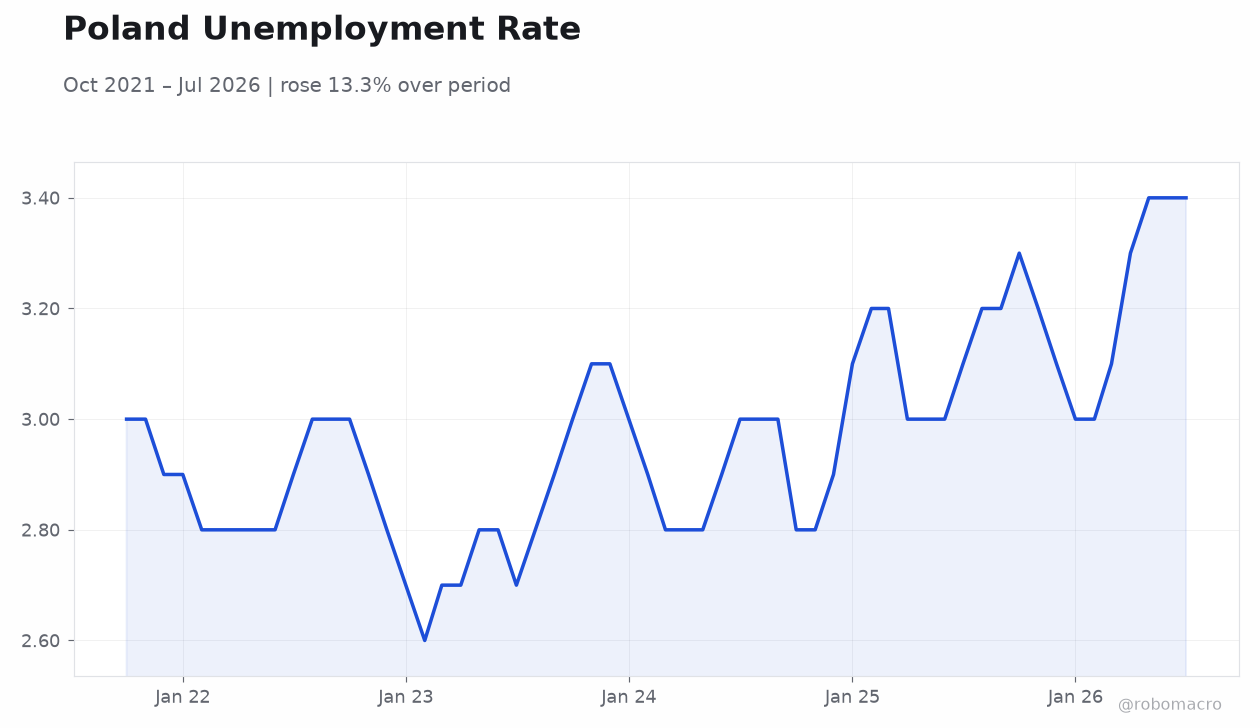
- Poland unemployment holds at 5.8%, beating consensus and supporting contained domestic demand
Yesterday's Recap
Hungary’s central bank left its key rate unchanged at 5.5%, matching both consensus and the prior level and signaling that current inflation and growth readings remain consistent with the MNB’s forward path. Turkey reported a Business Confidence Index decline to 102.0 from 102.8 alongside a Consumer Confidence Index improvement to 91.9 from 90.8, reflecting resilient households but ongoing corporate caution. Poland’s headline unemployment rate printed at 5.8%, unchanged from the previous month and 0.1pp below the 5.9% consensus, reinforcing the NBP’s assessment that labor-market pressures remain contained.
On markets, EUR/PLN fell 0.72% to 4.34 while EUR/HUF eased 0.13% to 364.79 and EUR/CZK dropped 0.33% to 24.31, indicating broad CEE currency strength. BIST 100 edged up 0.09% to 12,899.40 and iShares Poland rose 0.29% to 44.85. Brent crude plunged 8.59% to 97.44, while gold advanced 0.54% to 4,321.20.
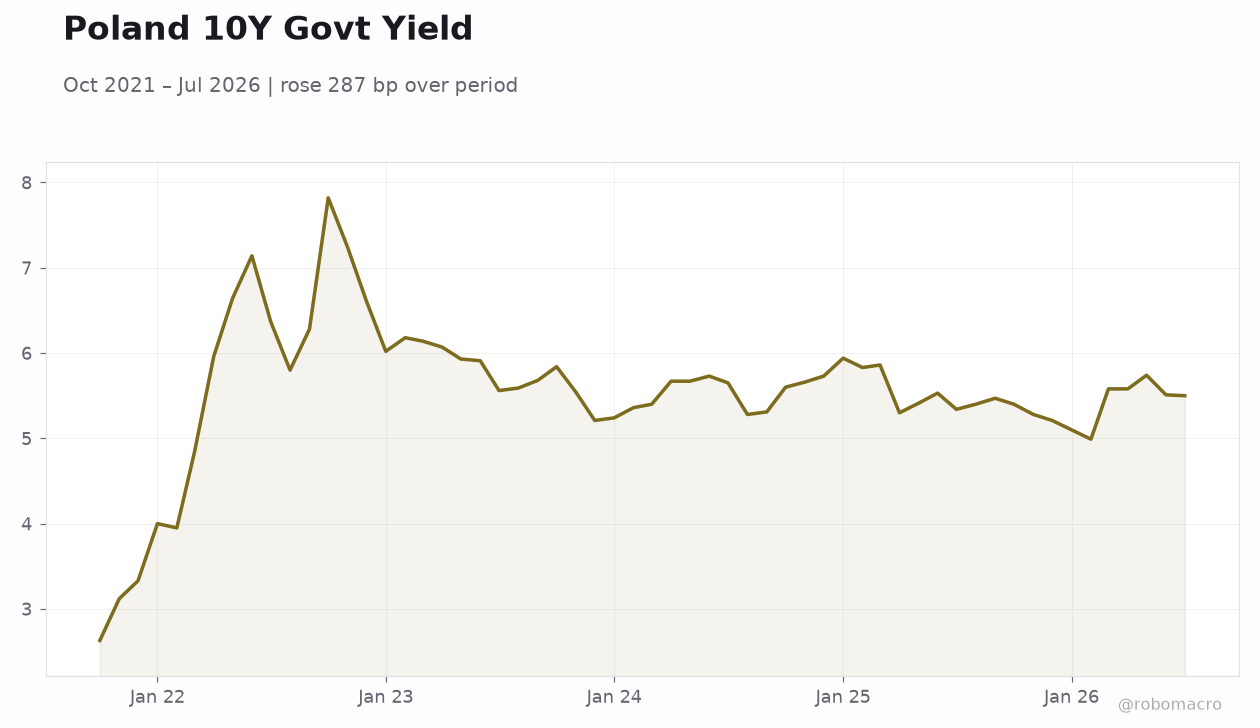
No sovereign yield prints were available for Poland or Hungary.
The Day Ahead
No macroeconomic releases, central-bank meetings or sovereign auctions are scheduled across Poland, Czech Republic, Hungary, Romania or Turkey for 25–26 September. The empty calendar leaves markets focused on incoming euro-area data and any ECB speakers for directional cues. Regional equity and FX trading is therefore likely to track global risk sentiment and Brent crude movements.
EU fund disbursement updates or any fiscal news from Prague could still surface and move CZK. Traders will monitor USD/TRY for any signs of renewed CBRT pressure amid the mixed Turkish confidence prints.
Other Economic Notes
Czech opposition parties triggered a no-confidence vote over next year’s budget, which projects the second-largest deficit on record and highlights fiscal strains ahead of potential EU fund talks. Poland’s accelerated military spending continues to reshape growth composition, with possible implications for EU convergence metrics and fiscal space. Hungary’s forint strength is already feeding through to lower imported inflation, as noted in recent domestic commentary.
Broader CEE economies remain exposed to energy-price volatility despite the sharp Brent drop, given high import dependence. Russia’s planned 2027 federal deficit of RUB5.5tn underscores regional growth headwinds that could spill into neighboring trade partners.