Emerging Europe Macro Daily(Beta Mode)
Polish CPI Preview, BIST Falls as Forint Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
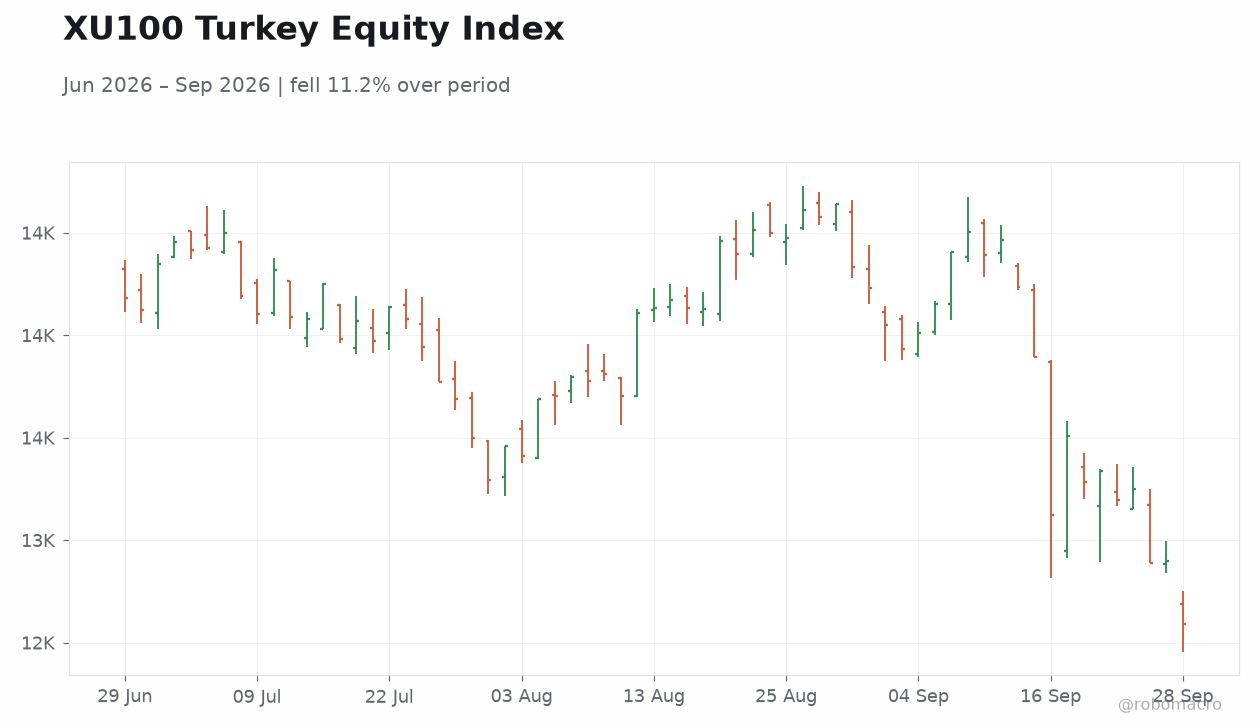
| BIST 100 | 12,592.80 | -2.38% |
| iShares Poland | 44.85 | +0.29% |
| EUR/PLN | 4.37 | +0.04% |
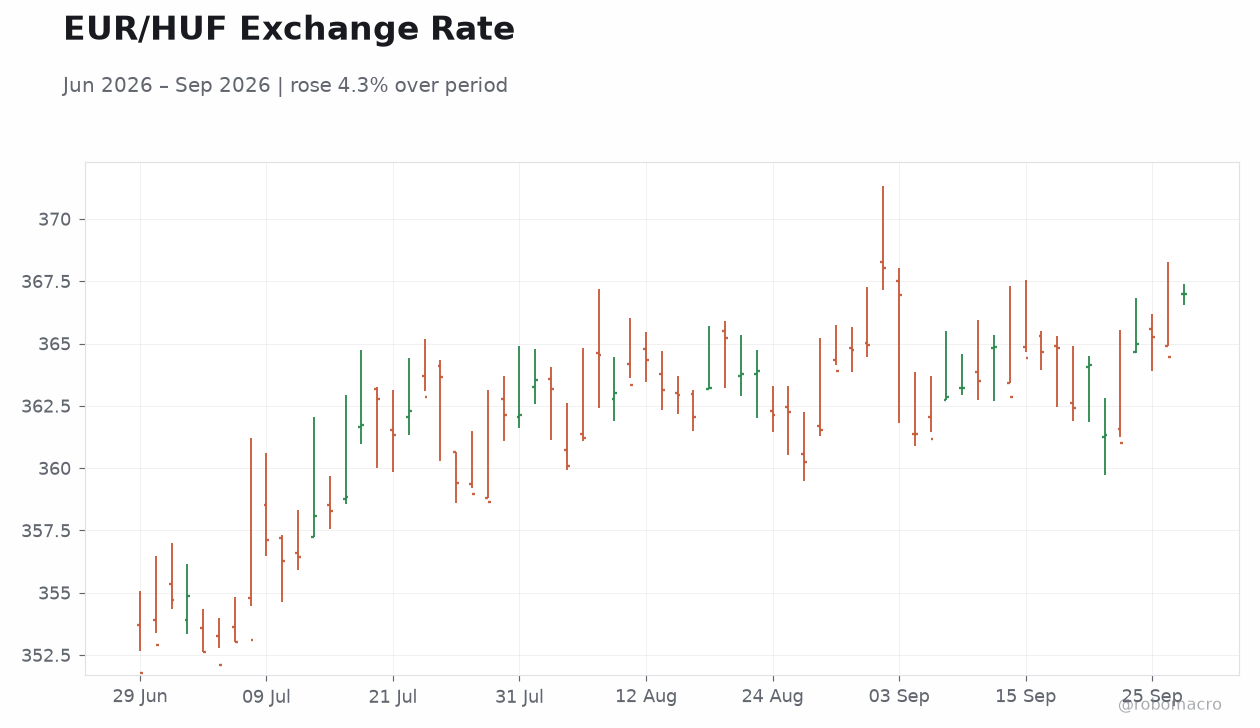
| EUR/HUF | 367.05 | +0.71% |
| EUR/CZK | 24.39 | +0.12% |
| USD/TRY | 48.99 | +0.03% |
| Brent Crude | 99.81 | -5.20% |
| Gold | 4,159.50 | -0.21% |
| Bitcoin | 83,226.98 | -1.46% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
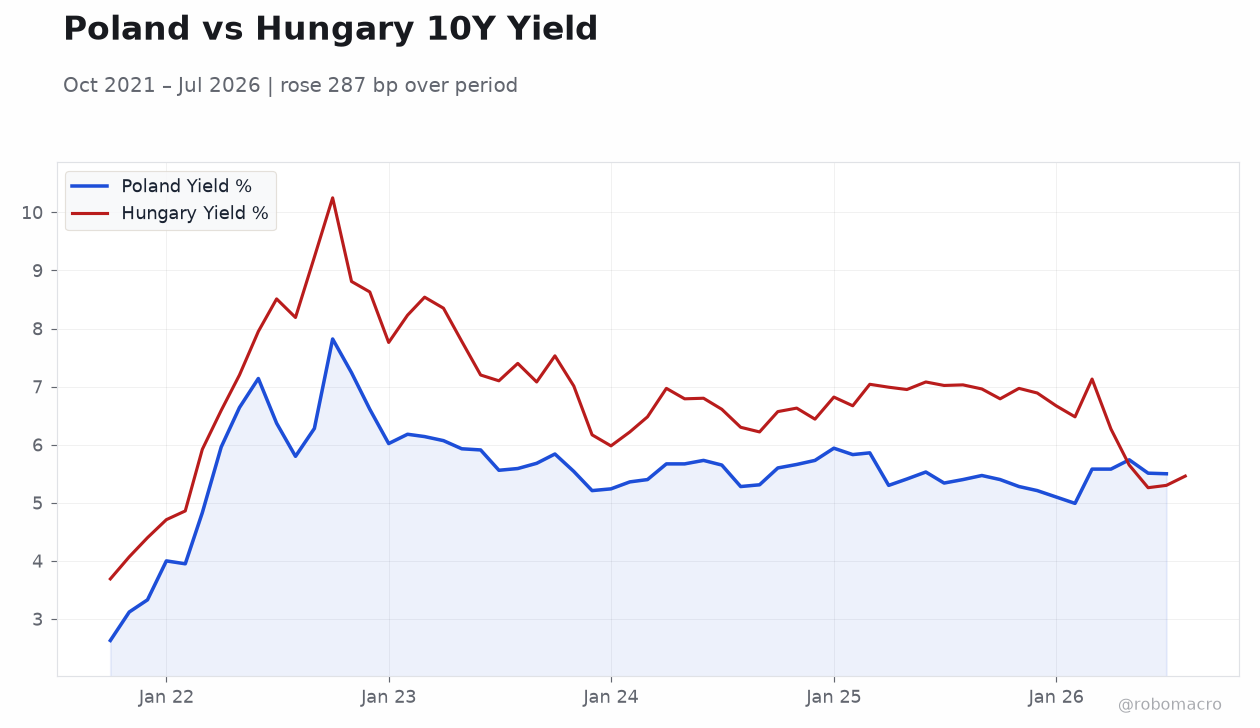
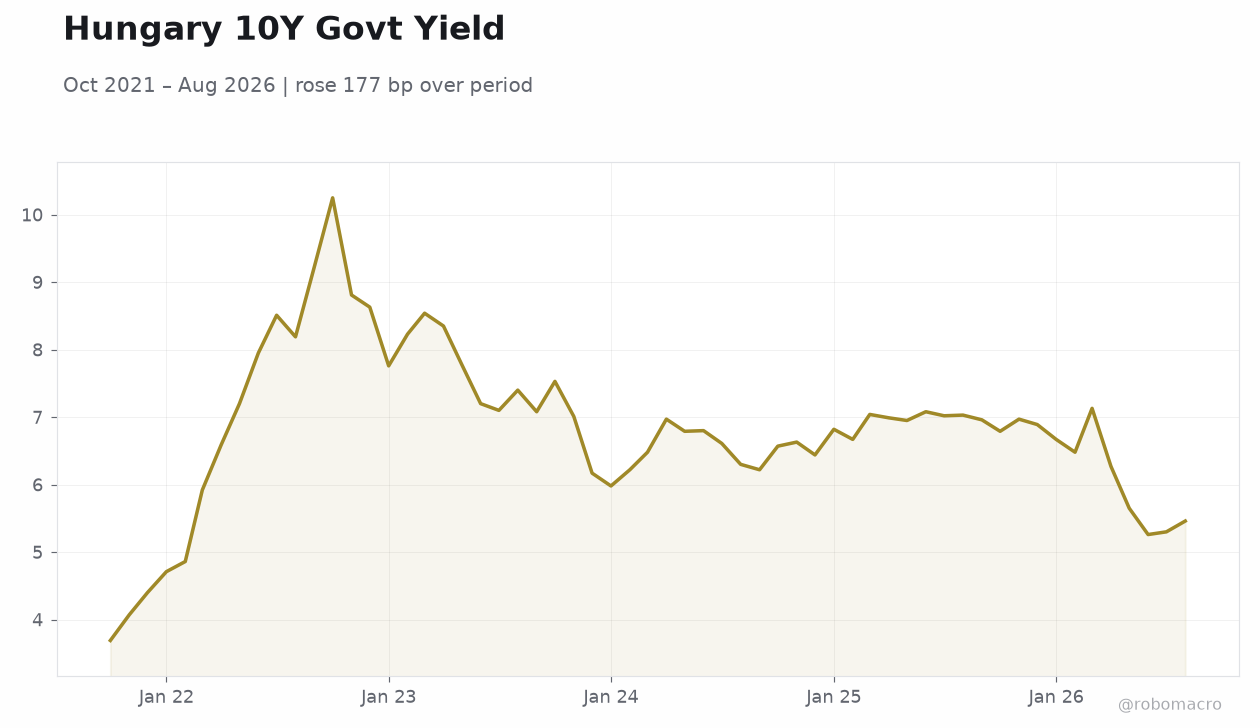 Hungary 10Y Govt Yield | Type: macro_line | Yield %: 5.46 (2026-08-01) | Range: 3.69–10.25 | Trend(6pt): 3.69,8.63,6.22,6.99,5.26,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Balance of Trade Final | -7,340m | -5,240m | 23:00 |
| Headline Unemployment Rate | 8.10 | - | 23:00 |
| Inflation Rate Year-over-Year Preliminary | 3.40 | 3.60 | 23:30 |
- Poland's preliminary inflation due at 3.6% consensus; Fitch lifts 2027 GDP forecast to 3.0%
- Turkey releases final trade balance and unemployment rate amid lira stability
- BIST 100 drops 2.38%, EUR/HUF rises 0.71% while Brent crude falls 5.20%
Yesterday's Recap
Equity and FX markets in Emerging Europe closed mixed amid thin data. The BIST 100 fell 2.38% to 12,592.80 while iShares Poland gained 0.29%. The forint weakened most sharply, with EUR/HUF rising 0.71% to 367.05.
EUR/PLN edged 0.04% higher to 4.37 and EUR/CZK added 0.12% to 24.39. USD/TRY ticked up 0.03% to 48.99. Brent crude's 5.20% drop to 99.81 weighed on regional sentiment.
Fitch upgraded its Poland 2027 GDP growth forecast to 3.0% from 2.9%, noting the slowdown from 3.5% expected this year as investment momentum fades. No macro releases occurred across the five markets.
The Day Ahead
Attention centers on three medium-impact releases scheduled for late today. Turkey will publish its final trade balance, with consensus pointing to a narrower deficit of 5.24 billion USD versus the prior 7.34 billion. Headline unemployment data for Turkey are also due, following the previous 8.1% print.
Poland's preliminary inflation rate YoY is expected at 3.6%, up from 3.4% last month; the outcome will shape near-term NBP policy expectations. No central-bank meetings, EU summits or sovereign bond auctions are listed. Markets will parse any surprises for signals on domestic demand and external balances.
Other Economic Notes
Poland remains the largest CEE economy and continues to attract attention for its growth trajectory despite the projected moderation. Fitch's modest upward revision underscores resilience in consumption even as investment slows. Turkey's structurally higher inflation and distinct policy framework keep its data releases under separate scrutiny from the EU members.
Energy import dependence continues to link the four EU members to euro-area conditions. Broader EU fund flows and rule-of-law developments have not featured in recent headlines.
Global Macro News
Eurozone CPI stood at 3.20% YoY as of August while unemployment held at 6.40% in July, keeping the ECB deposit rate at 2.50%. These benchmarks influence CNB and MNB thinking more directly than NBP or BNR given their historical responsiveness. ↓ p.2