Emerging Europe Macro Daily(Beta Mode)
Poland CPI Overshoots, Turkey Trade Narrows
Market Snapshot
| Asset | Level | Change |
|---|---|---|
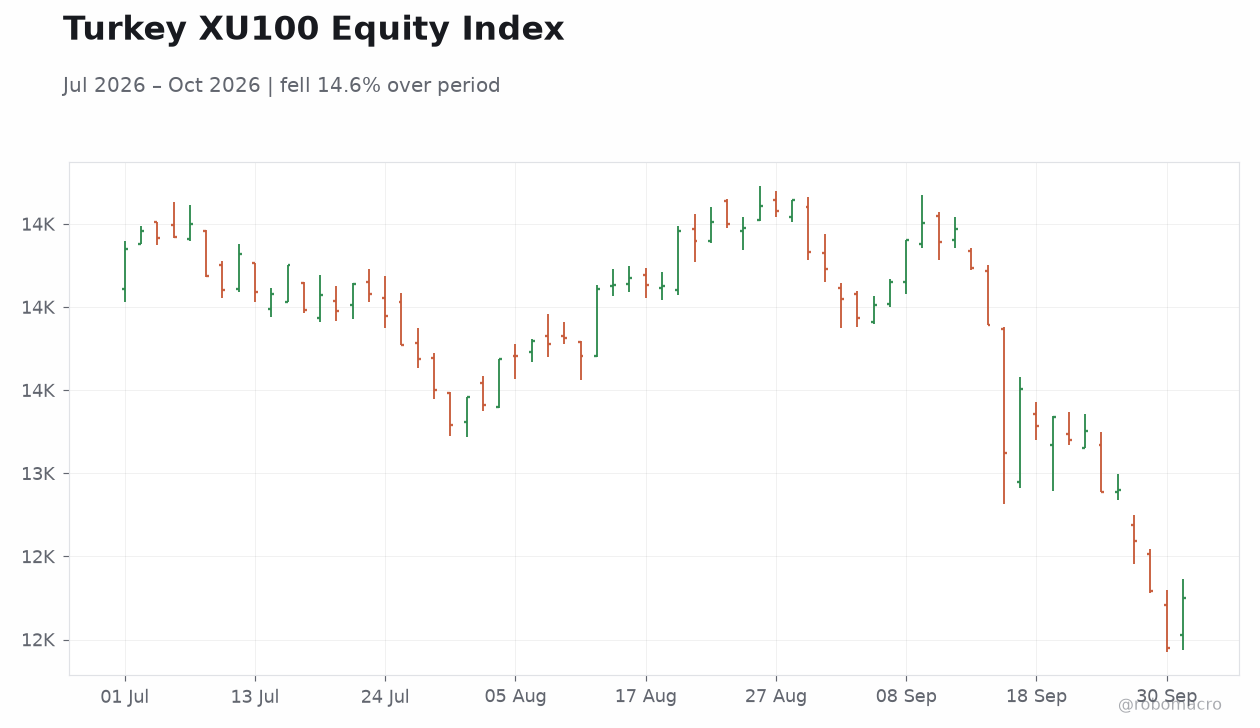
| BIST 100 | 12,249.00 | +2.53% |
| iShares Poland | 43.47 | -1.92% |
| EUR/PLN | 4.37 | +0.29% |
| EUR/HUF | 368.17 | +0.50% |
| EUR/CZK | 24.45 | +0.17% |
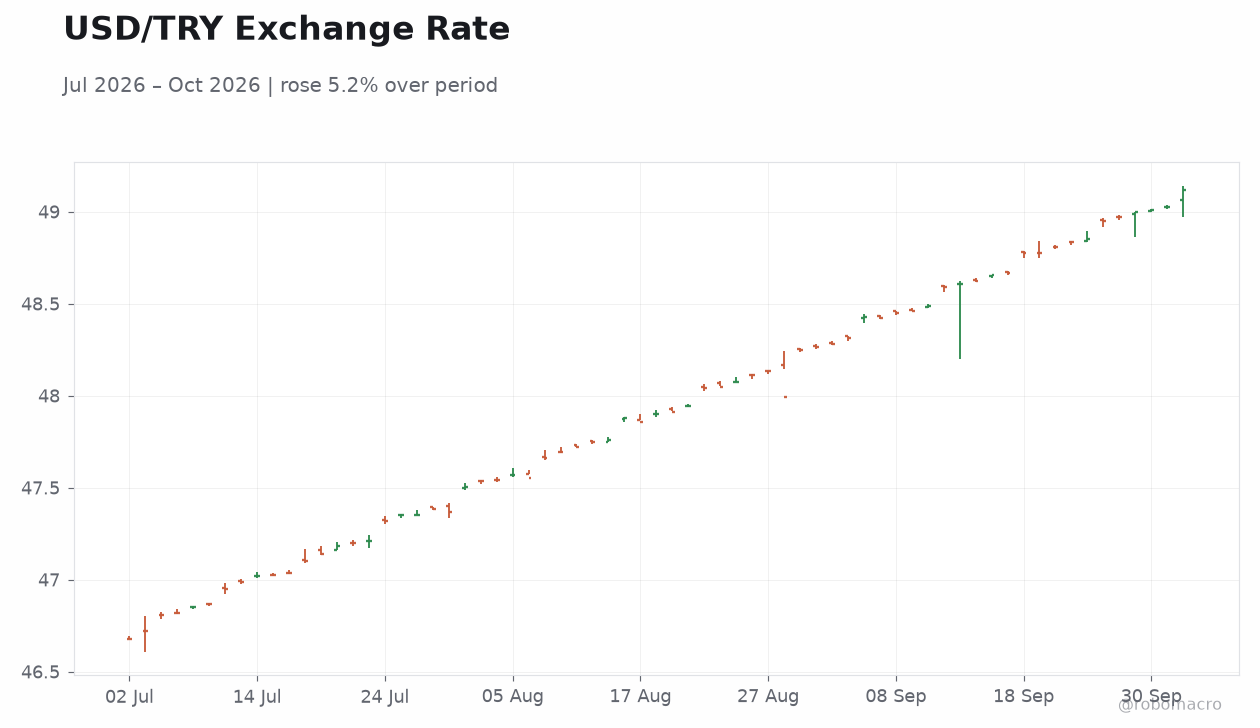
| USD/TRY | 49.12 | +0.18% |
| Brent Crude | 102.09 | -0.22% |
| Gold | 4,215.30 | +0.31% |
| Bitcoin | 86,558.56 | +3.60% |
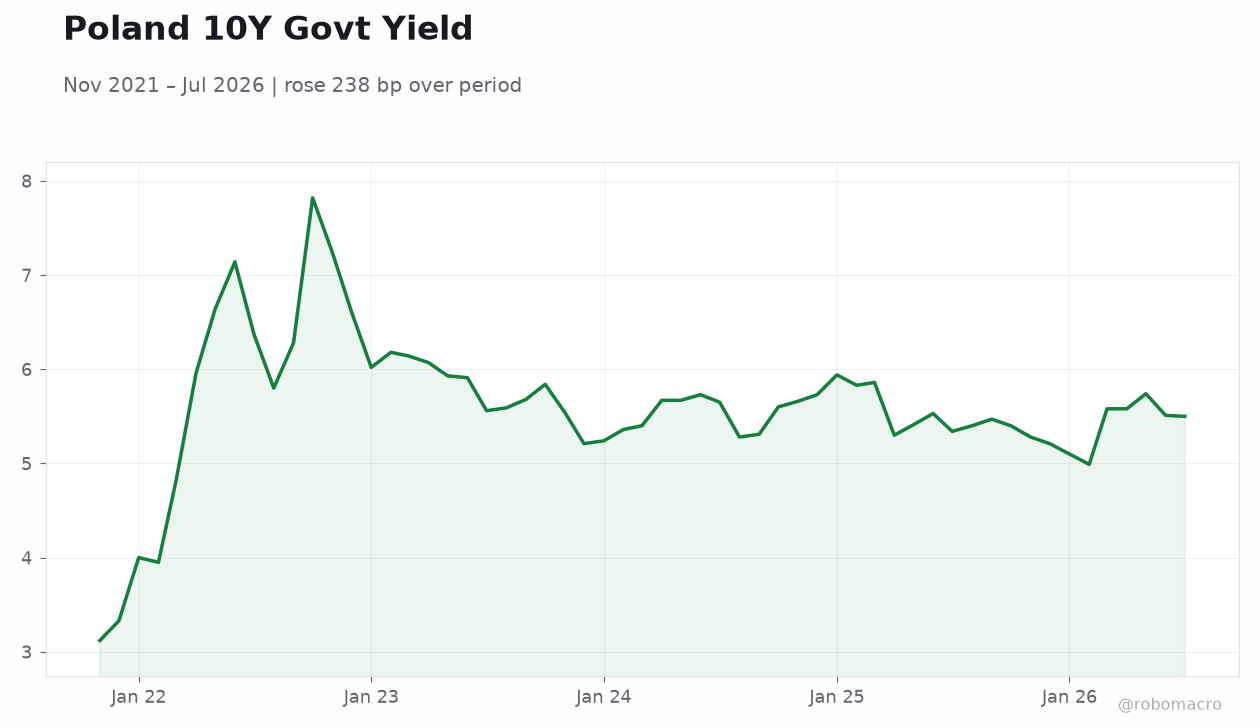
| Poland 10Y Govt Yield | - | - |
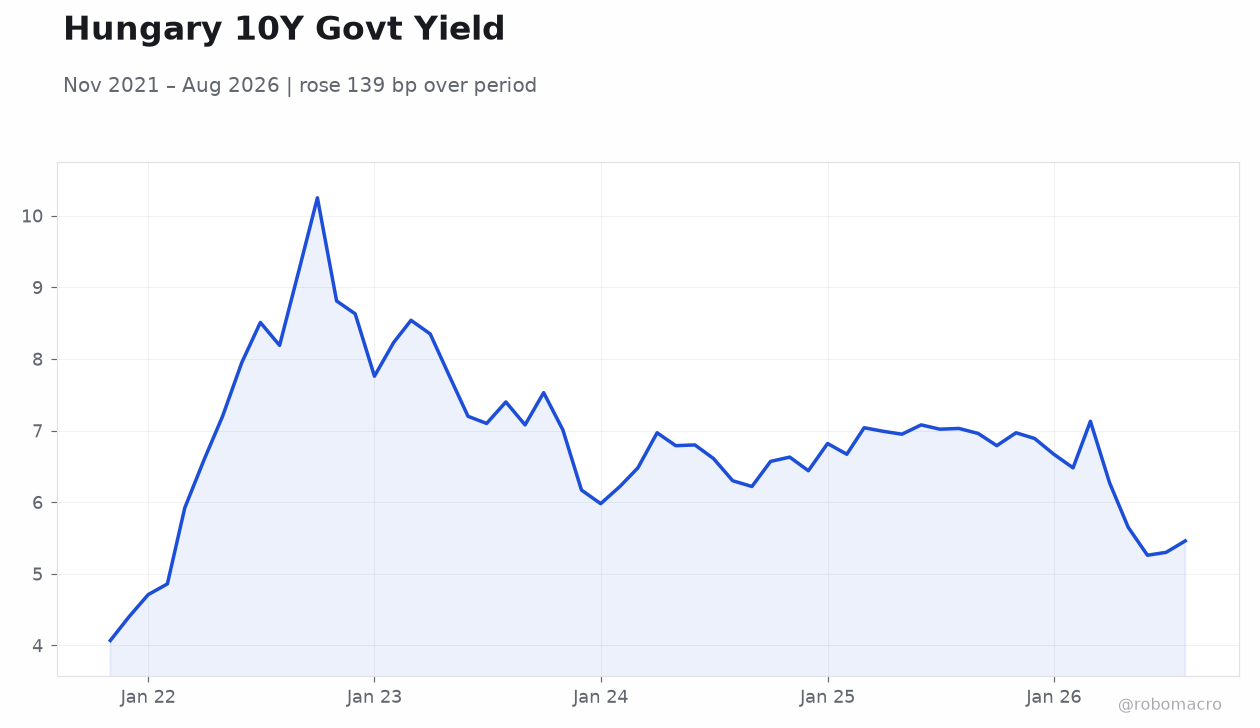
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Balance of Trade Final | -7,340m | -5,240m | -5,240m |
| Headline Unemployment Rate | 8.10 | - | 7.80 |
| Inflation Rate Year-over-Year Preliminary | 3.40 | 4.10 | 4 |
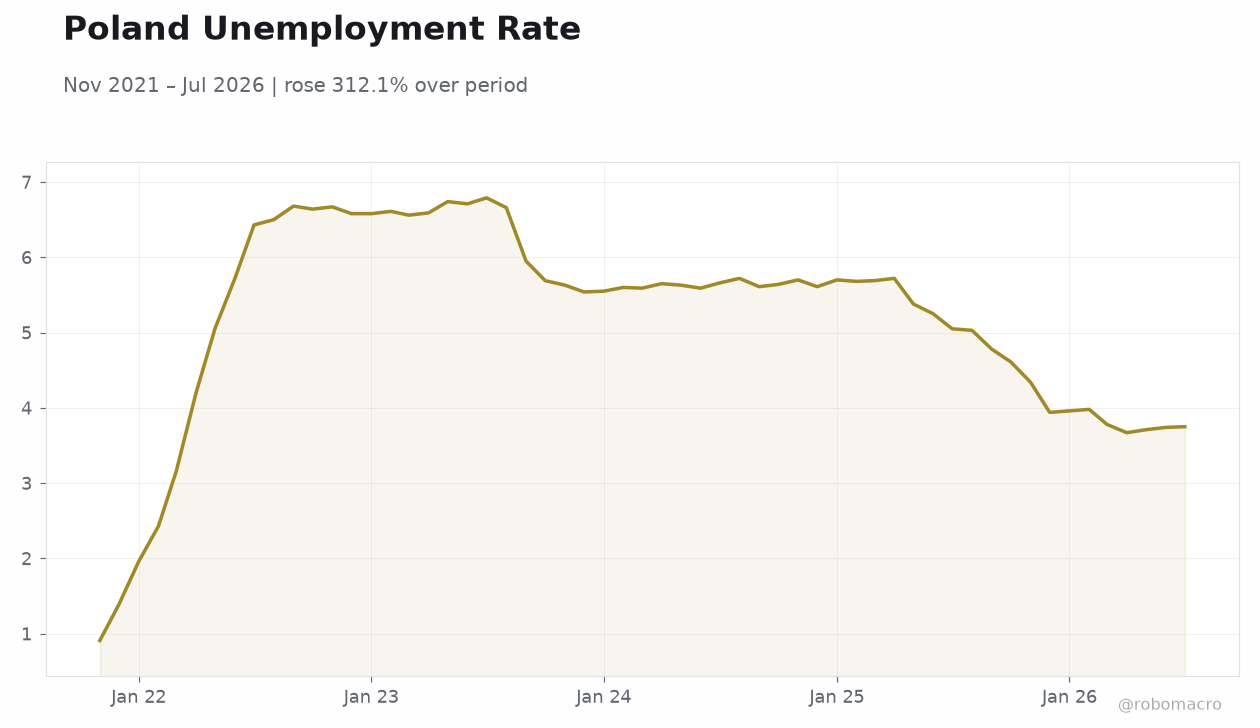 Poland Unemployment Rate | Type: macro_line | Unemployment %: 3.75 (2026-07-01) | Range: 0.91–6.79 | Trend(5pt): 0.91,6.58,5.59,5.38,3.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Poland’s preliminary September CPI rose 4.0% y/y, beating the prior 3.4% print and keeping NBP alert.
- Turkey’s trade deficit narrowed to $5.24 bn and unemployment fell to 7.8%, aligning with consensus.
- BIST 100 gained 2.53% while Polish equities fell 1.92% and regional currencies weakened versus the euro.
Yesterday's Recap
Poland’s September inflation print of 4.0% y/y exceeded the previous reading and came in just below the 4.1% consensus, reflecting persistent price pressures that could delay any NBP easing. Turkey reported a trade balance of –$5.24 bn, matching forecasts and narrower than the prior –$7.34 bn, while the unemployment rate declined to 7.8% from 8.1%, pointing to modest labour-market stabilisation under CBRT policy. Equity markets diverged sharply, with the BIST 100 climbing 2.53% to 12,249 while the iShares Poland ETF dropped 1.92% to 43.47.
Regional currencies posted modest losses against the euro, with EUR/PLN rising 0.29% to 4.37, EUR/HUF advancing 0.50% to 368.17 and EUR/CZK up 0.17% to 24.45. USD/TRY edged 0.18% higher to 49.12 amid continued lira pressure. Brent crude slipped 0.22% to 102.09 while gold rose 0.31% to 4,215.30 and Bitcoin surged 3.60%.
Polish officials highlighted plans to expand defence exports to India and confirmed a 100-company delegation will accompany Prime Minister Tusk to New Delhi in late October.
The Day Ahead
No macroeconomic releases, central-bank meetings or sovereign auctions are scheduled for 2–3 October across Poland, Czech Republic, Hungary, Romania or Turkey. Markets will therefore focus on incoming PMI surveys and any follow-up comments from Polish officials on defence-industry cooperation with India. Regional investors may also monitor euro-area data for spill-overs given the five economies’ trade linkages.
Turkish corporates could provide updates on external financing after yesterday’s trade and labour figures. With calendars empty, attention is likely to shift to technical levels in EUR/PLN and USD/TRY.
Other Economic Notes
Poland continues to draw investor attention with EU-leading growth prospects and its push for a permanent G20 seat, though talks are described as complex. The Pegasus acquisition of Czech Airlines and Smartwings marks the first international expansion for the Turkish carrier and deepens aviation ties between Istanbul and Prague. CEE manufacturers appear to be weathering higher costs, with recent PMI readings showing a milder downturn in Poland and neighbouring economies.
Energy-import dependence remains a shared vulnerability for the EU members, while Turkey’s structurally higher inflation continues to set it apart from the rest of the region.