Emerging Europe Macro Daily(Beta Mode)
BIST Edges Up, PLN Weakens on Quiet Day
Market Snapshot
| Asset | Level | Change |
|---|---|---|
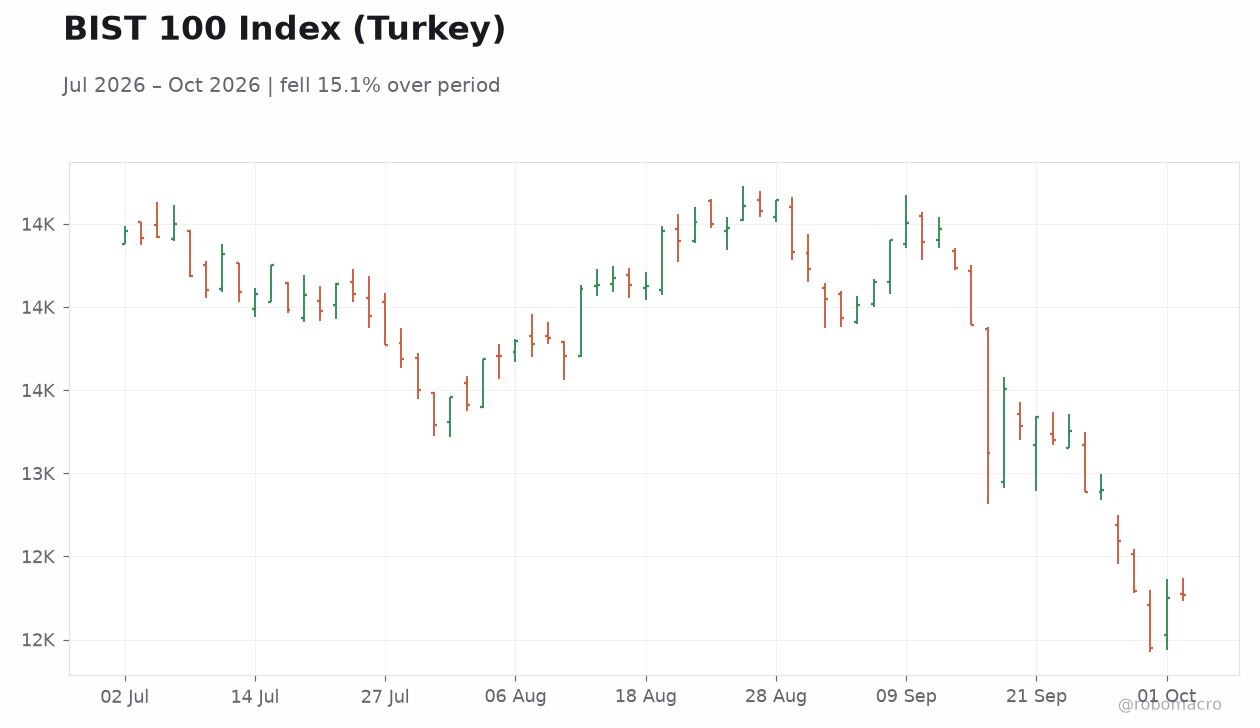
| BIST 100 | 12,270.20 | +0.17% |
| iShares Poland | 43.03 | -0.51% |
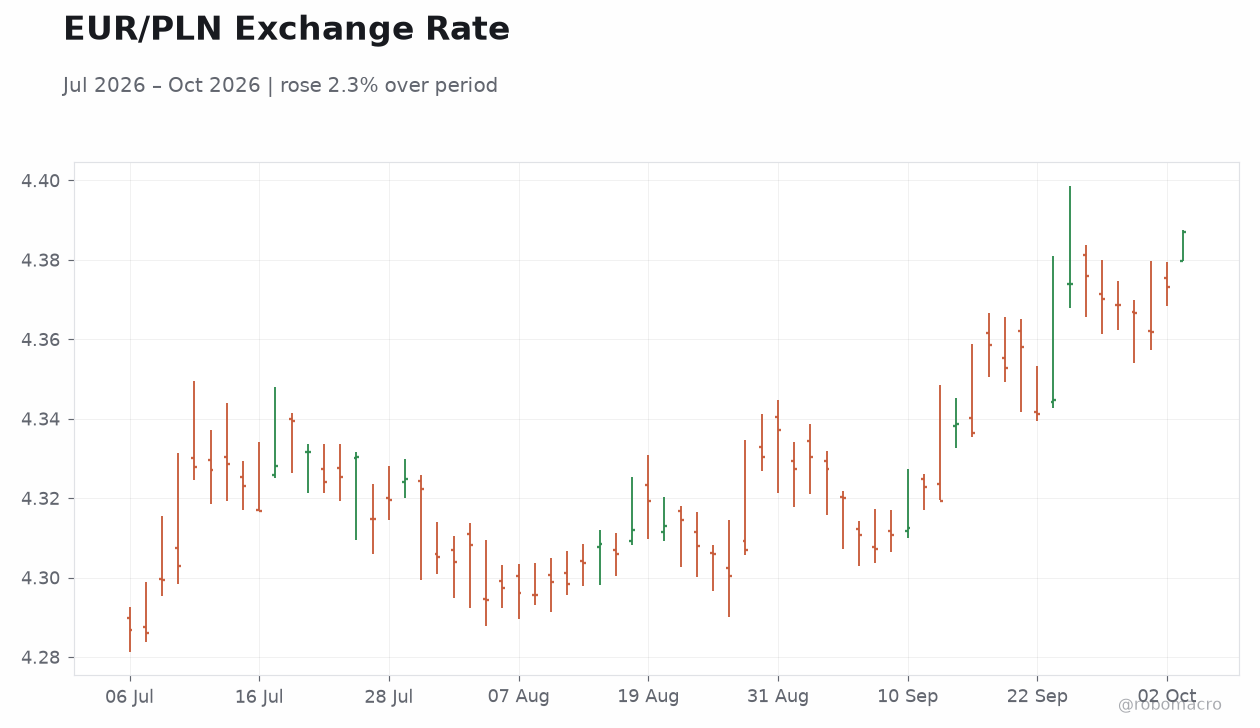
| EUR/PLN | 4.37 | +0.26% |
| EUR/HUF | 368.13 | +0.13% |
| EUR/CZK | 24.42 | -0.12% |
| USD/TRY | 49.12 | +0.18% |
| Brent Crude | 101.68 | -0.56% |
| Gold | 4,159.70 | -0.06% |
| Bitcoin | 85,545.28 | +0.92% |
| Poland 10Y Govt Yield | - | - |
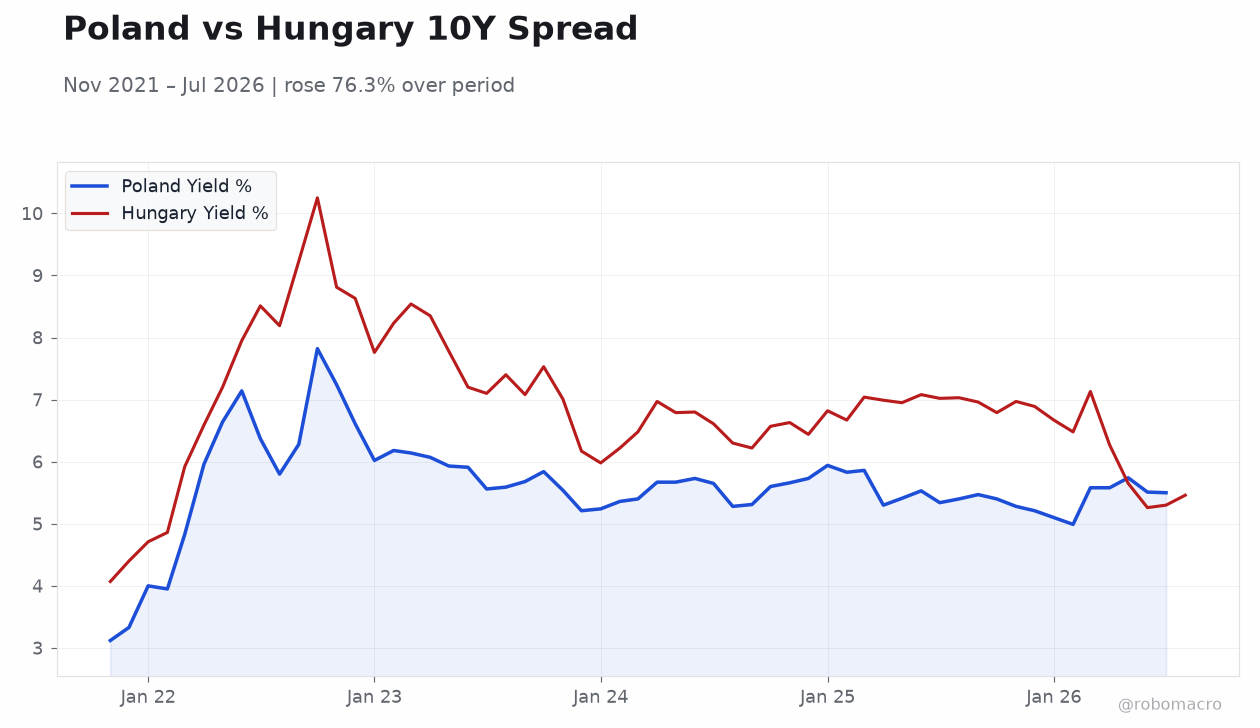
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
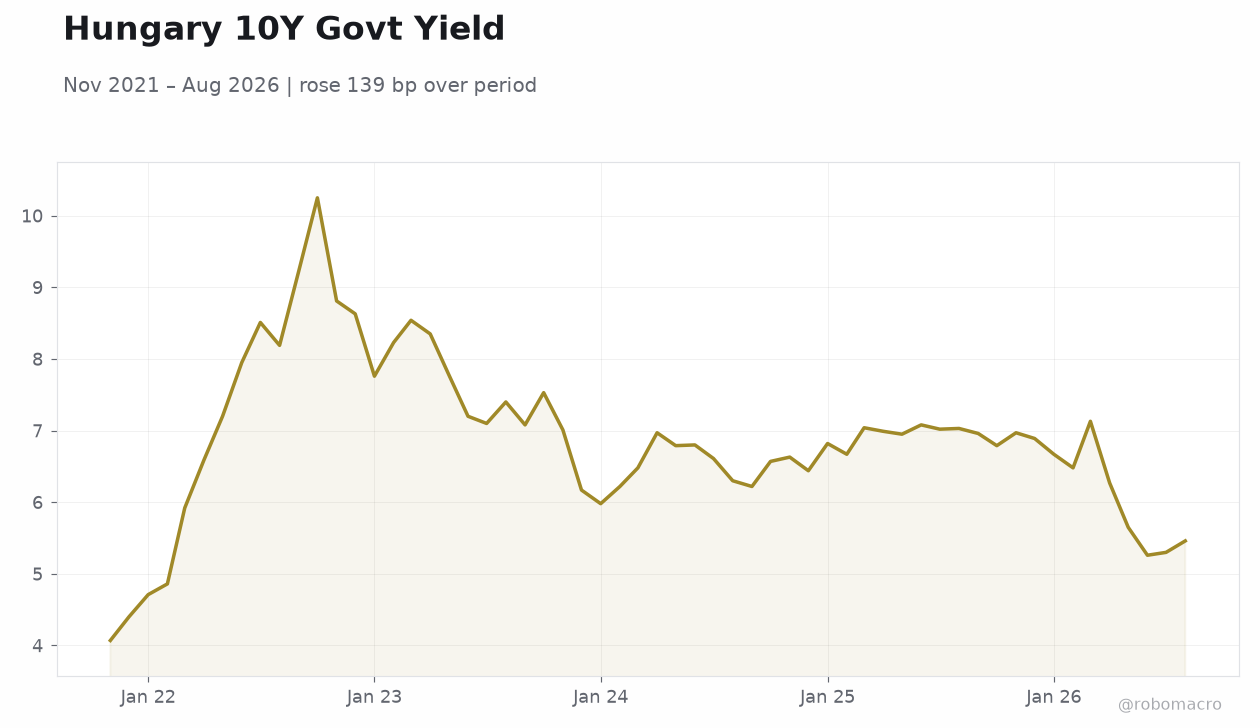 Hungary 10Y Govt Yield | Type: macro_line | Yield %: 5.46 (2026-08-01) | Range: 4.07–10.25 | Trend(6pt): 4.07,7.76,6.48,6.95,5.3,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- BIST 100 advanced 0.17% to 12,270.20 while iShares Poland fell 0.51% to 43.03.
- EUR/PLN rose 0.26% to 4.37 and USD/TRY gained 0.18% to 49.12 with no regional data prints.
- Brent crude slipped 0.56% to 101.68 as Bitcoin climbed 0.92% to 85,545.28.
Yesterday's Recap
Markets in Emerging Europe moved on thin volumes with no economic releases across Poland, Czech Republic, Hungary, Romania or Turkey. The BIST 100 posted a modest gain while the Polish equity ETF declined, reflecting limited domestic catalysts. EUR/PLN strengthened as the zloty softened 0.26% and EUR/HUF edged 0.13% higher, consistent with subdued regional risk appetite.
EUR/CZK eased 0.12%. USD/TRY rose 0.18% amid ongoing lira pressure. Poland’s new fuel price cap took effect at gas stations, providing a modest buffer for households but offering no immediate inflation print.
Reports indicated most Ukrainians intend to remain in Poland long-term, supporting labour supply in the largest CEE economy. Brent crude and gold both declined modestly, leaving Turkish and Polish assets as the main focus in an otherwise empty data calendar. Poland and Hungary 10-year government yields were not reported.
The Day Ahead
The calendar remains empty for 5–6 October with zero scheduled releases or central-bank meetings in any of the five countries. Traders will monitor external drivers including euro-area bond yields and any follow-through from the weak US payrolls print. Poland’s fuel-price cap may generate minor commentary on near-term CPI effects, though no official data are due.
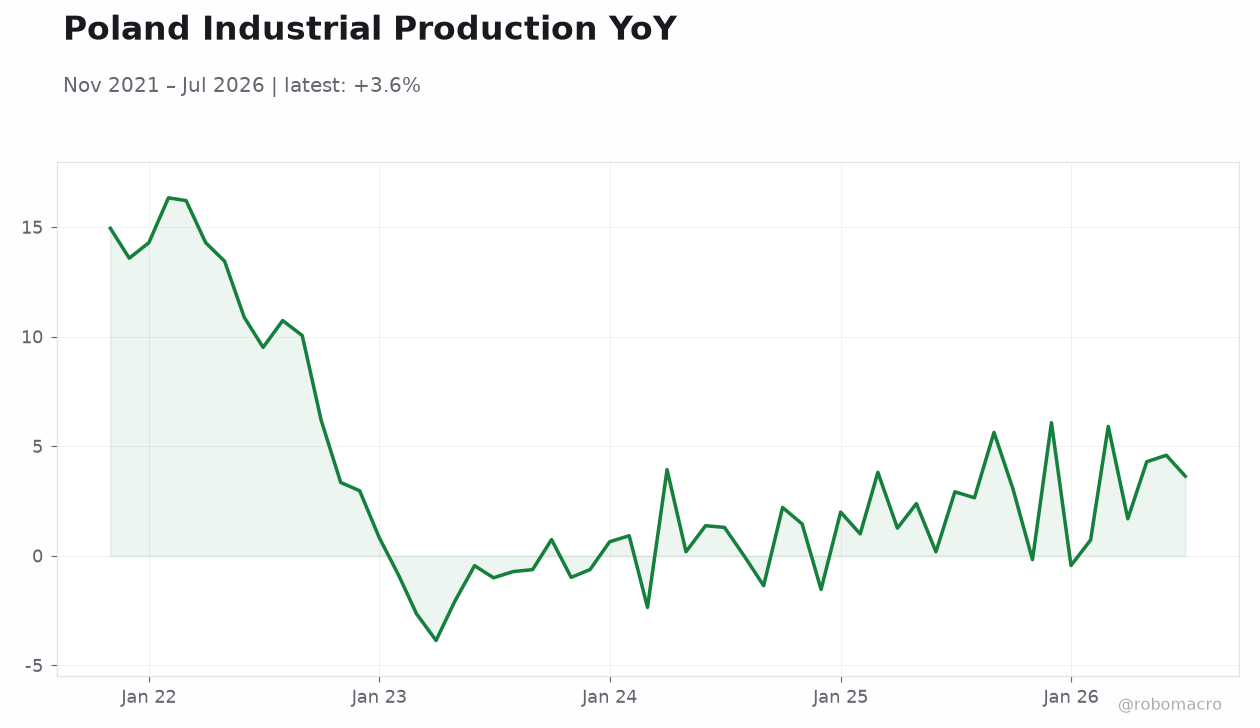
Hungary and the Czech Republic stay in focus for any ECB-aligned signals given their typical responsiveness to euro-area policy shifts. Romania and Turkey face quiet sessions with attention likely turning to FX reserve management and external financing conditions. Overall activity is expected to stay light until the next batch of inflation or industrial production figures appears later in the month.
Other Economic Notes
Poland’s labour market continues to absorb Ukrainian inflows, supporting potential output without immediate wage-pressure signals. Energy import dependence remains a shared vulnerability for the EU members, with Brent at 101.68 underscoring the cost of any supply disruption. Turkey’s distinct inflation dynamics and political constraints on the CBRT continue to set it apart from the convergence-focused policies in Poland, Czech Republic, Hungary and Romania.
EU fund flows and rule-of-law discussions stay relevant for the four member states, though no fresh disbursements were reported. ↓ p.2