Emerging Europe Macro Daily(Beta Mode)
MNB Hold Eyed as Forint, Budget in Focus
Market Snapshot
| Asset | Level | Change |
|---|---|---|
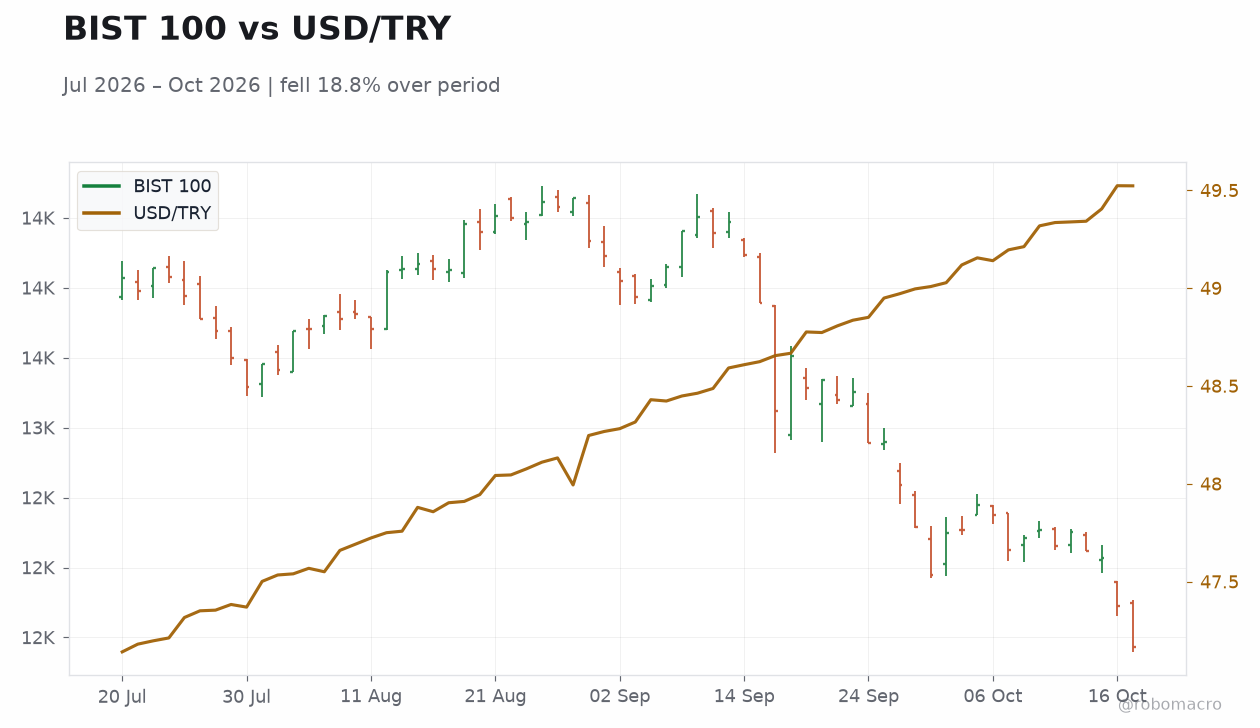
| BIST 100 | 11,430.10 | -2.49% |
| iShares Poland | 44.56 | +0.25% |
| EUR/PLN | 4.37 | +0.03% |
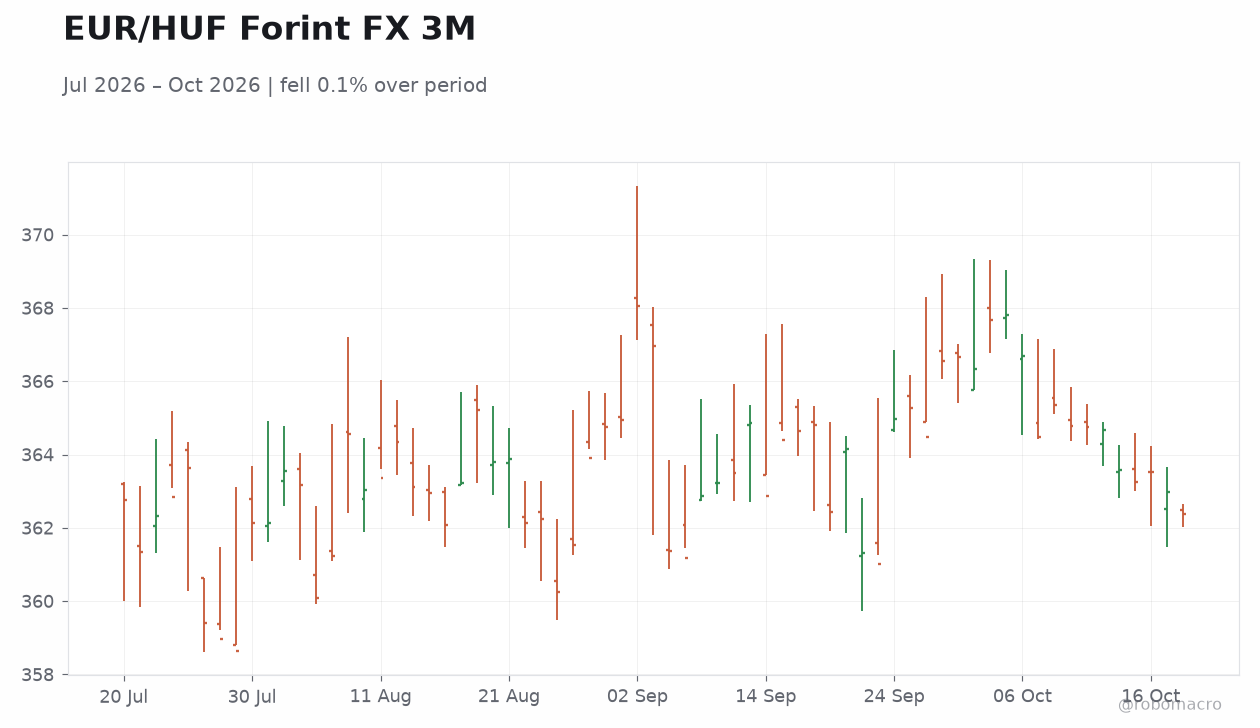
| EUR/HUF | 362.97 | -0.15% |
| EUR/CZK | 24.32 | +0.04% |
| USD/TRY | 49.57 | +0.09% |
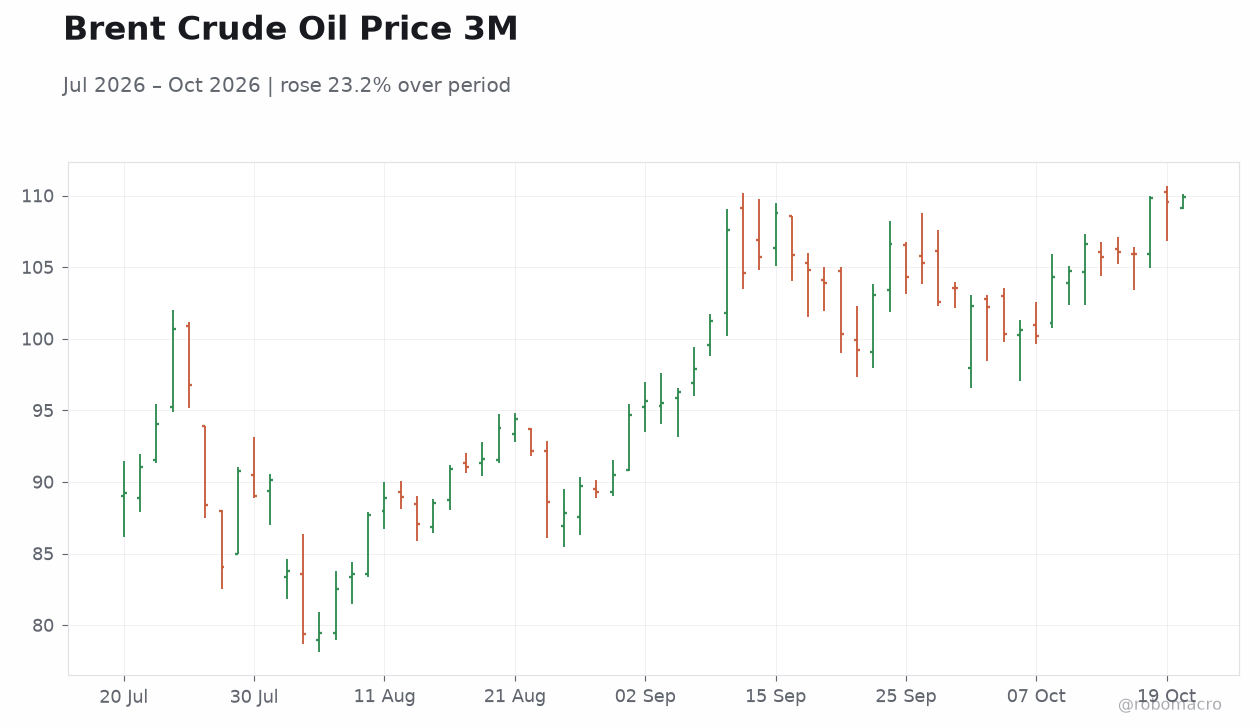
| Brent Crude | 109.96 | +0.37% |
| Gold | 4,162.80 | +0.06% |
| Bitcoin | 81,950.24 | -0.08% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
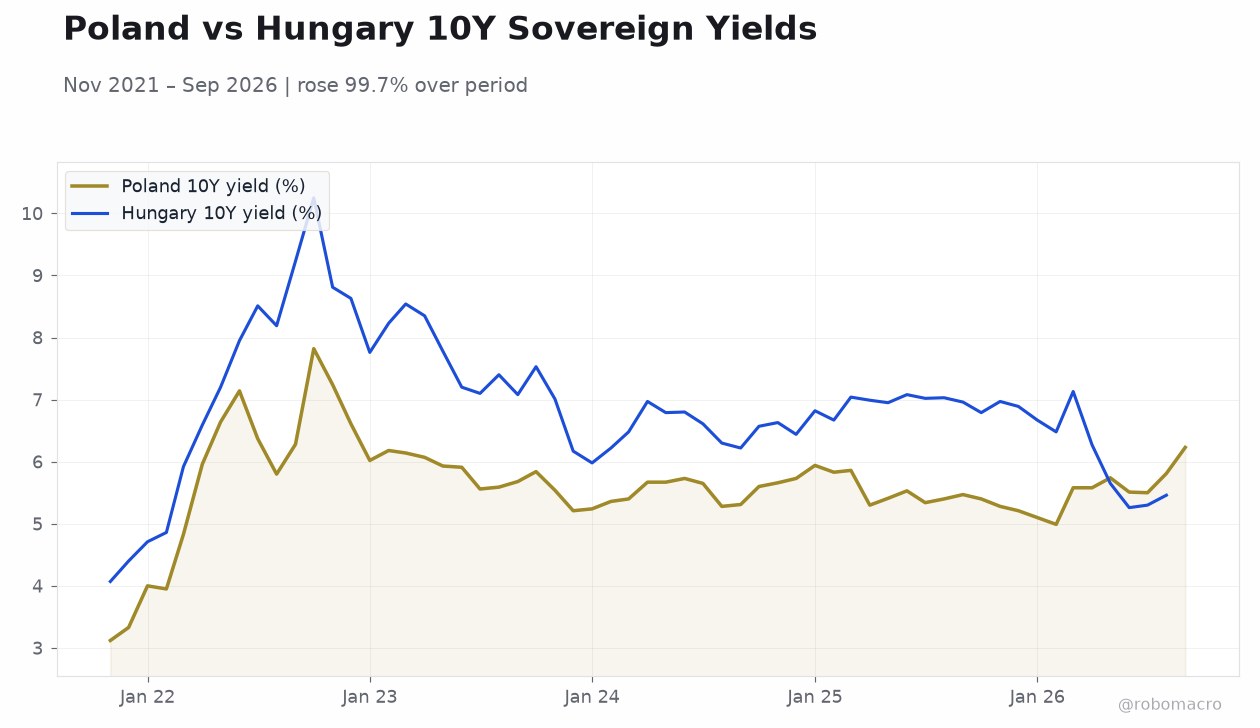 Poland vs Hungary 10Y Sovereign Yields | Type: macro_line | Poland 10Y yield (%): 6.23 (2026-09-01) | Range: 3.12–7.82 | Trend(6pt): 3.12,6.02,5.4,5.41,5.5,6.23 | Hungary 10Y yield (%): 5.46 (2026-08-01) | Range: 4.07–10.25 | Trend(6pt): 4.07,7.76,6.48,6.95,5.3,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 5.50 | 5.50 | 08:00 |
- MNB expected to hold the base rate at 5.5% for a second month as Prime Minister Magyar's 2027 budget plan frames the policy outlook.
- Forint firmed to 362.97 per euro; Polish MPC member flags zloty weakness as a possible rate-hike trigger.
- BIST 100 fell 2.49% while regional FX stayed range-bound; Brent near $110 keeps energy-import inflation risk live.
Yesterday's Recap
Hungary dominated the regional narrative on 19 October, with the forint strengthening to 362.97 per euro (-0.15% on the day) as markets positioned for the MNB's Tuesday decision and digested Prime Minister Peter Magyar's presentation of the 2027 budget plan to parliament. The MNB is widely expected to leave its base rate at 5.5% for a second consecutive month, with Portfolio.hu framing the stance as a deliberate wait-and-see while the government's fiscal plans are fully unveiled. In Poland, EUR/PLN held at 4.37 (+0.03%) and iShares Poland edged up 0.25%, but the standout signal came from a Monetary Policy Council member who told Bloomberg that further zloty weakening is among the triggers that could tip policymakers toward raising rates — a hawkish marker for a council that has otherwise been on hold.
Turkey was the clear underperformer: the BIST 100 dropped 2.49% to 11,430.10 and USD/TRY crept to 49.57 (+0.09%), extending the lira's slow grind weaker. Czech and Romanian markets were quiet, with EUR/CZK at 24.32 (+0.04%) and no major data prints across the region. Brent crude at $109.96 (+0.37%) and gold at $4,162.80 kept the imported-inflation backdrop uncomfortable for the CEE-4, all of which remain energy-import dependent.
The Day Ahead
The single high-impact event on the regional calendar is the MNB's central bank interest rate decision at 08:00 ET, with consensus at 5.5% and the previous setting also 5.5% — a hold that would mark the second straight month of unchanged policy. The accompanying statement and any forward guidance will matter more than the decision itself: markets will parse whether the MNB signals a prolonged pause tied to the budget rollout or retains a tightening bias should the forint come under pressure. No other Emerging Europe releases are scheduled for today, leaving Polish, Czech, Romanian and Turkish markets to trade off euro-area and global risk sentiment.
With the ECB deposit rate at 2.50% and euro-area CPI at 3.80%, the MNB's real-rate premium remains substantial, and any dovish tilt would likely test the forint's recent firmness.
Other Economic Notes
The region's shared vulnerability remains energy: Brent near $110 sustains cost-push pressure across the CEE-4, where import dependence leaves inflation sensitive to crude and gas swings. ↓ p.2