Emerging Europe Macro Daily(Beta Mode)
Forint Slides, Turkey Data Mixed, Poland CPI Eyed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 11,165.40 | +0.13% |
| iShares Poland | 44.20 | +0.14% |
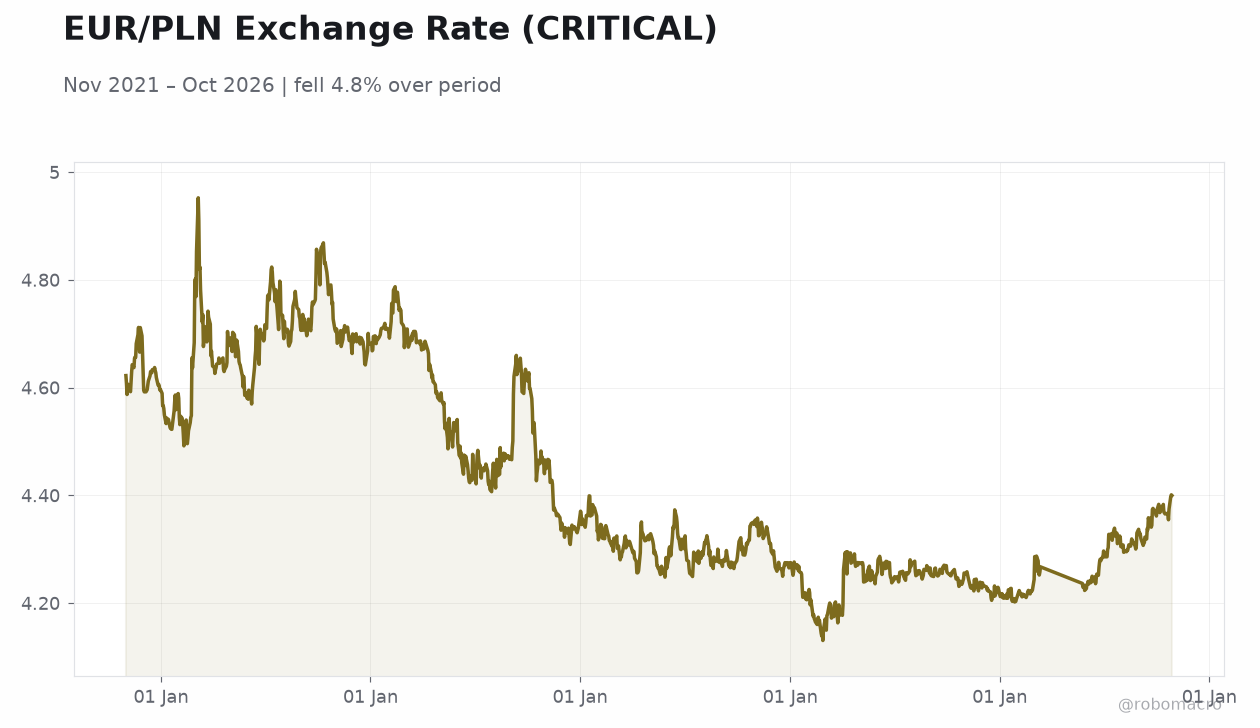
| EUR/PLN | 4.40 | +0.10% |
| EUR/HUF | 366.51 | +0.06% |
| EUR/CZK | 24.36 | +0.19% |
| USD/TRY | 49.81 | +0.02% |
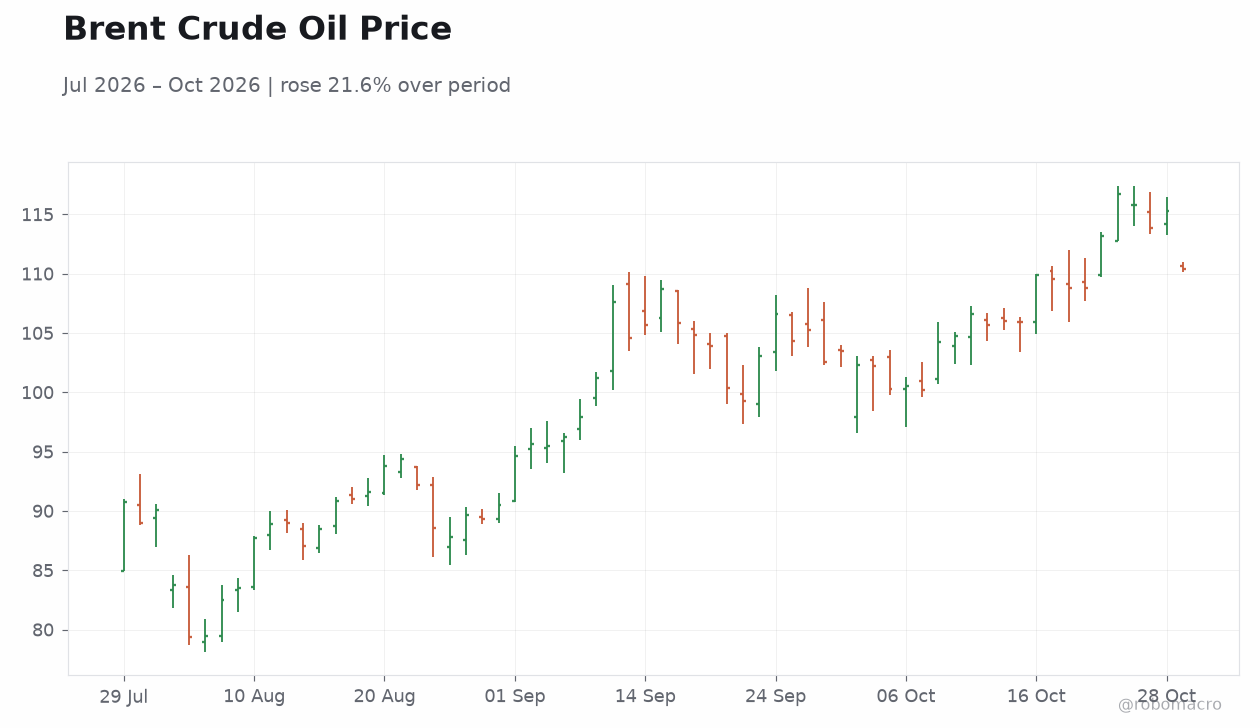
| Brent Crude | 110.31 | -4.34% |
| Gold | 4,050.30 | -0.03% |
| Bitcoin | 79,802.41 | -1.24% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
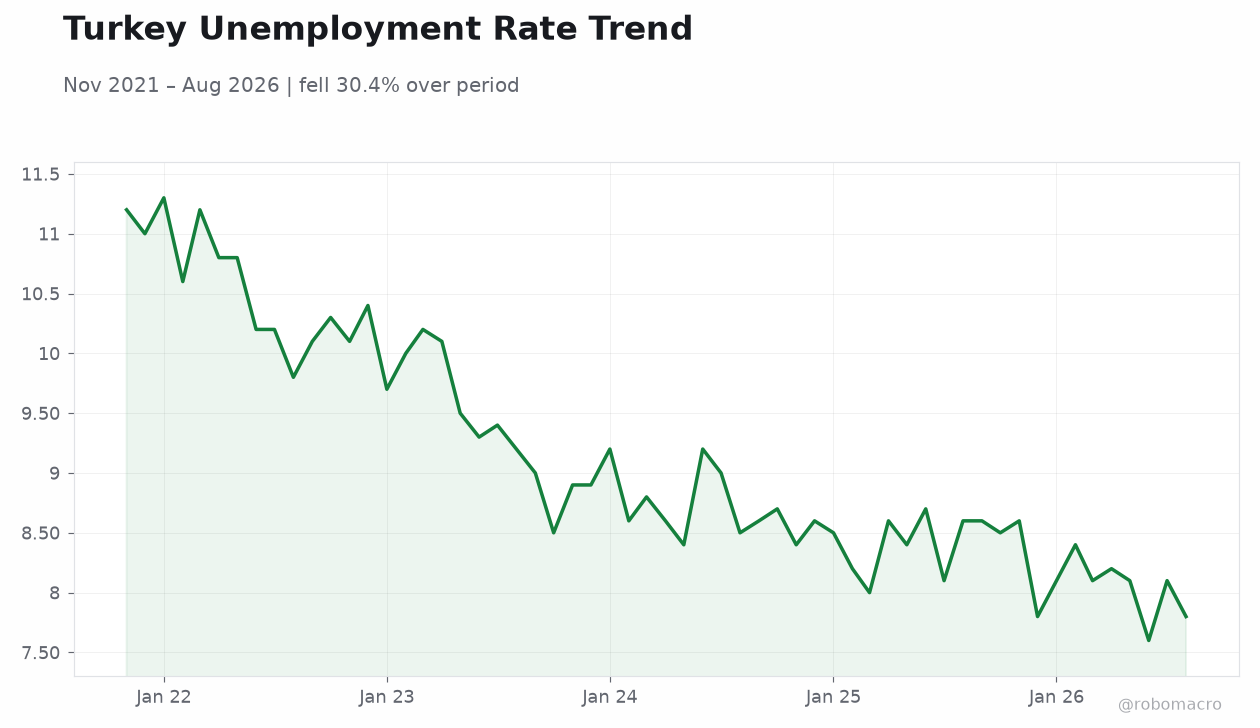
| Headline Unemployment Rate | 7.90 | - | 8.40 |
| Balance of Trade Final | -5,240m | -5,230m | -5,160m |
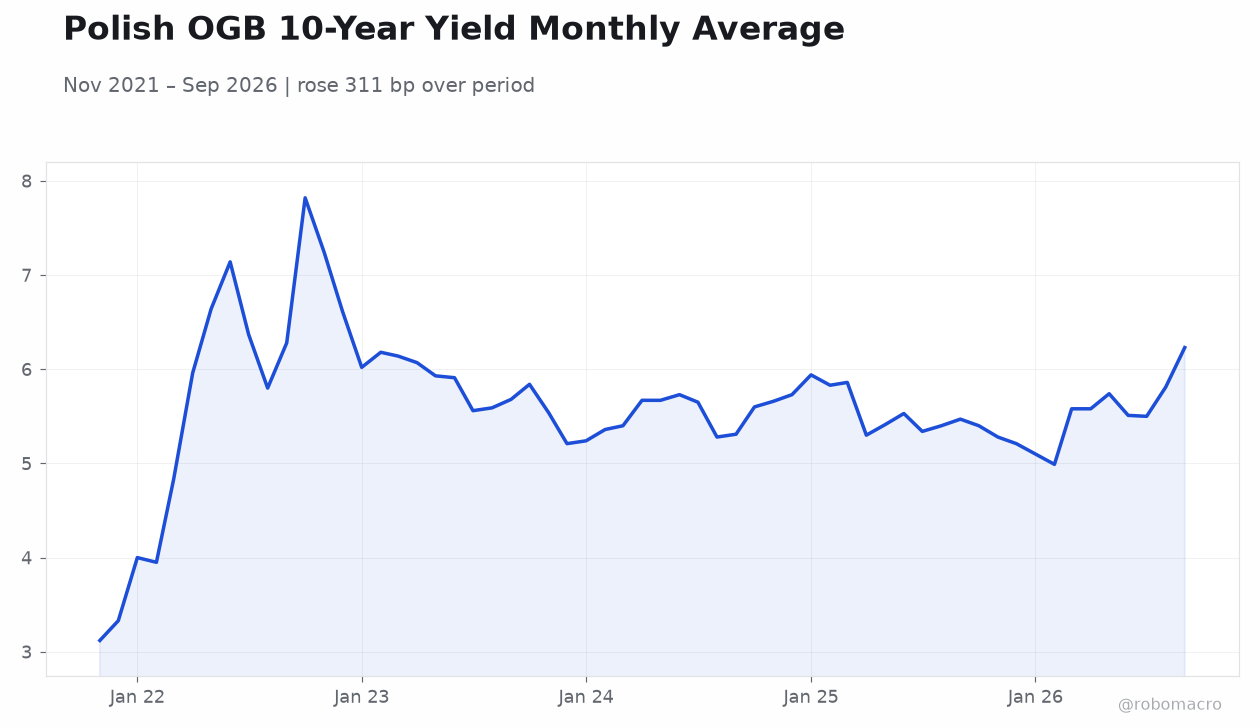
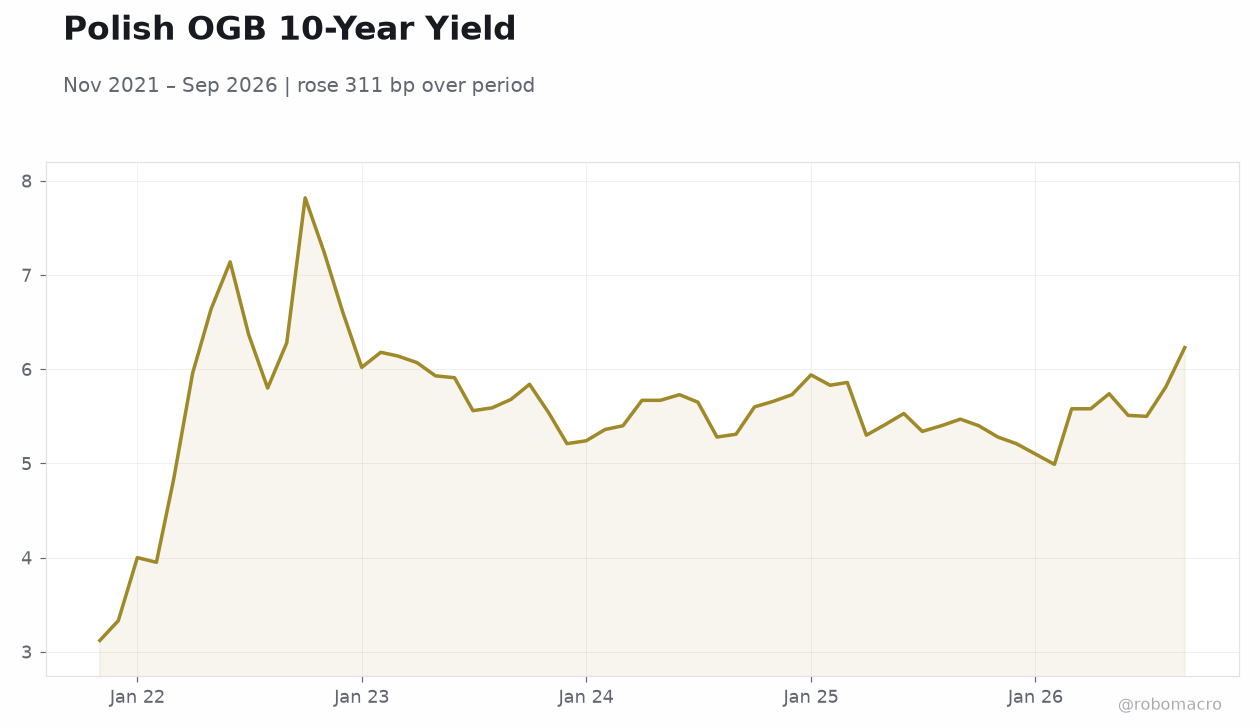 Polish OGB 10-Year Yield | Type: macro_line | Polish OGB 10-Year Yield: 6.23 (2026-09-01) | Range: 3.12–7.82 | Trend(6pt): 3.12,6.02,5.4,5.41,5.5,6.23
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Year-over-Year Preliminary | 4.10 | - | 04:30 |
| Friday (2026-10-30) | |||
| Inflation Rate Year-over-Year Preliminary | 4.10 | - | 04:30 |
- Hungarian forint under renewed pressure as USD strength tests MNB tolerance; EUR/HUF at 366.51.
- Turkey unemployment rose to 8.4% while trade deficit narrowed slightly to TRY 5.16bn.
- Poland's flash October CPI due Friday is the week's key regional print; NBP holds at 3.75%.
Yesterday's Recap
Turkey's headline unemployment rate rose to 8.4% from 7.9% previously, a notable deterioration in the labour market that complicates the CBRT's already delicate policy balancing act. The final balance of trade for Turkey printed at a deficit of TRY 5.16bn, modestly narrower than the prior TRY 5.24bn and slightly better than consensus, offering limited relief on the external accounts. Regional FX was broadly stable against the euro but the forint remains the standout weak link, with EUR/HUF at 366.51 and Hungarian press flagging the currency near lows last seen under the current government versus the dollar.
EUR/PLN edged to 4.40 and EUR/CZK to 24.36, both marginally softer for the local units. Equity markets were quiet: BIST 100 added 0.13% to 11,165.40 while iShares Poland rose 0.14%. Brent crude's 4.34% slide to $110.31 is a welcome disinflationary input for the energy-import-dependent region.
The Day Ahead
The calendar is thin, with Poland's preliminary October CPI the sole scheduled regional release, due Friday at 04:30 ET. The print follows September's 4.1% year-over-year reading and will be scrutinised for whether energy-base effects and administered-price changes are pushing inflation back toward the NBP's tolerance band. No Czech, Hungarian, Romanian or Turkish data are scheduled, leaving markets to trade off global risk sentiment and the forint's ongoing test of MNB resolve.
Liquidity may be thinner into month-end, amplifying moves in CEE currencies.
Other Economic Notes
EU gas storage has stalled at 74.9%, a record low for late October, with Austria, Slovakia and the Czech Republic already drawing down inventories — a shared vulnerability for the region's energy-intensive industrial base heading into winter. The Czech and Hungarian inflation pictures remain comparatively benign, with CPI at 2.51% and 1.54% respectively, keeping real-rate buffers intact. Romania's 6.50% policy rate remains the highest in the EU bloc, sustaining carry appeal but weighing on domestic credit.
Turkey's labour-market softening adds to the case for caution at the CBRT.