Emerging Europe Macro Daily(Beta Mode)
NBP Hold Eyed as Turkish Inflation Tops Forecasts
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 11,023.55 | +0.56% |
| iShares Poland | 43.40 | -2.95% |
| EUR/PLN | 4.41 | +0.11% |
| EUR/HUF | 364.61 | -0.07% |
| EUR/CZK | 24.34 | +0.02% |
| USD/TRY | 49.99 | +0.05% |
| Brent Crude | 103.53 | -1.18% |
| Gold | 3,949.10 | -0.52% |
| Bitcoin | 77,208.44 | +0.69% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Month-over-Month | 1.84 | 2.40 | 2.58 |
| Inflation Rate Year-over-Year | 29.73 | 29.56 | 29.77 |
| Balance of Trade Prel | -5,160m | - | -6,700m |
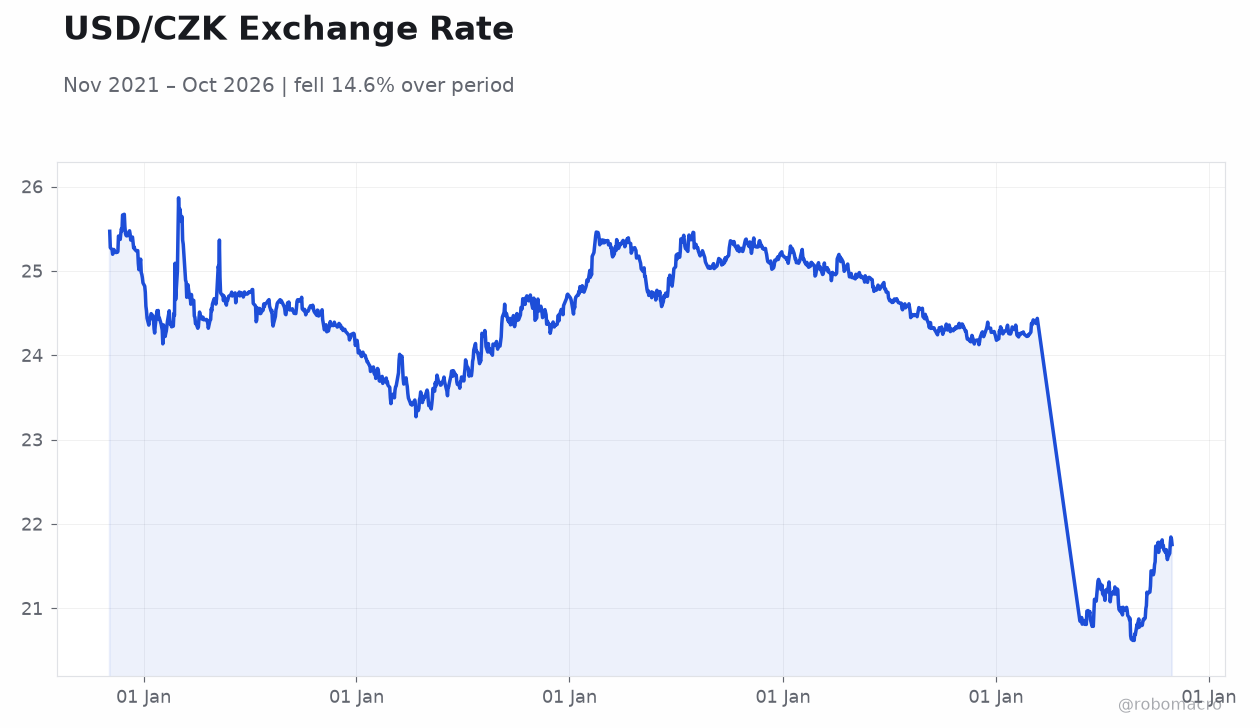
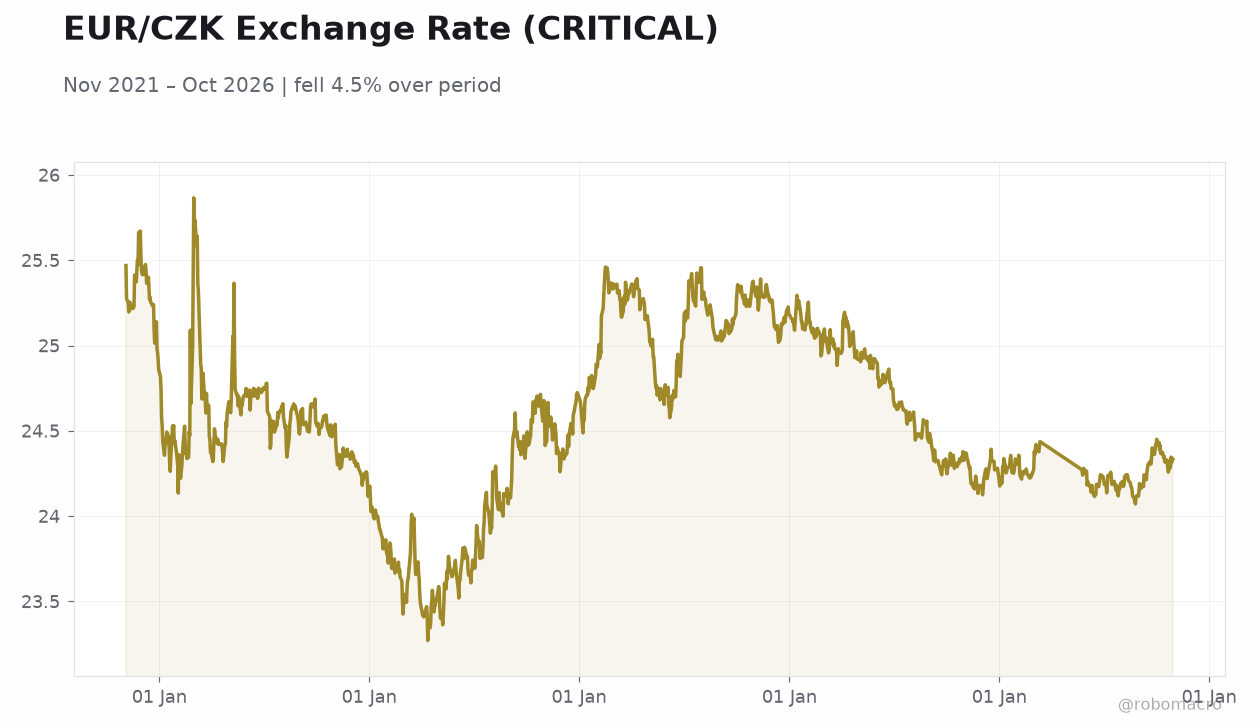 EUR/CZK Exchange Rate (CRITICAL) | Type: macro_line | EUR/CZK Exchange Rate (CRITICAL): 24.33 (2026-10-30) | Range: 23.27–25.87 | Trend(6pt): 25.47,24.04,25.28,24.78,24.31,24.33
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-11-04) | |||
| Central Bank Interest Rate Decision | 3.75 | 3.75 | 09:00 |
- Turkey's November CPI printed at 2.58% m/m and 29.77% y/y, both above consensus, keeping the CBRT's easing path constrained despite the lira's managed crawl near 50/USD.
- NBP is expected to hold at 3.75% on Wednesday, with the Tusk government's resolution of the management-board standoff removing a key political overhang on Polish monetary policy.
- Polish equities underperformed sharply (iShares Poland -2.95%) as rule-of-law tensions around the Constitutional Tribunal re-escalated ahead of the 2027 election cycle.
Yesterday's Recap
Turkey dominated Tuesday's data flow, with November CPI landing at 2.58% m/m versus a 2.4% consensus and 29.77% y/y against expectations of 29.56% — a marginal upside surprise that keeps headline inflation anchored just below 30% and reinforces the CBRT's cautious, gradual easing posture. The preliminary November trade deficit widened to $6.7bn from $5.16bn previously, a deterioration that, combined with sticky inflation, argues against any acceleration in rate cuts. The lira was essentially flat at 49.99/USD (+0.05%), suggesting the CBRT's managed depreciation path remains intact.
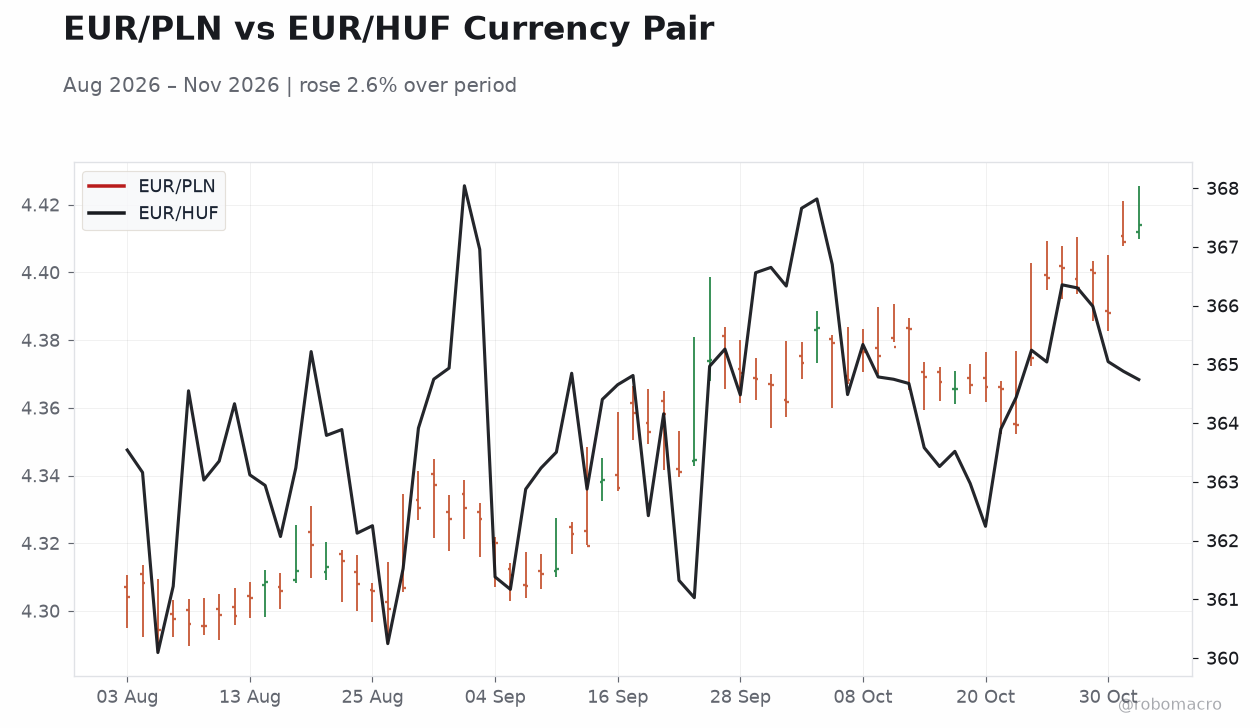
Elsewhere in the region, FX was quiet: EUR/PLN edged up 0.11% to 4.41, EUR/HUF slipped 0.07% to 364.61, and EUR/CZK was unchanged at 24.34. Polish equities bore the brunt of risk-off sentiment, with iShares Poland down 2.95% to $43.40, while Istanbul's BIST 100 gained 0.56% to 11,023.55. The Polish underperformance reflects domestic political noise rather than regional macro deterioration, with the Constitutional Tribunal dispute re-emerging as a campaign flashpoint.
The Day Ahead
The calendar is thin, with the sole high-impact event being the NBP's rate decision on Wednesday at 09:00 ET, where consensus and the previous level both sit at 3.75%. No change is expected, and the committee's communication will be scrutinised for any shift in tone following the resolution of the management-board appointments dispute. With Polish CPI at 3.21% y/y as of August, real rates remain modestly positive, giving the NBP room to stay on hold through year-end.
The CNB meets Thursday (5 November) with the policy rate at 3.75%, and Czech CPI at 2.51% keeps the bank comfortably within its tolerance band, supporting a steady-as-she-goes stance. Romanian and Hungarian calendars are empty, leaving regional attention on the NBP statement and any commentary on the zloty's recent softness.
Other Economic Notes
The Polish banking sector reported January–September net profit of PLN 32.28bn, down 10.5% y/y, according to NBP data — a reflection of compressed margins and higher funding costs as the rate-cutting cycle of prior years works through the system. Hungary's MNB household survey showed financial optimism declining in Q3 2026 even as borrowing appetite hit a four-year high, a divergence that suggests consumers are levering up while inflation perceptions remain elevated. ↓ p.2