Emerging Europe Macro Daily(Beta Mode)
NBP Hold Masks Political Risk; TR CPI Stays Hot
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 11,023.60 | +0.56% |
| iShares Poland | 42.72 | +0.06% |
| EUR/PLN | 4.41 | +0.05% |
| EUR/HUF | 364.49 | +0.15% |
| EUR/CZK | 24.35 | +0.14% |
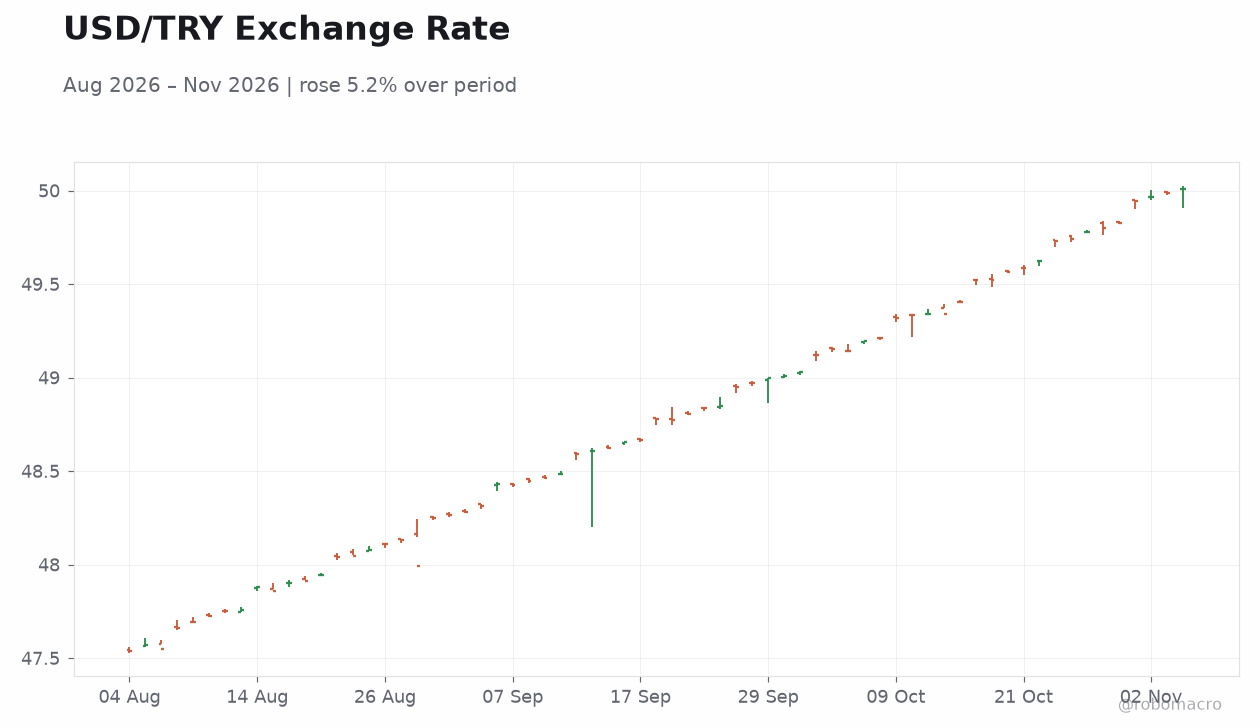
| USD/TRY | 50.01 | +0.05% |
| Brent Crude | 104.13 | +0.51% |
| Gold | 3,960.00 | +0.50% |
| Bitcoin | 77,342.96 | +0.87% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Month-over-Month | 1.84 | 2.40 | 2.58 |
| Inflation Rate Year-over-Year | 29.73 | 29.56 | 29.77 |
| Balance of Trade Prel | -5,160m | - | -6,700m |
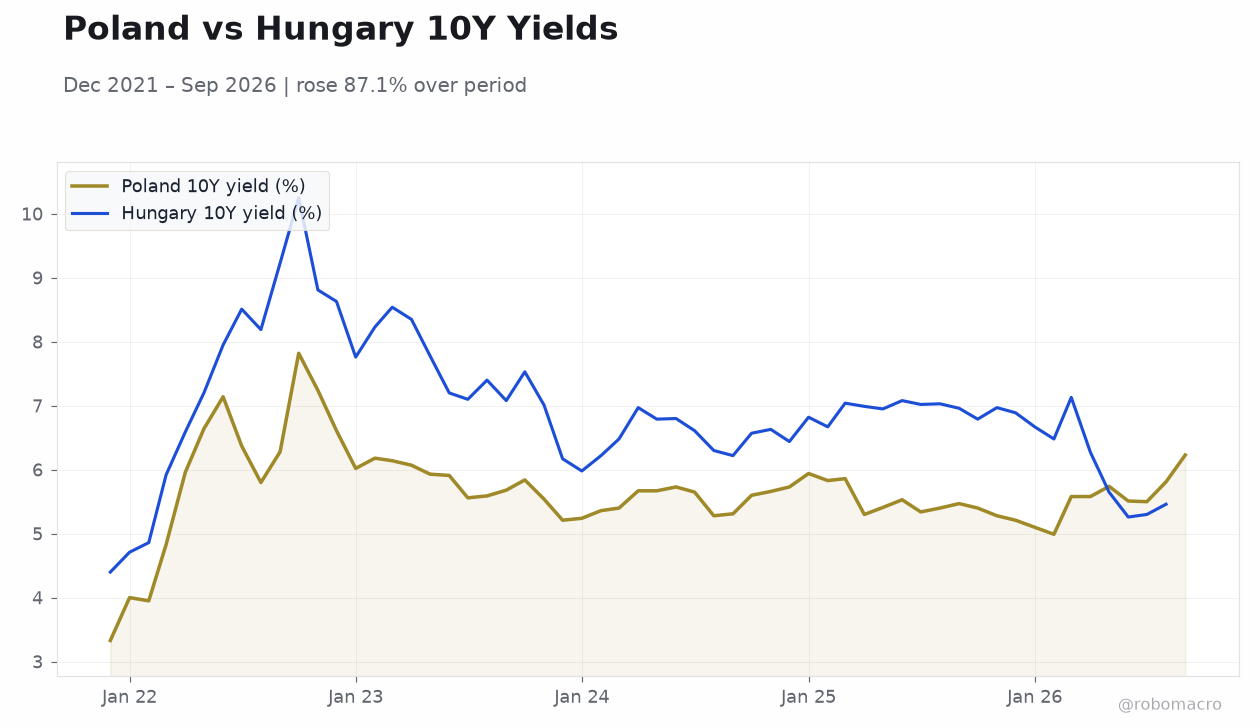 Poland vs Hungary 10Y Yields | Type: macro_line | Poland 10Y yield (%): 6.23 (2026-09-01) | Range: 3.33–7.82 | Trend(6pt): 3.33,6.18,5.67,5.53,5.81,6.23 | Hungary 10Y yield (%): 5.46 (2026-08-01) | Range: 4.4–10.25 | Trend(5pt): 4.4,8.23,6.97,7.08,5.46
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 3.75 | 3.75 | 09:00 |
- NBP expected to hold at 3.75% today amid a constitutional crisis that has put Governor Glapinski's future in doubt
- Turkish CPI printed at 29.77% y/y and 2.58% m/m, both above consensus, with the trade deficit widening to $6.7bn
- CEE FX broadly softer vs EUR; BIST 100 outperforms, Brent above $104 keeps energy-importing region on edge
Yesterday's Recap
Turkey dominated Tuesday's data flow, and the prints were unhelpful for the disinflation narrative. November 3 releases showed Turkish CPI at 2.58% m/m versus a 2.4% consensus, with the y/y rate at 29.77% against expectations of 29.56% — a marginal upside surprise that keeps the CBRT's easing path constrained. The preliminary trade balance deteriorated to -$6.7bn from -$5.16bn previously, underscoring the energy import bill as Brent holds above $104.
Markets absorbed the data without drama: BIST 100 rose 0.56% and USD/TRY edged up just 0.05% to 50.01, suggesting the lira's managed crawl remains intact. Elsewhere in the region, FX was quietly softer — EUR/PLN at 4.41 (+0.05%), EUR/HUF at 364.49 (+0.15%), EUR/CZK at 24.35 (+0.14%) — a uniform drift consistent with a firmer dollar backdrop rather than idiosyncratic stress. Polish equities via iShares Poland were essentially flat (+0.06%).
The dominant non-data story was Poland's constitutional tribunal standoff, where PM Tusk and President Nawrocki are locked in an escalating confrontation that Bloomberg Economics flagged as raising fresh doubts about Governor Glapinski's tenure ahead of today's NBP decision.
The Day Ahead
The single high-impact event on the regional calendar is the NBP rate decision at 09:00 ET, with consensus firmly anchored at a hold at 3.75% — the level in place since March 5. The decision itself is unlikely to move markets; the statement and press conference carry the risk, given the political crosscurrents around the governor's position and the rule-of-law fight that has drawn EU attention. With Polish CPI at 3.21% y/y as of August, the real rate remains modestly positive, giving the MPC room to sit still.
No other Emerging Europe releases are scheduled for today, and Thursday's calendar is empty, so attention shifts to the CNB's November 5 meeting tomorrow — the most ECB-sensitive of the regional central banks. Positioning into that decision, with the Czech policy rate at 3.75% and CPI at 2.51%, will likely dominate CZK flows late in the session.
Other Economic Notes
Poland's banking sector remains a quiet drag on the macro-financial backdrop: NBP reported January–September net profit of PLN 32.28bn, down 10.5% y/y, as margins compress and costs rise. ↓ p.2