Emerging Europe Macro Daily(Beta Mode)
Poland GDP, BNR Hold, Bond Woes Mount
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| BIST 100 | 11,811.20 | +1.24% |
| iShares Poland | 43.95 | +0.76% |
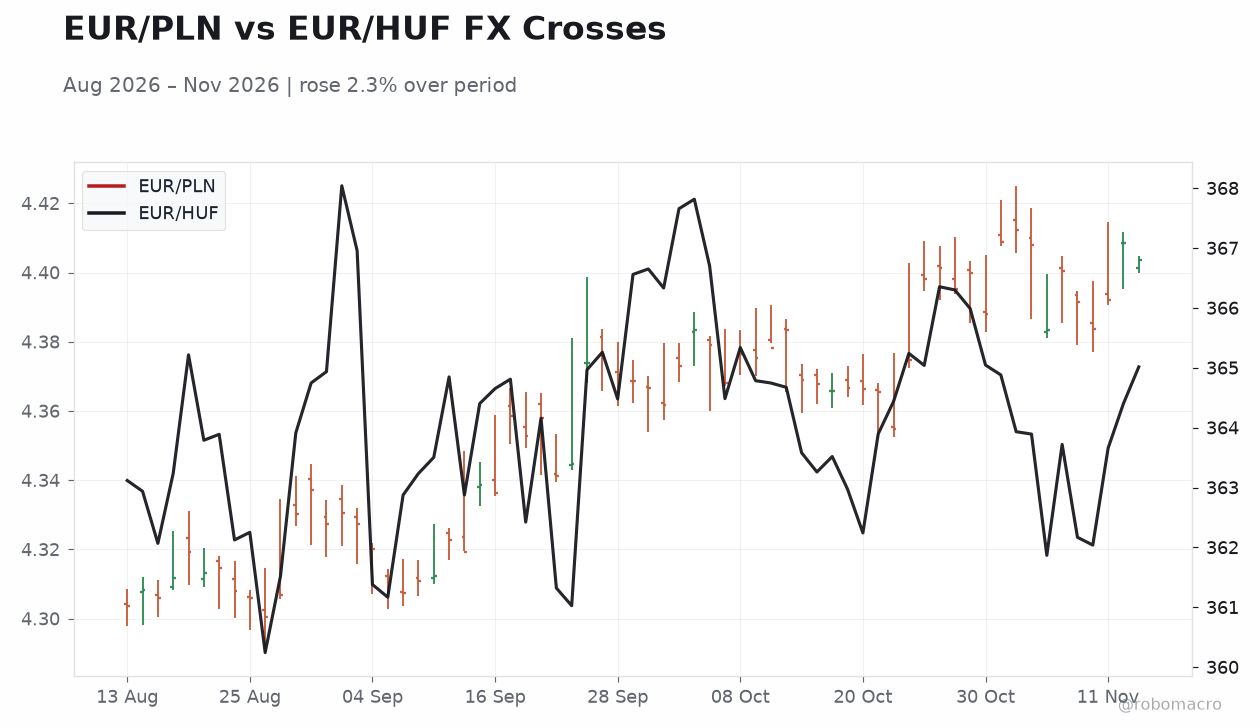
| EUR/PLN | 4.40 | -0.11% |
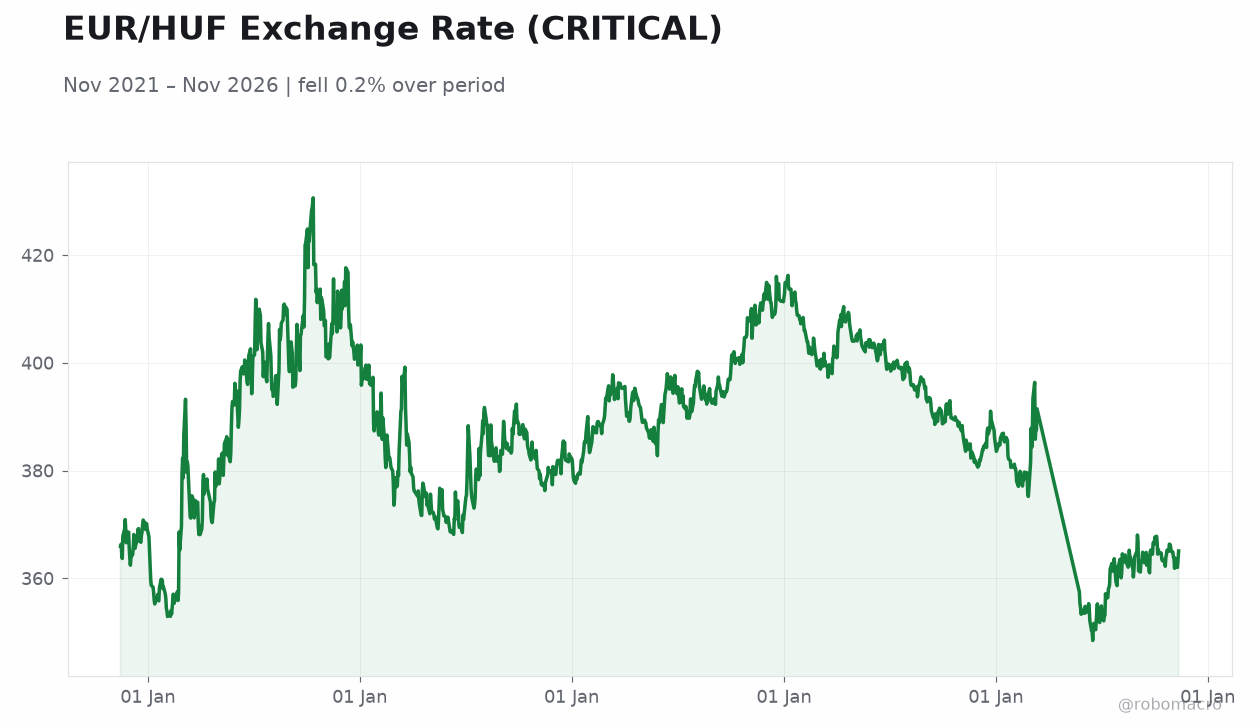
| EUR/HUF | 364.99 | +0.16% |
| EUR/CZK | 24.37 | +0.02% |
| USD/TRY | 50.36 | +0.22% |
| Brent Crude | 95.60 | -0.23% |
| Gold | 3,922.30 | +0.95% |
| Bitcoin | 68,572.74 | -7.29% |
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Year-over-Year | -1.70 | - | 2.60 |
| Central Bank Interest Rate Decision | 6.50 | 6.50 | 6.50 |
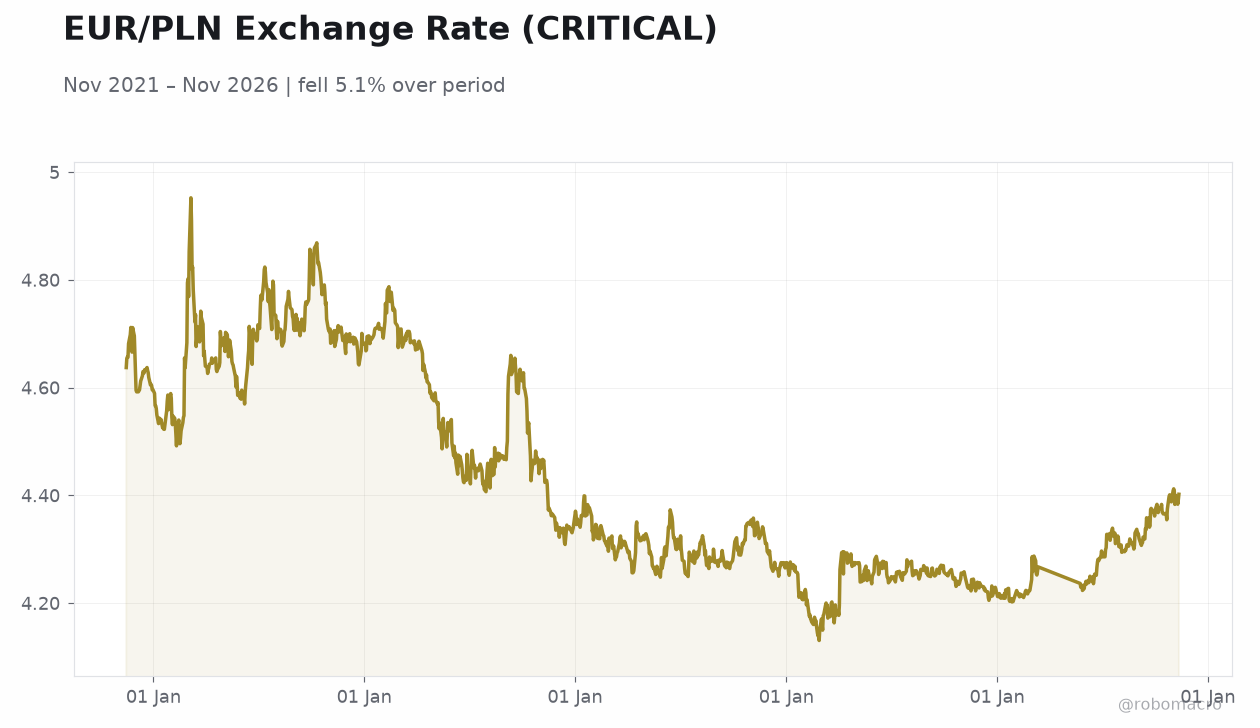 EUR/PLN Exchange Rate (CRITICAL) | Type: macro_line | EUR/PLN Exchange Rate (CRITICAL): 4.402 (2026-11-12) | Range: 4.131–4.952 | Trend(6pt): 4.637,4.713,4.256,4.248,4.392,4.402
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| GDP Growth Quarter-over-Quarter Preliminary | 1 | - | 03:30 |
| GDP Growth Year-over-Year Preliminary | 3.90 | 3.70 | 03:30 |
- Romania's BNR held its policy rate at 6.50% on November 12, matching consensus, as inflation remains above target.
- Turkey industrial production rebounded to +2.6% y/y in the November 10 print, reversing the prior -1.7% contraction.
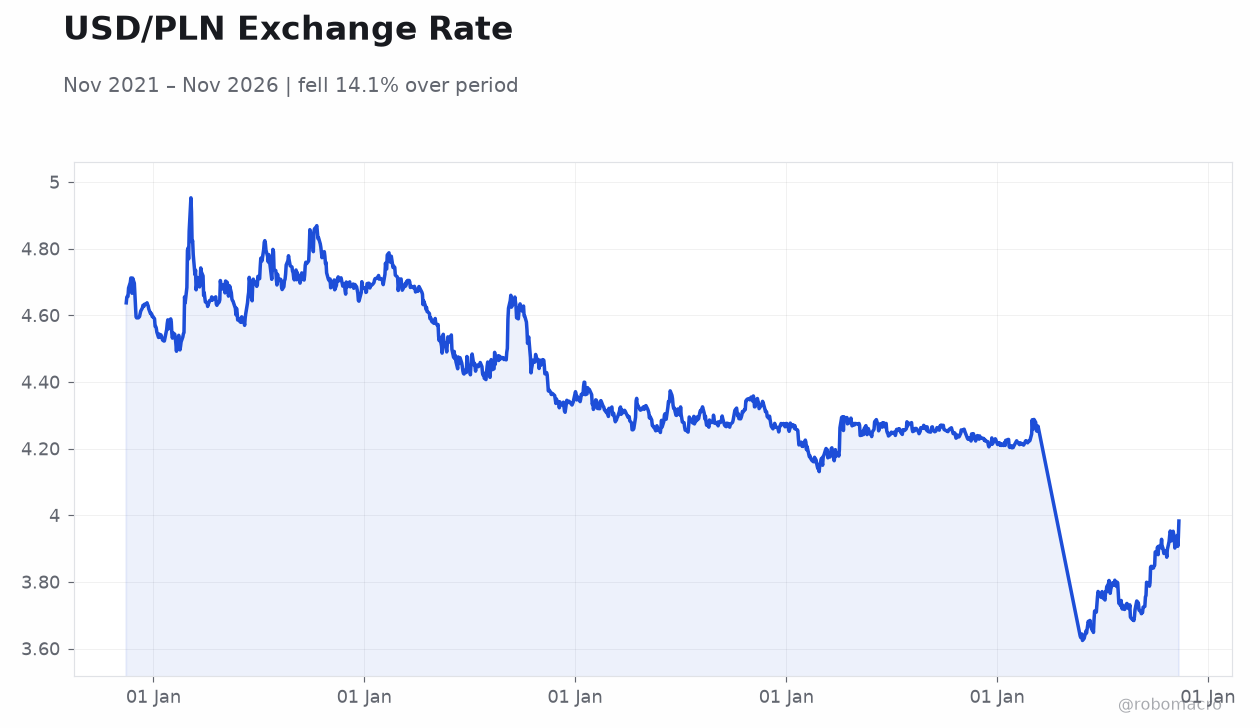
- Poland's preliminary Q3 GDP lands today (03:30 ET), with consensus at +3.7% y/y; Polish bonds remain under pressure on political turmoil.
Yesterday's Recap
Romania's central bank held its policy rate at 6.50% on November 12, in line with consensus, keeping the BNR in wait-and-see mode as inflation stays elevated. Turkey's industrial production printed at +2.6% y/y for the November 10 release, a sharp rebound from the prior -1.7% contraction and a sign that Turkish manufacturing is stabilizing despite tight monetary conditions. Polish assets were the dominant regional story: iShares Poland gained 0.76% while EUR/PLN eased 0.11% to 4.40, but Bloomberg reported that bondholders are increasingly questioning Poland's status as an emerging-market favorite as political turmoil undermines the government's fiscal credibility.
The zloty's modest firmness contrasts with the negative bond narrative, suggesting FX markets are pricing the political risk more lightly than rates markets. Elsewhere in the region, EUR/HUF rose 0.16% to 364.99 and EUR/CZK was essentially flat at 24.37, with the forint the weakest of the CEE currencies on the day. Turkey's BIST 100 outperformed, rising 1.24% to 11,811.20, while USD/TRY edged up 0.22% to 50.36, continuing the lira's slow grind weaker.
The Day Ahead
Poland's preliminary Q3 GDP is the sole regional release today, due at 03:30 ET, with consensus at +3.7% y/y following the prior +3.9% and QoQ consensus absent against a prior +1.0%. A print at or above consensus would reinforce the narrative of Polish domestic demand resilience, but the more important signal for markets may be the composition — whether growth is consumption-led or investment-driven, given the defense buildup highlighted by Politico. A soft print would sharpen the contrast with the bond market's fiscal concerns and could pressure the zloty.
No other Emerging Europe releases are scheduled for today or tomorrow, leaving Polish GDP as the single regional catalyst into the weekend. Markets will also watch whether the Polish 10-year yield extends its recent rise after Bloomberg's debt-woes story.
Other Economic Notes
Poland's rearmament drive is increasingly reliant on state-owned Polish Armaments Group, which Politico notes is playing a central role but faces its own operational troubles — a reminder that defense spending, while growth-positive, carries execution risk. Separately, the EU court rejected Poland's bid to overturn seven major climate laws, with lawsuits launched by the previous nationalist government kept alive under Prime Minister Donald Tusk; the ruling removes a legal overhang for Polish energy transition planning. ↓ p.2