MNB Hold Eyed as NBP-Tribunal Standoff Deepens
BIST 10011,841.80-0.01%
iShares Poland44.13+0.43%
EUR/PLN4.40-0.09%
EUR/HUF363.97+0.06%
Market Snapshot
| Asset | Level | Change |
|---|
| BIST 100 | 11,841.80 | -0.01% |
| iShares Poland | 44.13 | +0.43% |
| EUR/PLN | 4.40 | -0.09% |
| EUR/HUF | 363.97 | +0.06% |
| EUR/CZK | 24.40 | +0.04% |
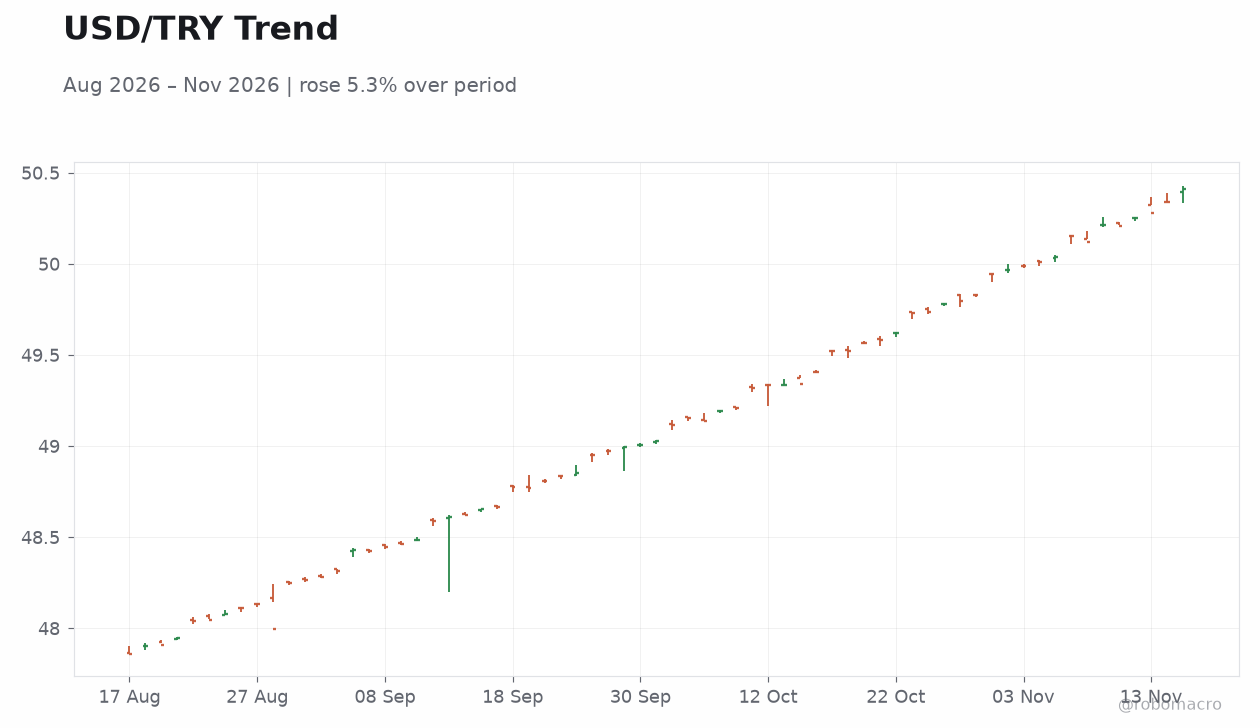
| USD/TRY | 50.41 | +0.13% |
| Brent Crude | 91.81 | -0.68% |
| Gold | 3,884.30 | +0.81% |
| Bitcoin | 64,790.38 | -0.79% |
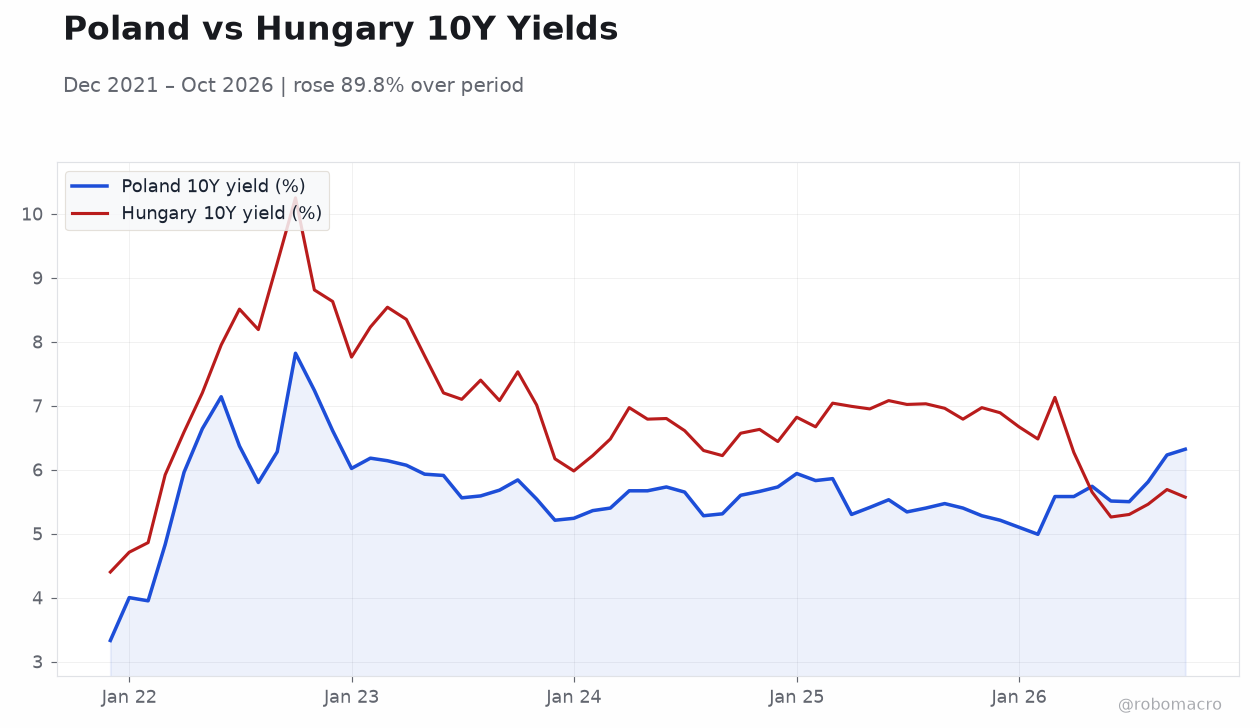
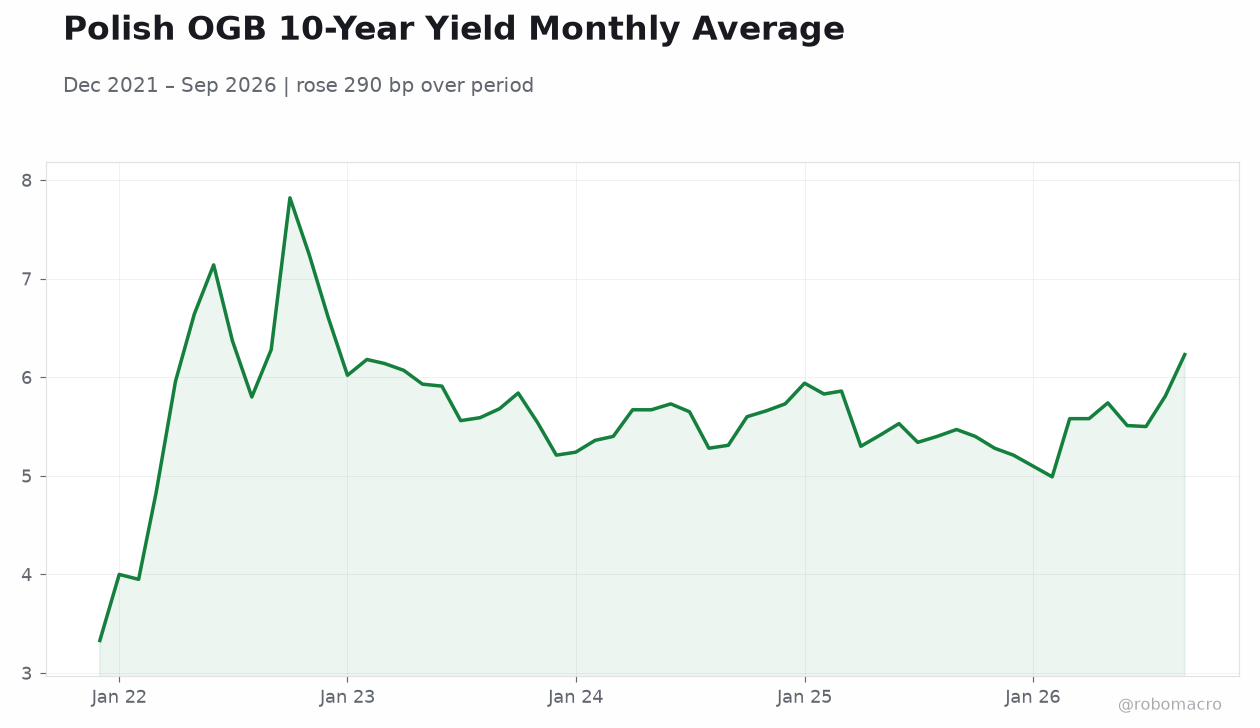
| Poland 10Y Govt Yield | - | - |
| Hungary 10Y Govt Yield | - | - |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| No events available |
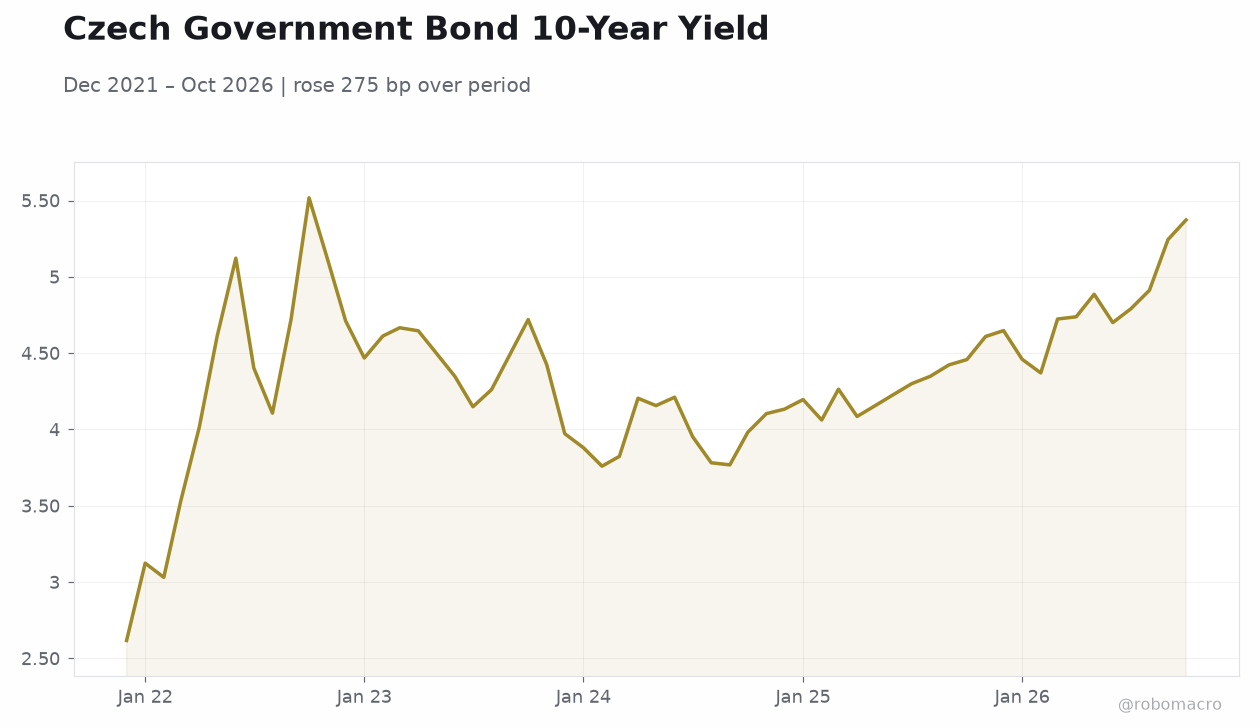 Czech Government Bond 10-Year Yield | Type: macro_line | Czech Government Bond 10-Year Yield: 5.372 (2026-10-01) | Range: 2.618–5.518 | Trend(6pt): 2.618,4.612,4.205,4.23,4.912,5.372
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| Central Bank Interest Rate Decision | 5.50 | - | 08:00 |
- MNB's Monetary Council is expected to hold the base rate at 5.50% for a third consecutive month, with global risk aversion and a recent inflation uptick arguing against further easing.
- NBP has suspended all payment orders from the Constitutional Tribunal's accounts, escalating a legal-institutional standoff that carries reputational risk for Polish financial plumbing.
- Regional FX is broadly stable (EUR/PLN 4.40, EUR/HUF 363.97, EUR/CZK 24.40), while USD/TRY grinds to 50.41 and Brent's slide to $91.81 offers limited import-bill relief.
Yesterday's Recap
Monday's session in Emerging Europe was light on scheduled macro data, with no releases on the regional calendar, leaving markets to trade off positioning and institutional headlines. Poland dominated the news flow: the National Bank of Poland suspended all payment orders from the accounts of the Constitutional Tribunal, with the central bank's legal department concluding there were grounds to halt execution pending clarity on who is authorized to dispose of the funds. The move drew commentary from former NBP governor Hanna Gronkiewicz-Waltz, now an MEP, who pointed to a procedural exit from the dispute, while market experts flagged the operational and reputational implications of a central bank freezing a constitutional body's transfers.
Polish assets took it in stride — iShares Poland edged up 0.43% and EUR/PLN slipped 0.09% to 4.40, suggesting investors read the episode as political noise rather than a systemic threat. Elsewhere, EUR/HUF firmed 0.06% to 363.97 and EUR/CZK added 0.04% to 24.40, both essentially flat. Turkey's BIST 100 closed unchanged at 11,841.80 while USD/TRY advanced 0.13% to 50.41, extending the lira's slow crawl.
Brent crude fell 0.68% to $91.81, a modest positive for the region's energy-importing economies, while gold's 0.81% gain to $3,884.30 reflected lingering safe-haven demand.
The Day Ahead
The sole scheduled event on the regional calendar is the MNB's rate decision at 08:00 ET, with the consensus pointing to an unchanged 5.50% base rate. The decision follows a -25bp cut at the 2026-08-25 meeting and a hold at the 2026-10-20 meeting, and a third consecutive hold would confirm the Council's cautious pause amid elevated global risk and a recent inflation uptick. Markets will parse the accompanying statement for guidance on the timing of any resumption of easing, with the next scheduled meeting on 2026-12-15.
No other Emerging European releases are due, so attention will shift to the MNB press communication and any FX reaction in the forint. With EUR/HUF at 363.97, a hawkish-hold tone could offer modest support, while any hint of a faster easing path would test the pair's recent range.
Page 1
Never miss an issue
Subscribe to Emerging Europe Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.