Eurozone Macro Daily(Beta Mode)
ZEW Data Looms Over Divergent Euro Markets
Market Snapshot
| Asset | Level | Change |
|---|---|---|
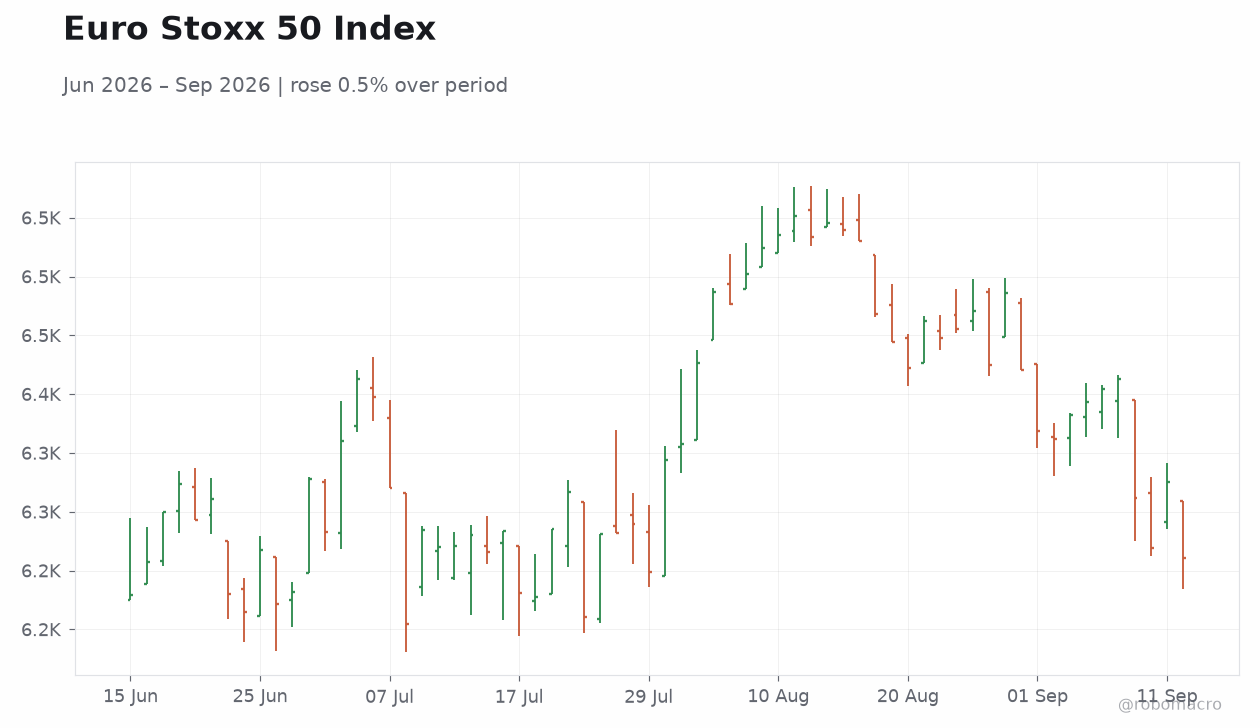
| Euro Stoxx 50 | 6,260.38 | -1.02% |
| DAX | 25,568.56 | +0.82% |
| CAC 40 | 8,117.78 | -0.76% |
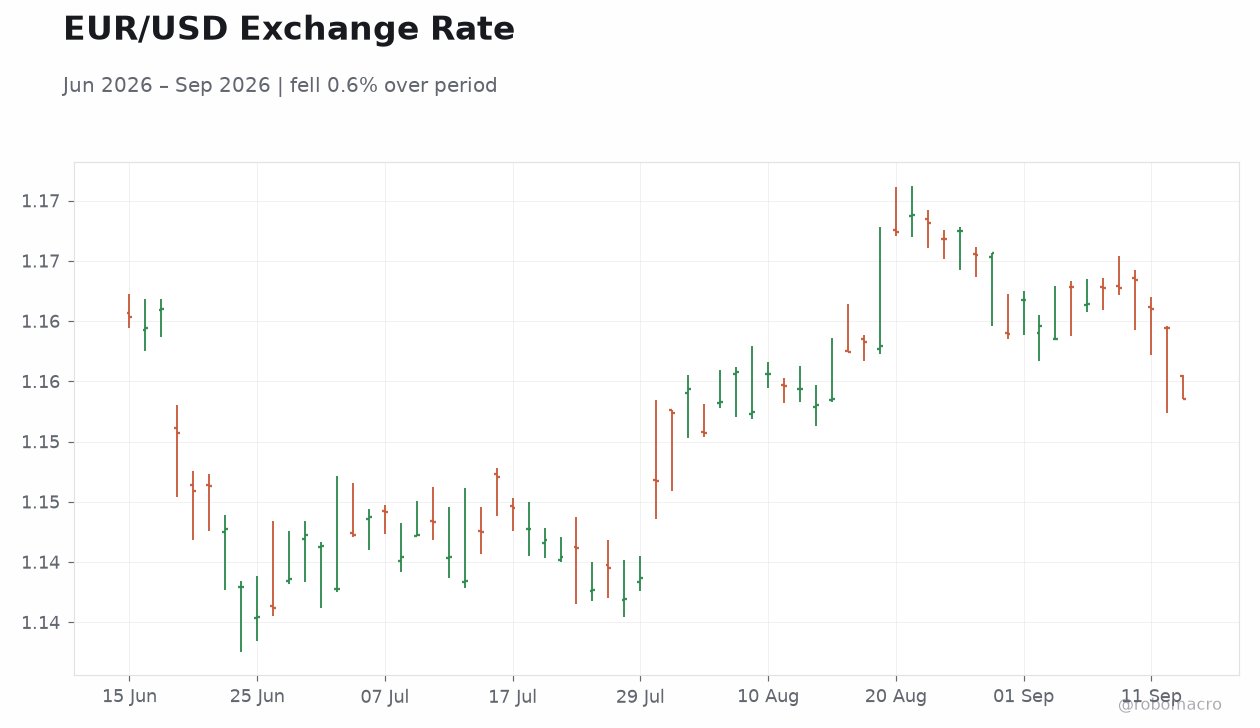
| EUR/USD | 1.15 | -0.49% |
| EUR/GBP | 0.86 | -0.16% |
| EUR/JPY | 178.51 | +0.36% |
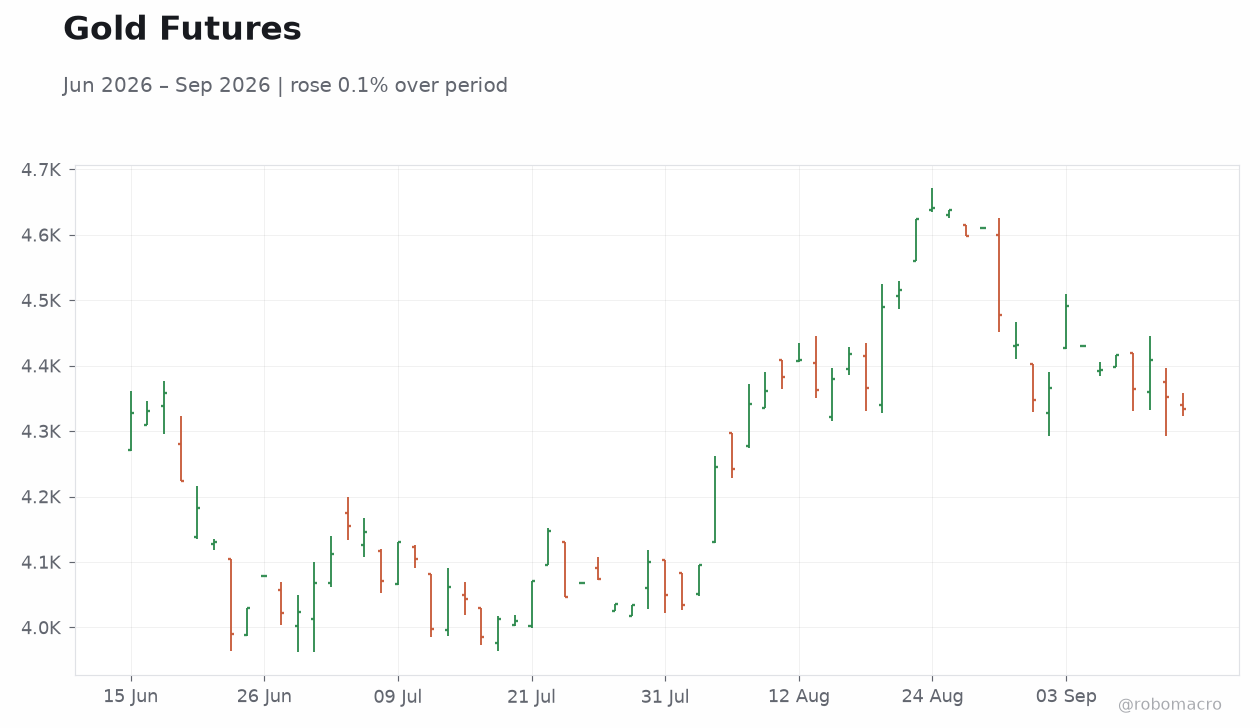
| Gold | 4,331.40 | -0.47% |
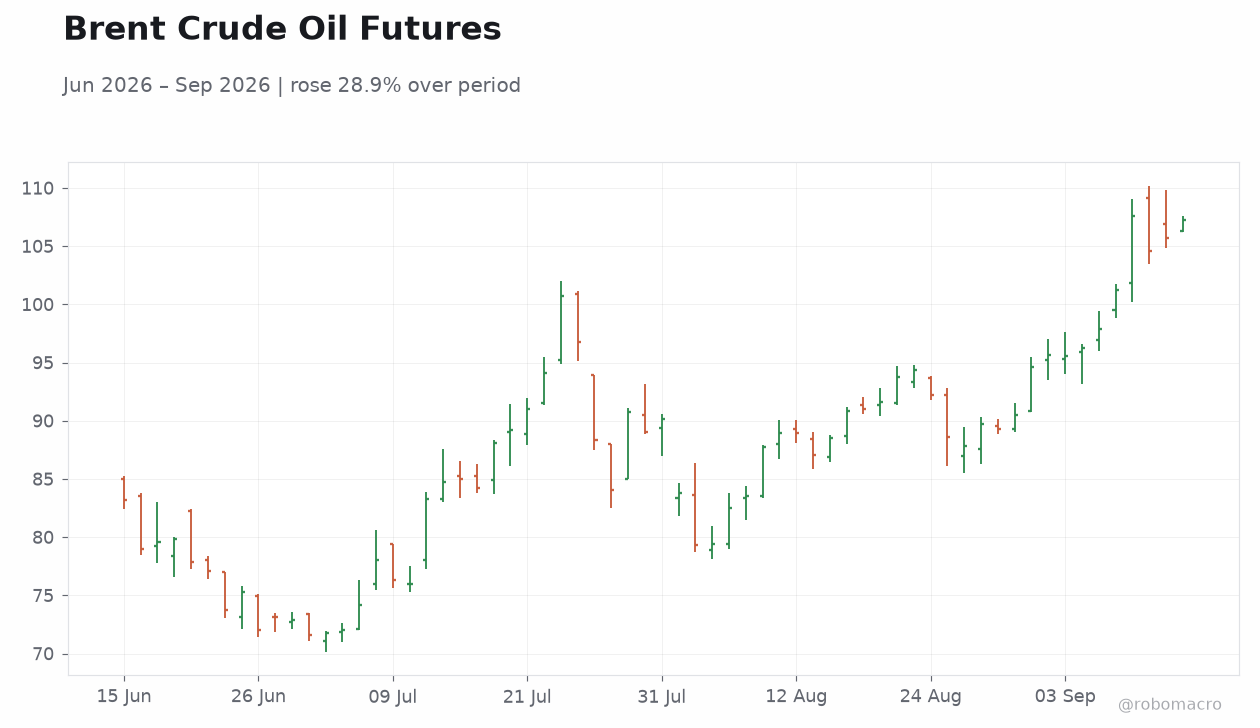
| Brent Crude | 107.21 | +1.45% |
| Bitcoin | 77,623.54 | +1.02% |
| German 2Y Bund | - | - |
| German 10Y Bund | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
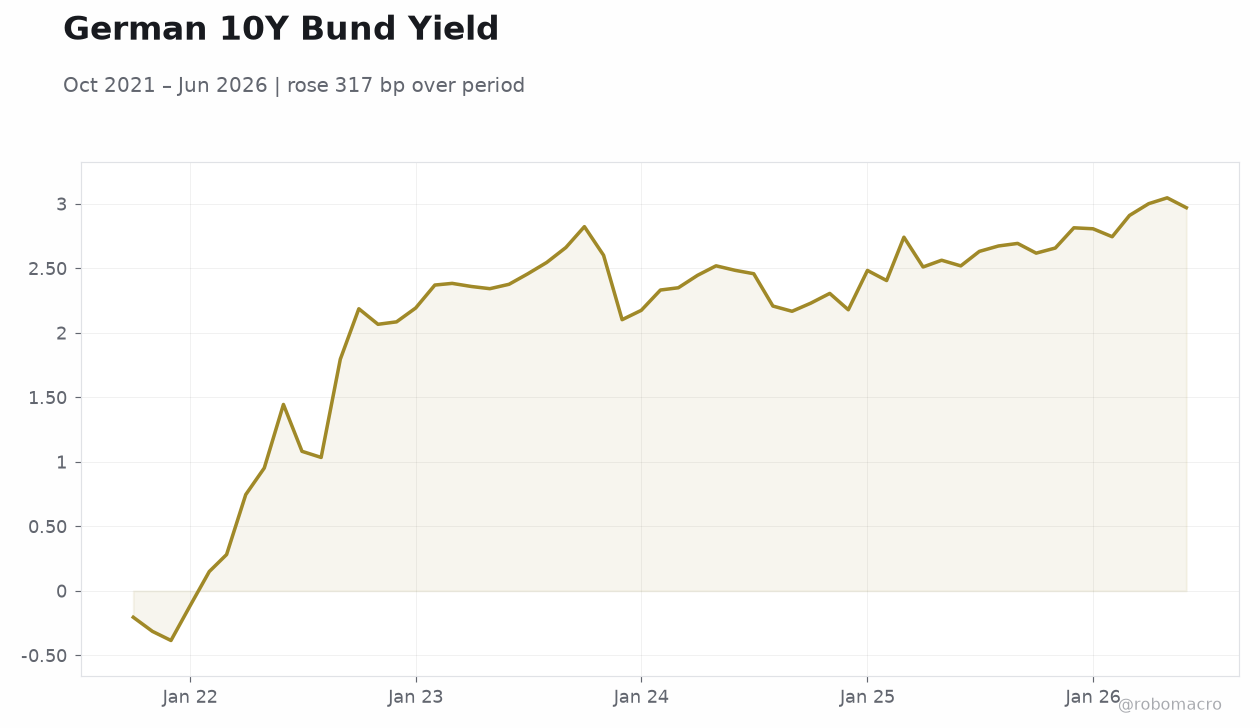 German 10Y Bund Yield | Type: macro_line | Yield %: 2.97 (2026-06-01) | Range: -0.3843–3.046 | Trend(5pt): -0.2043,2.085,2.332,2.51,2.97
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wholesale Prices Month-over-Month | 0.20 | 0.10 | 02:00 |
| Wholesale Prices Year-over-Year | 5.30 | - | 02:00 |
| Trade Balance | 4,232m | 4,770m | 04:00 |
| ZEW Economic Sentiment Index | 34.20 | 37 | 05:00 |
| Unemployment Rate | 4 | - | 00:30 |
| Producer Price Index Year-over-Year | 3 | 3.90 | 02:00 |
| Consumer Confidence Index | -34 | - | 00:30 |
| Trade Balance | -7,690m | - | 04:00 |
- German ZEW sentiment expected at 37, up from 34.2, with wholesale prices also due.
- Euro Stoxx 50 fell 1.02% while DAX rose 0.82% and German 10-year Bund yield dropped to 2.97%.
- ECB deposit rate holds at 2.25% as Eurozone CPI stands at 3.30% and leadership talks intensify.
Yesterday's Recap
No economic data releases occurred across Germany, France, Italy, Spain or the Netherlands on 14 September. Euro Stoxx 50 declined 1.02% to 6,260.38 while DAX advanced 0.82% to 25,568.56 and CAC 40 slipped 0.76% to 8,117.78. EUR/USD fell 0.49% to 1.15 and EUR/GBP eased 0.16% to 0.86.
German 10-year Bund yield were unavailable from the daily warehouse. Christian Democrats topped local polls in Lower Saxony, with the AfD finishing third. A Volkswagen plant conversion to defense production offered limited relief to the car sector.
German Foreign Minister Wadephul urged Ukraine to buy more German weapons.
The Day Ahead
Germany releases wholesale prices month-over-month at 02:00 ET with consensus at 0.1% versus prior 0.2%, alongside year-over-year figures. Italy publishes trade balance at 04:00 ET, expected at €4.77 billion after €4.232 billion previously. Germany’s ZEW Economic Sentiment Index prints at 05:00 ET, forecast at 37 after 34.2, carrying the highest market impact.
Later in the week the Netherlands reports unemployment on 17 September and Germany issues producer prices on 18 September. Traders will watch ZEW deviations for signals on German growth and Bund yield direction.
Other Economic Notes
Germany enters the heating season with historically low gas storage levels, raising risks for winter energy costs. Fuel prices in France and Germany have climbed above €2.30 per liter, prompting government concerns over localized shortages. French officials seek €30 billion in budget savings, including a proposed one-point de-indexation of pensions.
Political shifts in Germany and France add uncertainty ahead of potential fiscal tightening. These pressures coincide with elevated Eurozone CPI at 3.30% and steady ECB policy.
Global Macro News
Brent crude rose 1.45% to $107.21, supporting energy exporters while adding to European input costs. Gold slipped 0.47% to $4,331.40 and Bitcoin gained 1.02% to $77,623.54. ↓ p.2