Eurozone Macro Daily(Beta Mode)
French Spreads Hit Euro-Crisis Highs
Market Snapshot
| Asset | Level | Change |
|---|---|---|
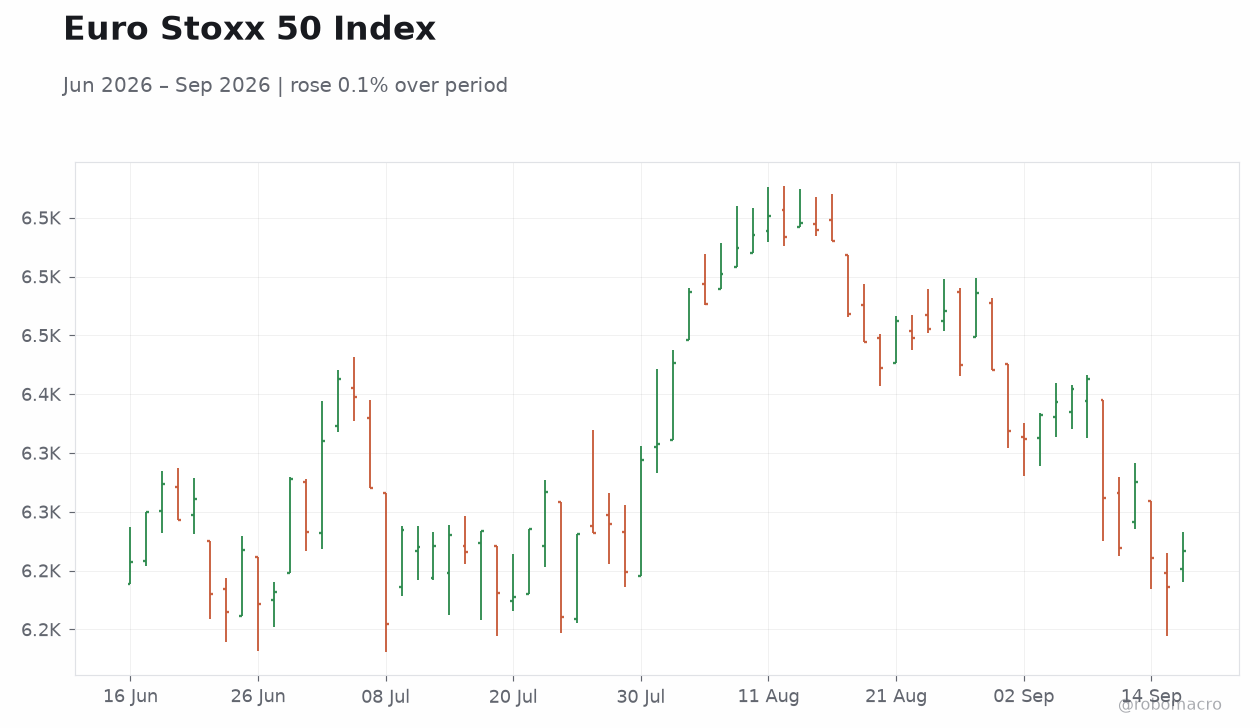
| Euro Stoxx 50 | 6,266.50 | +0.48% |
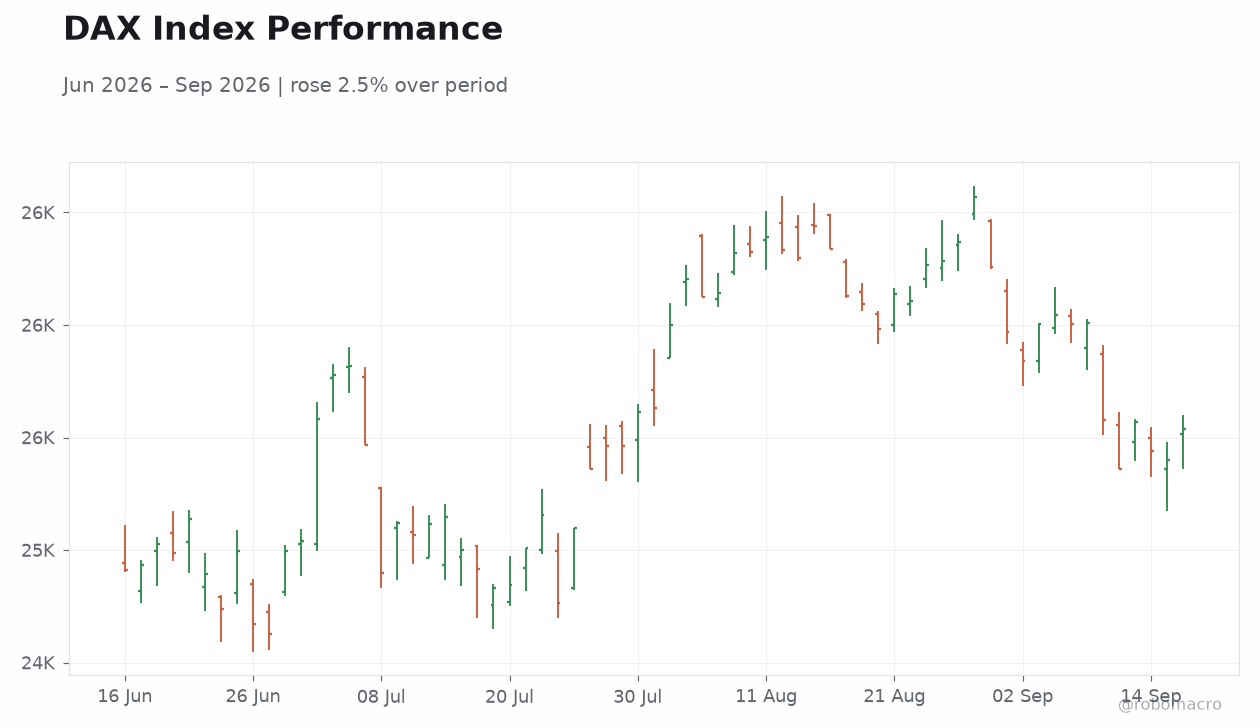
| DAX | 25,559.25 | +0.62% |
| CAC 40 | 8,140.59 | +0.62% |
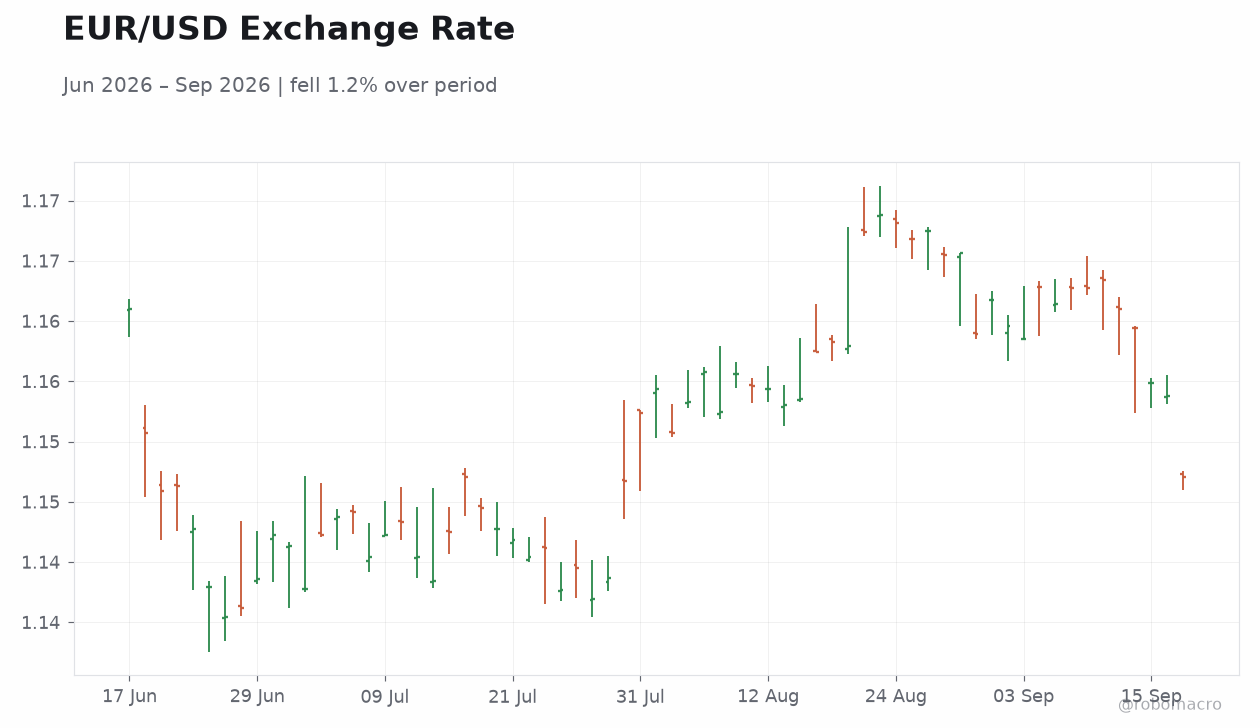
| EUR/USD | 1.15 | -0.59% |
| EUR/GBP | 0.86 | +0.07% |
| EUR/JPY | 178.59 | -0.31% |
| Gold | 4,338.30 | -1.12% |
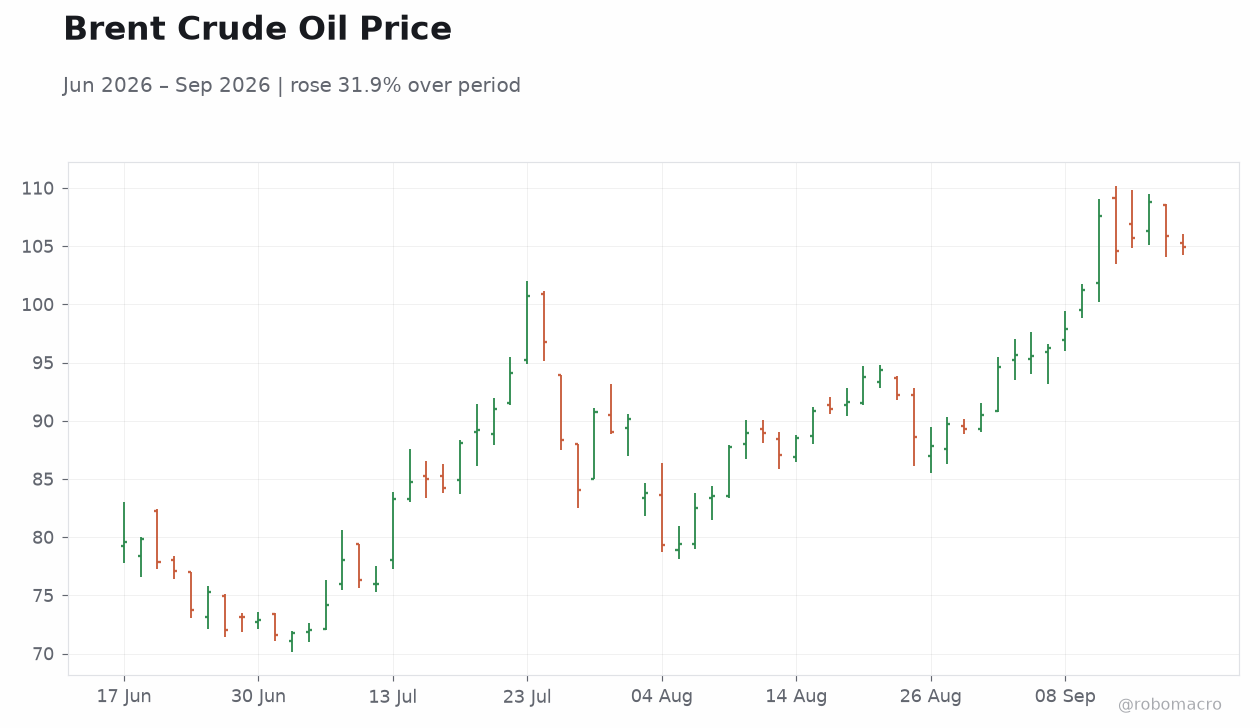
| Brent Crude | 105.18 | -0.61% |
| Bitcoin | 76,222.30 | +0.81% |
| German 2Y Bund | 3.24% | -2 bp |
| German 10Y Bund | 3.58% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
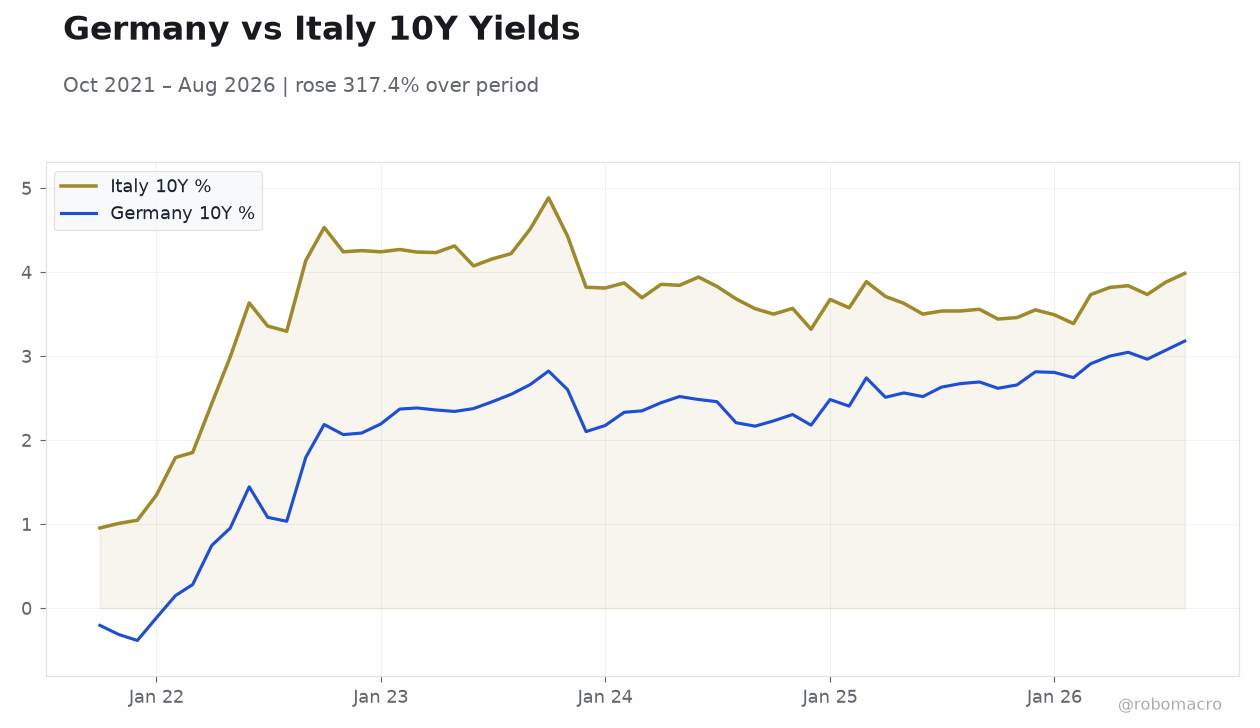 Germany vs Italy 10Y Yields | Type: macro_line | Italy 10Y %: 3.986 (2026-08-01) | Range: 0.9549–4.885 | Trend(6pt): 0.9549,4.257,3.872,3.712,3.734,3.986 | Germany 10Y %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.2043,2.085,2.332,2.51,2.964,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Unemployment Rate | 4 | - | 00:30 |
| Producer Price Index Year-over-Year | 3 | 4.10 | 02:00 |
| Consumer Confidence Index | -34 | - | 00:30 |
| Trade Balance | -7,690m | - | 04:00 |
| S&P Global Composite PMI Flash | 48.50 | - | 03:15 |
| S&P Global Manufacturing PMI Flash | 51.10 | - | 03:15 |
| S&P Global Services PMI Flash | 48 | - | 03:15 |
| S&P Global Manufacturing PMI Flash | 54.30 | - | 03:30 |
| S&P Global Composite PMI Flash | 51.80 | - | 03:30 |
| S&P Global Services PMI Flash | 49.70 | - | 03:30 |
- Eurozone equities rose with the Euro Stoxx 50 up 0.48% while German 2-year Bund yields fell 2 bp to 3.24%.
- No macro releases occurred on 16 September across Germany, France, Italy, Spain or the Netherlands.
- French sovereign spreads widened to the highest level since the euro-area debt crisis as fiscal concerns persisted.
Yesterday's Recap
European equities advanced on 16 September with the Euro Stoxx 50 closing at 6,266.50, up 0.48%, the DAX at 25,559.25, up 0.62%, and the CAC 40 at 8,140.59, up 0.62%. The euro weakened against the dollar, with EUR/USD falling 0.59% to 1.15, while EUR/GBP edged 0.07% higher to 0.86. German 2-year Bund yields declined 2 bp to 3.24% and the 10-year yield held steady at 3.58%.
No economic data were published in any major member state. Chancellor Friedrich Merz cancelled his UN General Assembly trip amid domestic political pressure ahead of state elections. European natural gas prices swung as traders assessed German winter stockpiling plans.
French sovereign spreads over German Bunds reached the widest levels since the euro-area debt crisis, reflecting reduced investor appetite for French debt.
The Day Ahead
The Netherlands Unemployment Rate is due at 00:30 ET on 17 September with the prior reading at 4.0%. Germany’s Producer Price Index Year-over-Year follows on 18 September, with consensus at 4.1% versus the previous 3.0%. Flash PMIs for France, Germany and the euro area are scheduled for 23 September, covering manufacturing and services.
The Ifo Business Climate survey for Germany appears on 24 September. These releases will provide fresh readings on price pressures and business sentiment across the bloc’s largest economies. No ECB speeches are listed in the immediate calendar.
Other Economic Notes
The 2026 Fortune 500 Europe list showed the UK overtaking Germany in company representation, with Volkswagen and Shell occupying the top two spots. European industry continues to lack momentum according to ING analysis, with output remaining subdued across core member states. Energy security concerns intensified after reports of Saudi Arabia halting certain oil supplies to the region.
These developments underscore persistent fiscal and supply-side challenges facing the euro area. Reports also noted duplication risks in supply chains from proposed retail splits in other markets, adding to broader cost pressures.