Eurozone Macro Daily(Beta Mode)
German Wholesale Prices Surge, Equities Advance
Market Snapshot
| Asset | Level | Change |
|---|---|---|
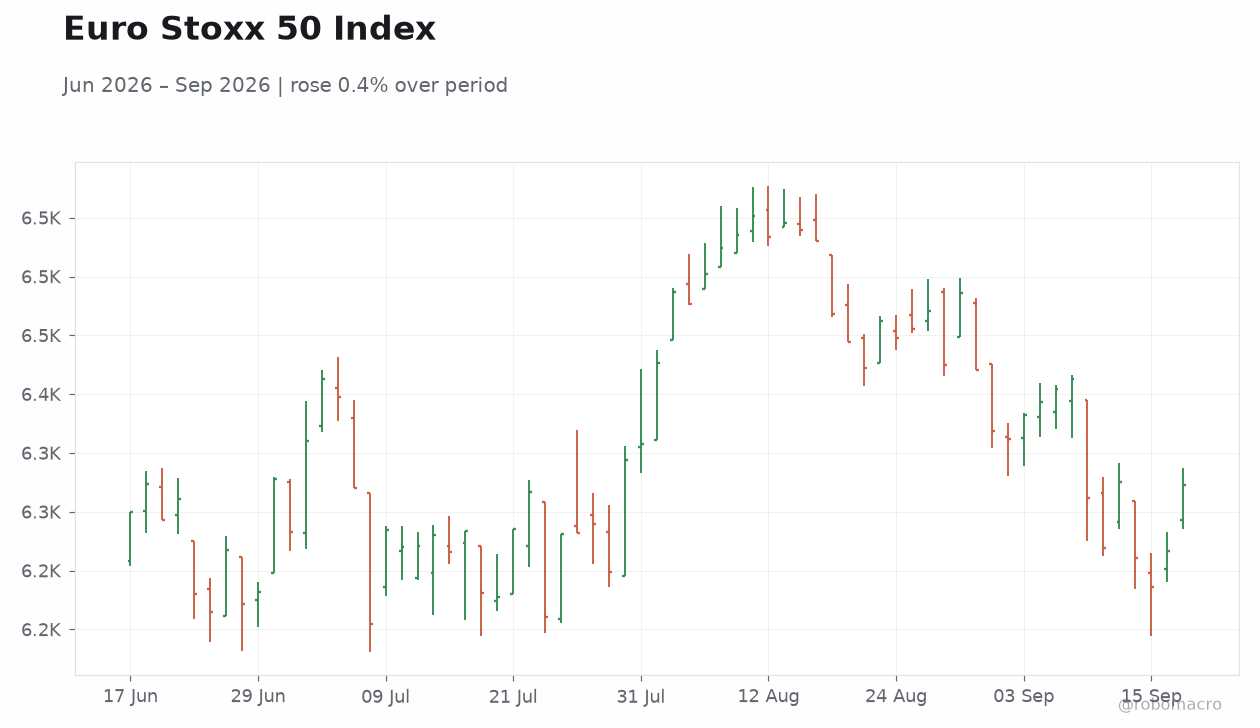
| Euro Stoxx 50 | 6,322.90 | +0.90% |
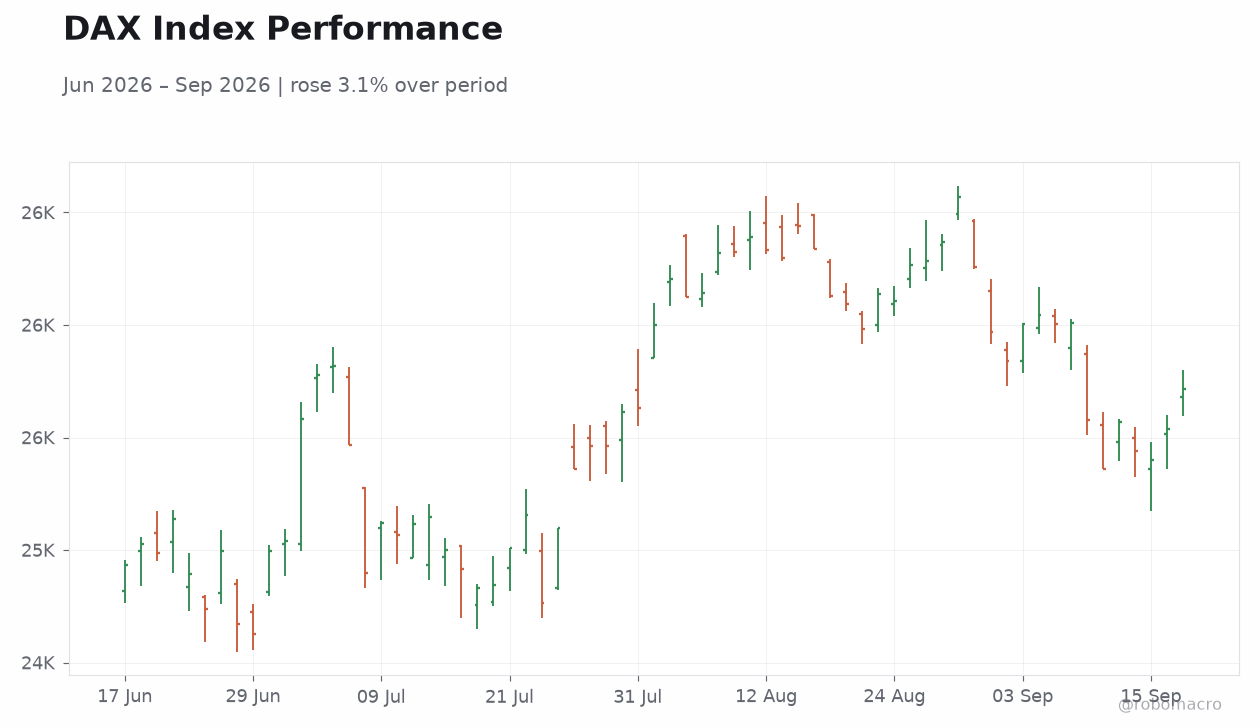
| DAX | 25,733.26 | +0.77% |
| CAC 40 | 8,186.93 | +0.57% |
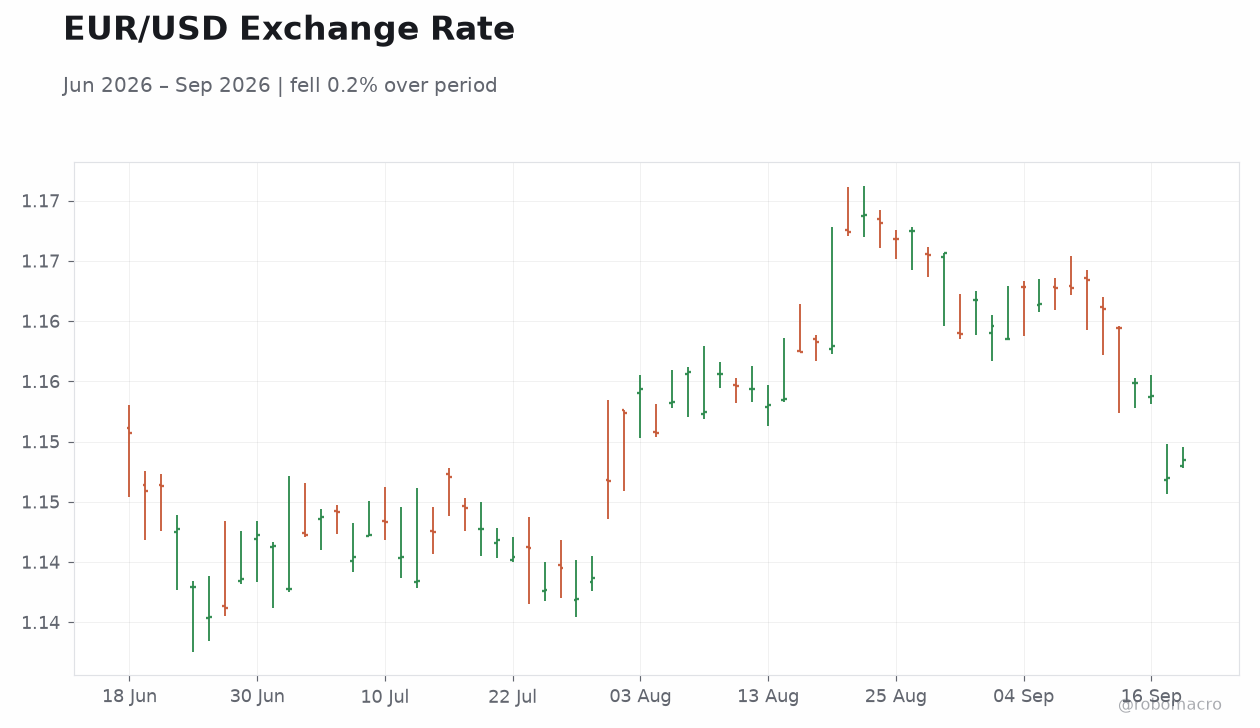
| EUR/USD | 1.15 | +0.13% |
| EUR/GBP | 0.86 | +0.22% |
| EUR/JPY | 178.97 | -0.10% |
| Gold | 4,424.20 | +0.56% |
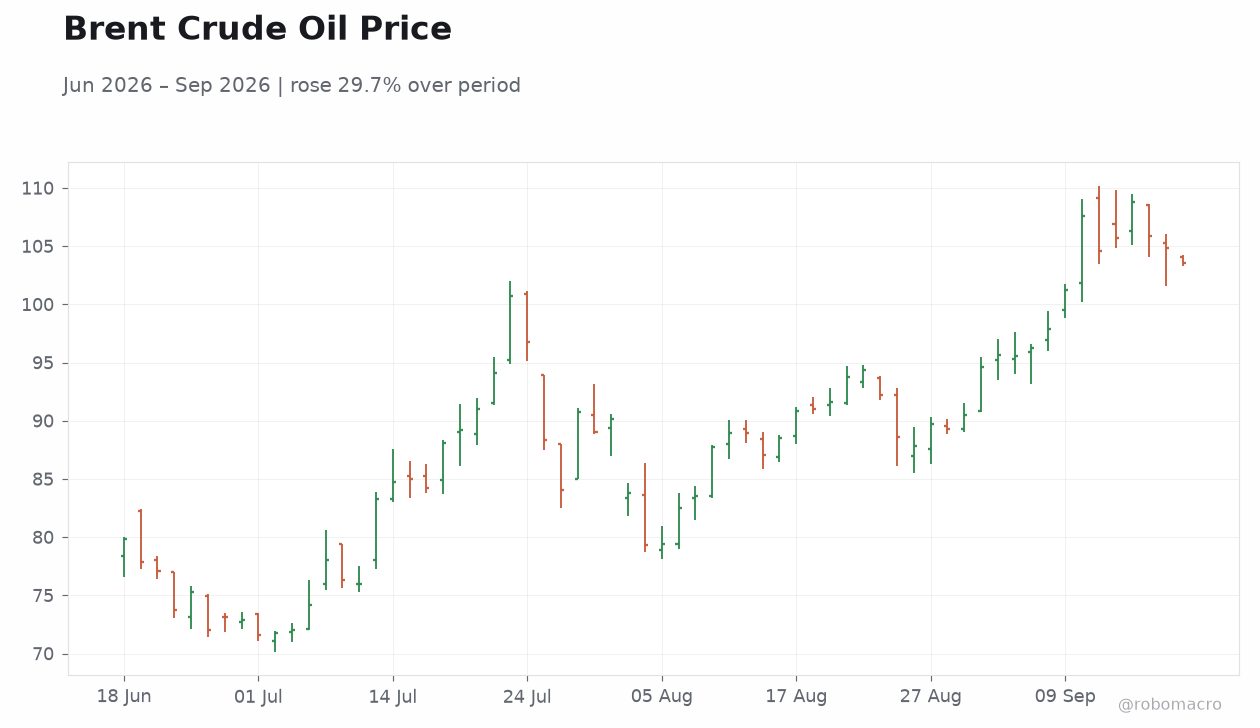
| Brent Crude | 103.34 | -1.41% |
| Bitcoin | 77,422.64 | +1.67% |
| German 2Y Bund | 3.17% | +13 bp |
| German 10Y Bund | 3.56% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Wholesale Prices Month-over-Month | 0.20 | 0.10 | 0.90 |
| Wholesale Prices Year-over-Year | 5.30 | - | 6.80 |
| Trade Balance | 4,343m | 4,770m | 8,240m |
| ZEW Economic Sentiment Index | 34.20 | 37 | 34.70 |
| Unemployment Rate | 4 | - | 4 |
| Producer Price Index Year-over-Year | 3 | 4.10 | - |
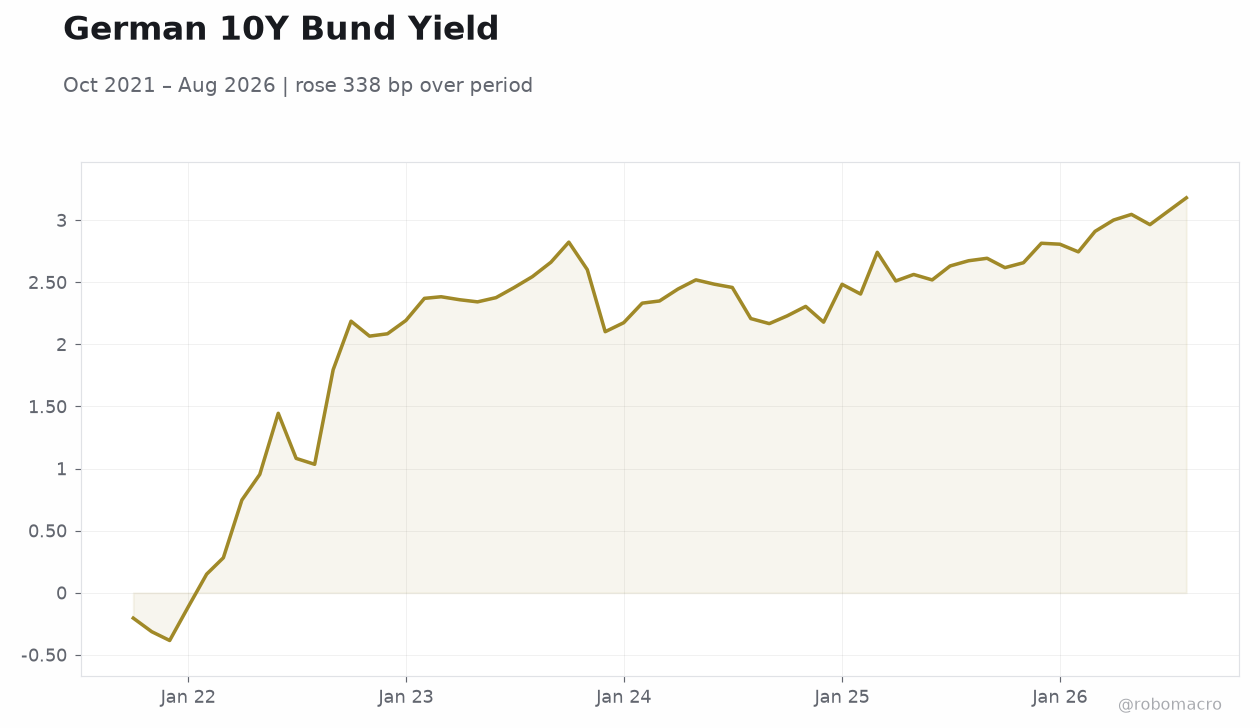 German 10Y Bund Yield | Type: macro_line | Yield %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.2043,2.085,2.332,2.51,2.964,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- German wholesale prices rose sharply, with MoM at 0.9% versus 0.1% consensus.
- Italian trade surplus widened to €8.24 billion, exceeding expectations.
- Euro Stoxx 50 gained 0.90% while German 2-year yields climbed 13 bp to 3.17%.
Yesterday's Recap
German wholesale prices surprised to the upside on 17 September, with the month-over-month rate at 0.9% against a 0.1% consensus and the year-over-year measure reaching 6.8% from 5.3% prior. Italy recorded a stronger trade balance of €8.24 billion versus the €4.77 billion forecast. German ZEW Economic Sentiment Index rose modestly to 34.7 from 34.2, though below the 37 consensus.
Dutch unemployment stayed at 4.0%. Euro Stoxx 50 closed at 6,322.90, up 0.90%, while DAX advanced 0.77% to 25,733.26 and CAC 40 rose 0.57% to 8,186.93. EUR/USD finished at 1.15 after a 0.13% gain.
German 2-year Bund yields increased 13 bp to 3.17% and 10-year yields rose 5 bp to 3.56%. The data mix showed firmer German price pressures alongside slightly softer sentiment, with no immediate market reaction evident in the supplied figures. No ECB Governing Council speeches were reported.
The Day Ahead
No scheduled economic releases appear for the Eurozone or major member states on 18 or 19 September. Markets will monitor any follow-through from the German wholesale price surprise and Italian trade data. Attention may turn to political developments in Germany ahead of state elections.
Broader global risk sentiment and US policy signals could influence EUR crosses and Bund yields. Equity flows into Euro Stoxx 50 and DAX may reflect positioning ahead of the weekend. Investors will also watch for any updates on trade policy toward Chinese hybrids and domestic fiscal proposals.
Other Economic Notes
Germany’s Vice Chancellor urged EU tariffs on Chinese hybrid vehicles, adding to trade tensions. Social Democrats proposed taxing AI-driven corporate revenue to support the welfare state. Two German state elections on Sunday could test Chancellor Merz following recent AfD gains.
Toyota and partners advanced plans for hydrogen trucks in Germany. These developments highlight domestic policy pressures alongside external trade frictions affecting German industry. The combination of price data and political signals may keep focus on growth and competitiveness risks.