Eurozone Macro Daily(Beta Mode)
Merz Defeat, French Debt Downgrade Spark Alarm
Market Snapshot
| Asset | Level | Change |
|---|---|---|
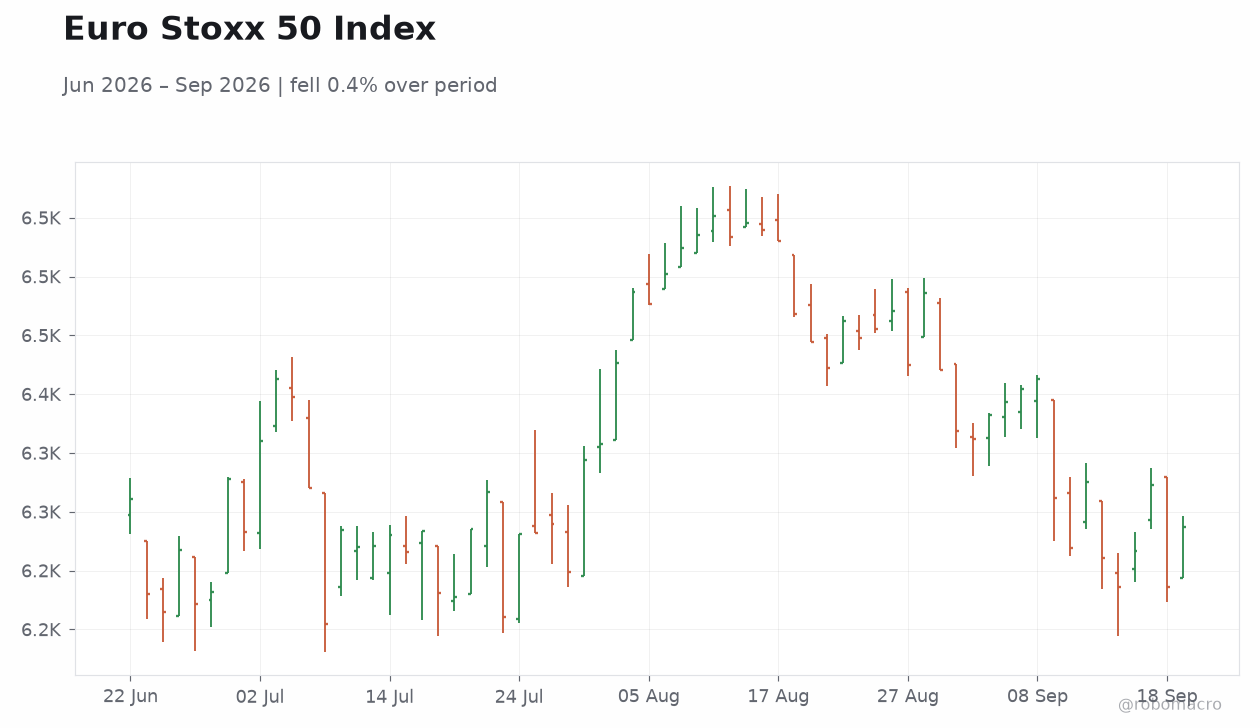
| Euro Stoxx 50 | 6,286.21 | +0.80% |
| DAX | 25,304.06 | -1.60% |
| CAC 40 | 8,105.73 | +0.50% |
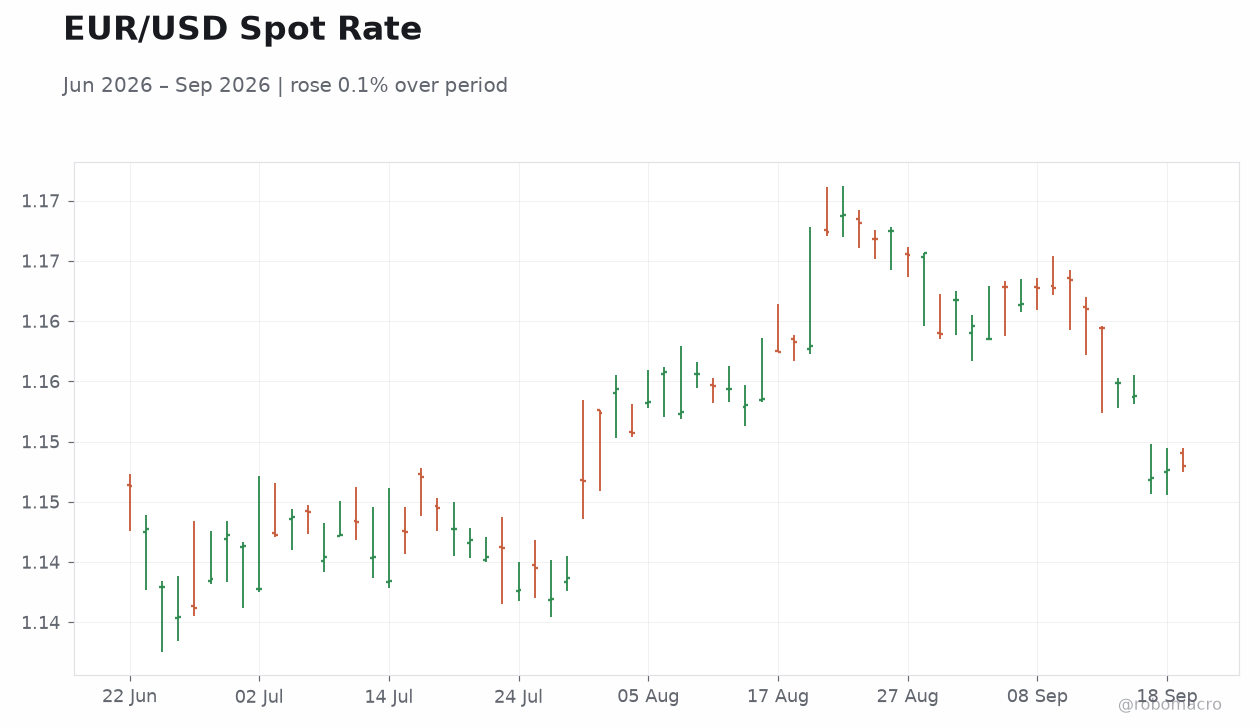
| EUR/USD | 1.15 | +0.02% |
| EUR/GBP | 0.86 | -0.17% |
| EUR/JPY | 180.39 | +0.67% |
| Gold | 4,390.30 | -0.78% |
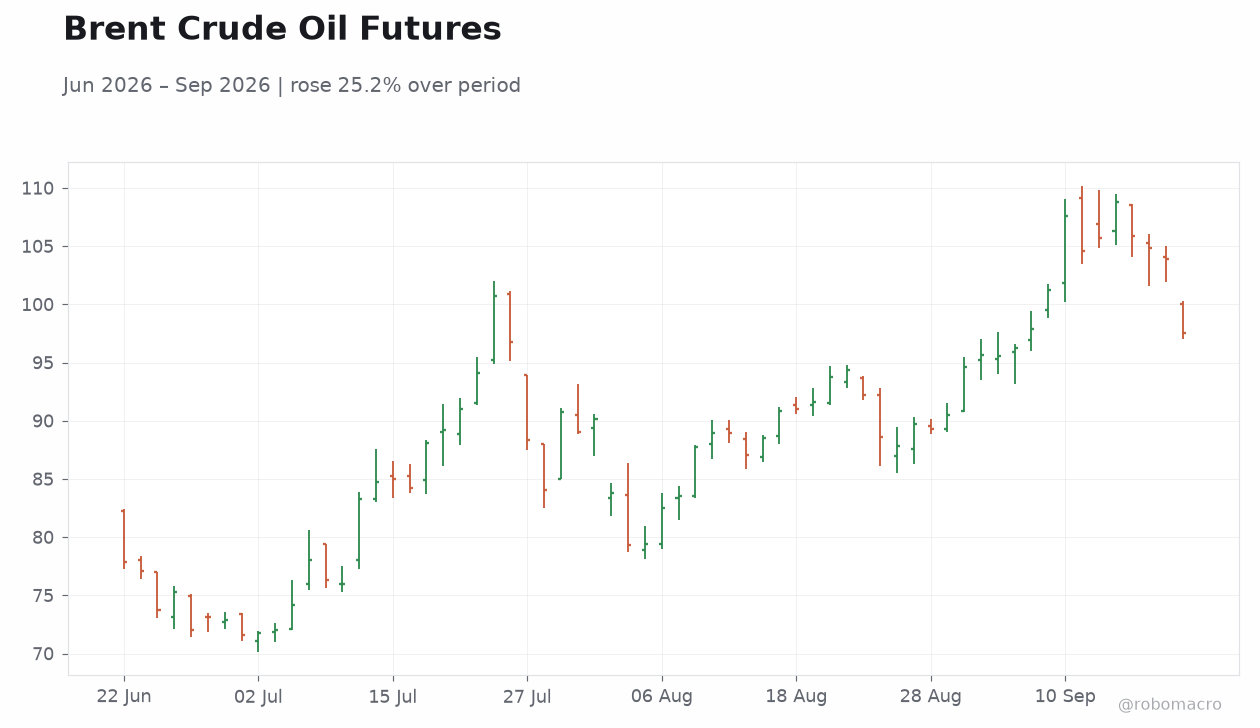
| Brent Crude | 97.64 | -6.00% |
| Bitcoin | 81,500.99 | +0.33% |
| German 2Y Bund | 3.17% | +13 bp |
| German 10Y Bund | 3.56% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
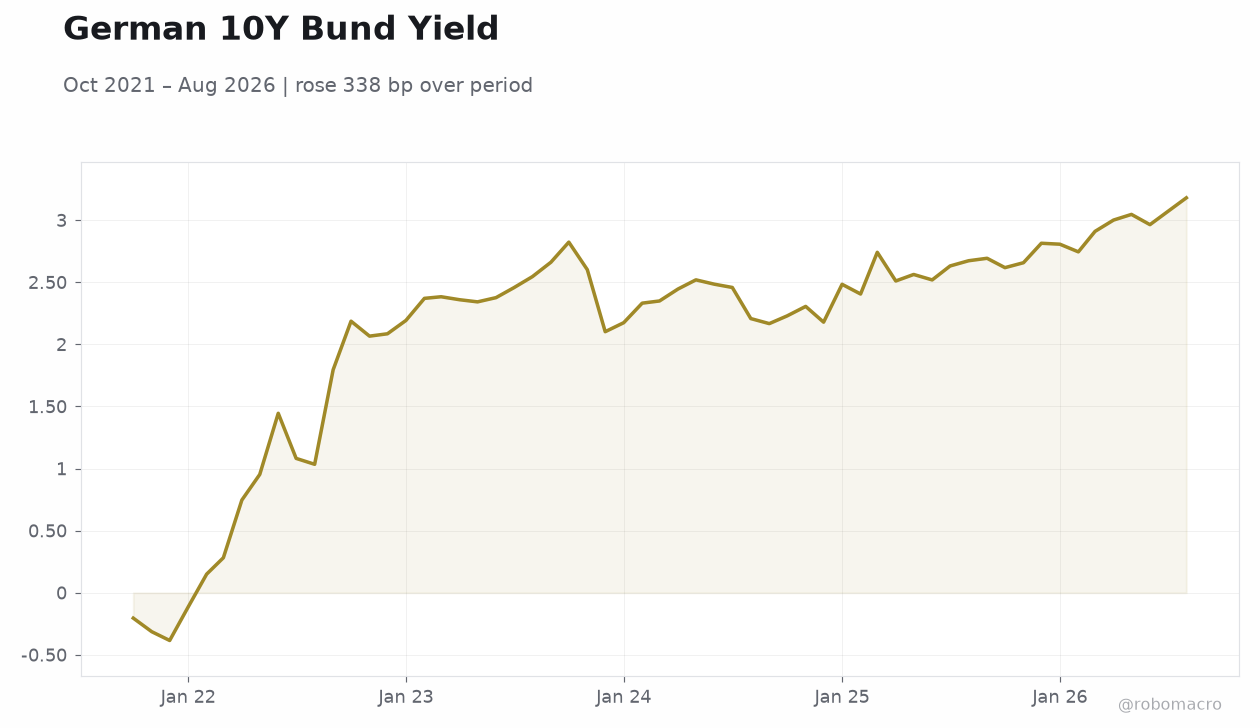 German 10Y Bund Yield | Type: macro_line | %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.2043,2.085,2.332,2.51,2.964,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Consumer Confidence Index | -34 | - | 20:30 |
| Trade Balance | -7,690m | - | 00:00 |
| S&P Global Composite PMI Flash | 48.50 | - | 23:15 |
| S&P Global Manufacturing PMI Flash | 51.10 | 50.90 | 23:15 |
| S&P Global Services PMI Flash | 48 | 48.50 | 23:15 |
| S&P Global Manufacturing PMI Flash | 54.30 | 54.50 | 23:30 |
| S&P Global Composite PMI Flash | 51.80 | - | 23:30 |
| S&P Global Services PMI Flash | 49.70 | 50 | 23:30 |
| Business Confidence | 103 | 101 | 22:45 |
| Consumer Confidence Index | 86 | 85 | 22:45 |
- German Chancellor Merz labels regional election defeats a disaster yet vows reform continuity
- France debt reaches 119% of GDP with Scope downgrade and negative DBRS outlook
- German 2Y Bund yield jumps 13 bp to 3.17% while Euro Stoxx 50 rises 0.80%
Yesterday's Recap
No Eurozone data releases occurred on 20 September across Germany, France, Italy, Spain or the Netherlands. Equities closed mixed as Euro Stoxx 50 gained 0.80% to 6,286.21 while DAX fell 1.60% to 25,304.06 and CAC 40 added 0.50%. German 2Y Bund yield rose 13 bp to 3.17% and 10Y yield increased 5 bp to 3.56%.
Brent crude plunged 6.00% to 97.64 while EUR/USD edged 0.02% higher to 1.15. Chancellor Friedrich Merz described his CDU party’s heavy losses in Berlin and Mecklenburg-Western Pomerania elections as a disaster but pledged to advance reforms. Germany requested EU tariffs on surging Chinese hybrid imports to safeguard auto-sector jobs.
The Day Ahead
Netherlands Consumer Confidence Index prints today. Spain Trade Balance and French S&P Global Composite, Manufacturing and Services PMI Flash releases follow on 22 September. German S&P Global Manufacturing PMI Flash, carrying high impact, is due the same day alongside Composite and Services readings.
France Business and Consumer Confidence indices appear on 23 September. Germany IFO Business Climate Level and GfK Consumer Confidence close the week on 24 September. Markets will scrutinise German manufacturing and IFO prints for signals on industrial momentum and rate-path expectations.
The Netherlands reading at 20:30 ET offers the first fresh sentiment gauge after the weekend elections.
Other Economic Notes
France’s draft 2027 budget aims to comply with EU spending guidelines despite the highest projected deficit in the euro area. Scope Ratings downgraded France while DBRS placed the sovereign on negative outlook, citing political and fiscal risks. German authorities seek tighter EU rules on Chinese hybrid-vehicle imports after volumes rose sharply from 3,800 to 50,000 units.
Broader euro-area inflation stood at 3.20% YoY in August and unemployment at 6.40% in July, leaving limited room for policy easing. Political instability in Germany and fiscal slippage in France continue to weigh on regional sentiment. The French debt-to-GDP ratio at 119% revives concerns last seen in 2012.