Eurozone Macro Daily(Beta Mode)
Eurozone Growth Signals Strengthen, Equities Slip
Market Snapshot
| Asset | Level | Change |
|---|---|---|
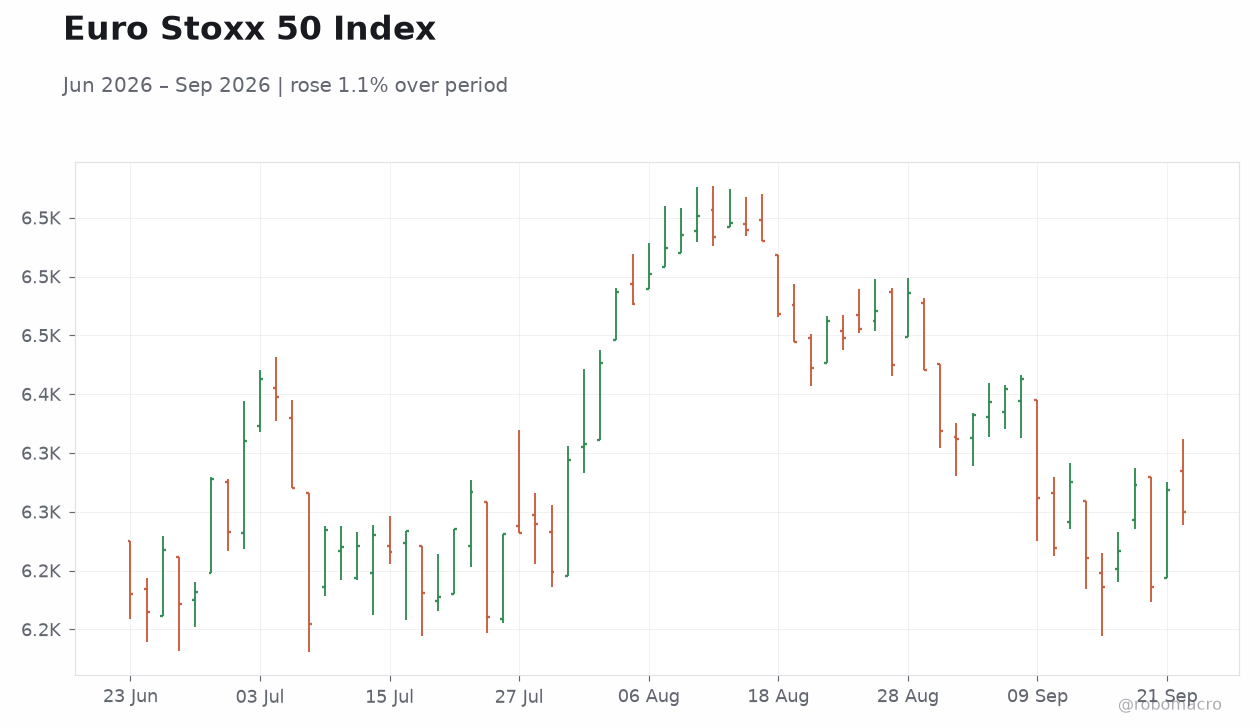
| Euro Stoxx 50 | 6,299.82 | -0.29% |
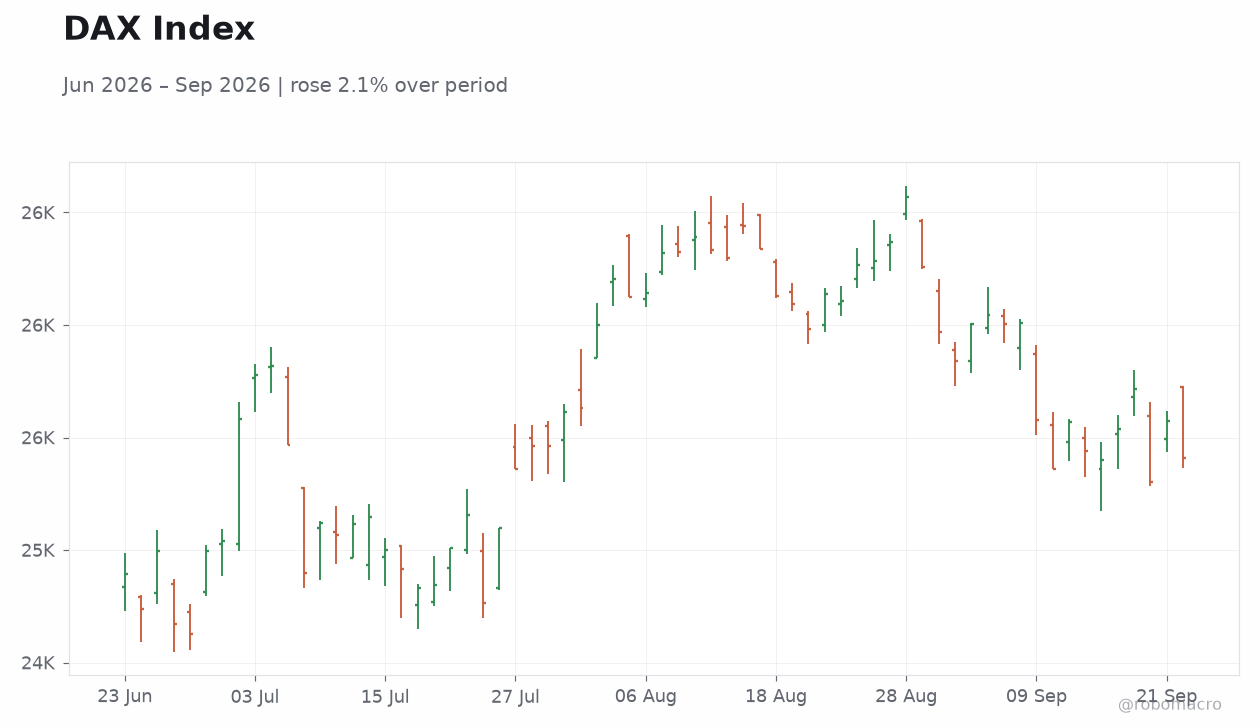
| DAX | 25,410.63 | -0.77% |
| CAC 40 | 8,123.41 | -0.19% |
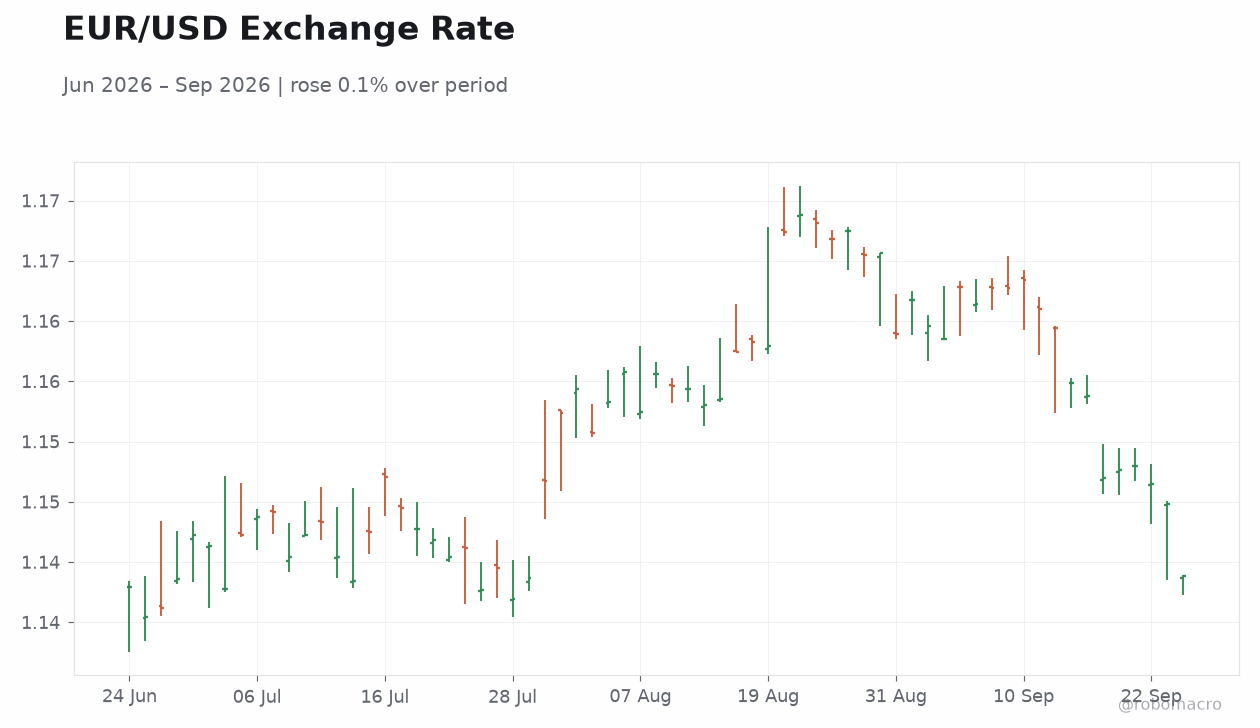
| EUR/USD | 1.14 | -0.53% |
| EUR/GBP | 0.86 | +0.21% |
| EUR/JPY | 179.83 | -0.24% |
| Gold | 4,323.30 | +0.11% |
| Brent Crude | 97.47 | -5.44% |
| Bitcoin | 84,172.71 | -2.32% |
| German 2Y Bund | 3.23% | +1 bp |
| German 10Y Bund | 3.52% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
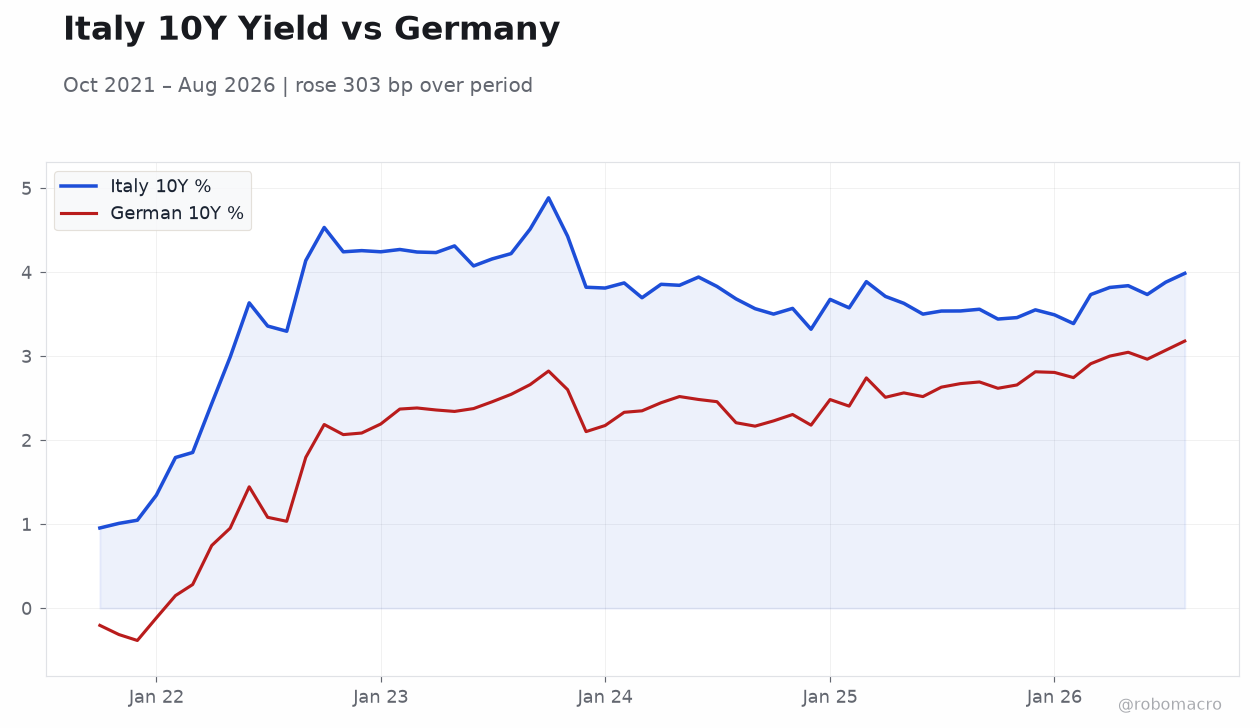
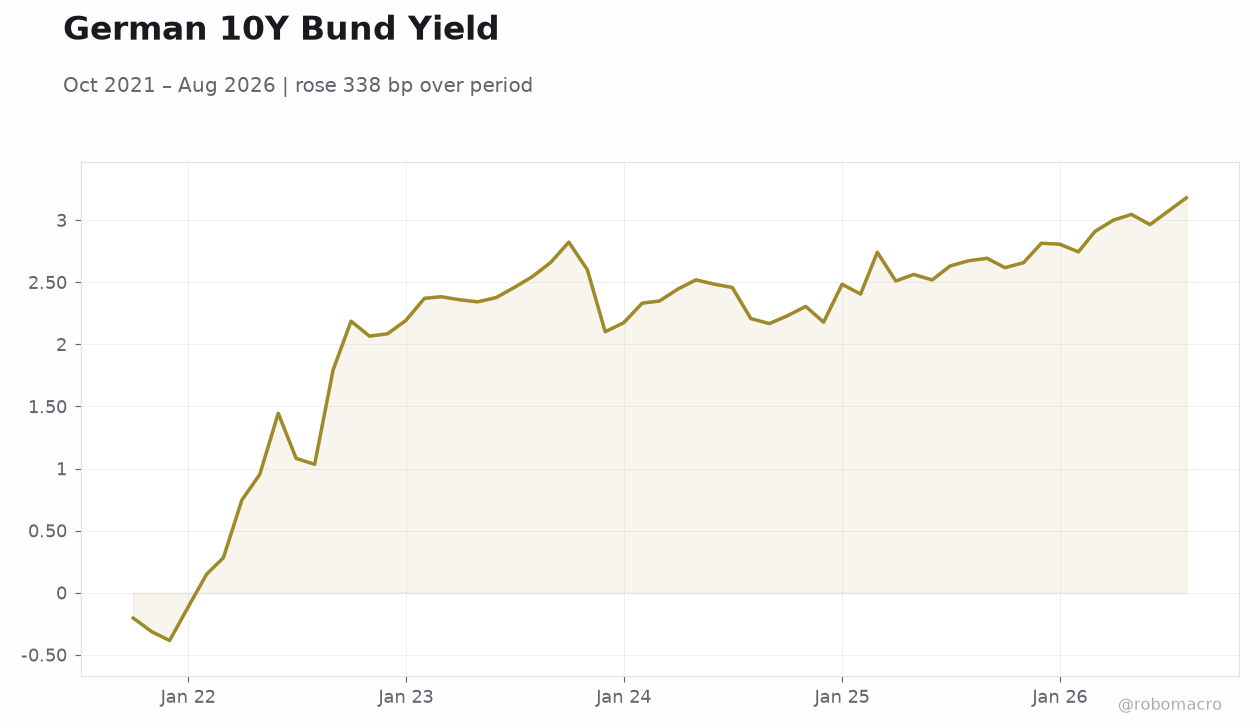 German 10Y Bund Yield | Type: macro_line | %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.2043,2.085,2.332,2.51,2.964,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Eurozone private sector growth reaches 41-month high driven by services acceleration
- DAX falls 0.77% while German 10Y Bund yield holds at 3.52%
- EUR/USD drops 0.53% to 1.14 amid Brent Crude decline of 5.44%
Yesterday's Recap
No macroeconomic data releases occurred across Germany, France, Italy, Spain or the Netherlands on 23 September. European equities closed lower with the Euro Stoxx 50 declining 0.29% to 6,299.82 and the CAC 40 easing 0.19% to 8,123.41. The DAX posted the largest drop at 0.77% to 25,410.63.
Brent Crude fell sharply to 97.47 while gold edged up 0.11% to 4,323.30. The euro weakened against the dollar with EUR/USD closing at 1.14. German yields remained stable as the 2Y Bund rose 1 bp to 3.23% and the 10Y Bund held at 3.52%.
Greece reported tourism receipts rising 12% to €13.5 billion in the first seven months with arrivals exceeding 20 million. These moves occurred against a backdrop of steady policy expectations and limited new information from official sources.
The Day Ahead
No economic releases or ECB events are scheduled for 24 September across the euro area. Markets will monitor any follow-through from recent private sector expansion data. Attention may turn to ongoing fiscal developments in France where debt costs continue to pressure yields.
German and Dutch innovation agencies begin collaboration on AI chip design. Broader focus remains on external factors including oil price volatility and global growth signals. Investors will also watch for any updates on Greece’s tourism-driven current account improvement and potential spillovers from China’s data-centre expansion plans into European markets.
Other Economic Notes
Germany issued its first explicit commitment to phase out fossil fuels by 2045 marking a policy shift for Europe’s largest economy. France faces renewed budget pressures as deficit concerns weigh on sovereign bonds and government stability. Greece continues to benefit from strong tourism inflows that support its external accounts.
Private sector momentum across the euro area reached the highest level since April 2023 with German industrial rebound contributing notably. These developments occur against a backdrop of steady ECB policy settings. The absence of fresh domestic data leaves the recent services-led expansion as the dominant narrative supporting euro-area resilience.