Eurozone Macro Daily(Beta Mode)
Inflation Tops Forecasts in Key Eurozone Economies
Market Snapshot
| Asset | Level | Change |
|---|---|---|
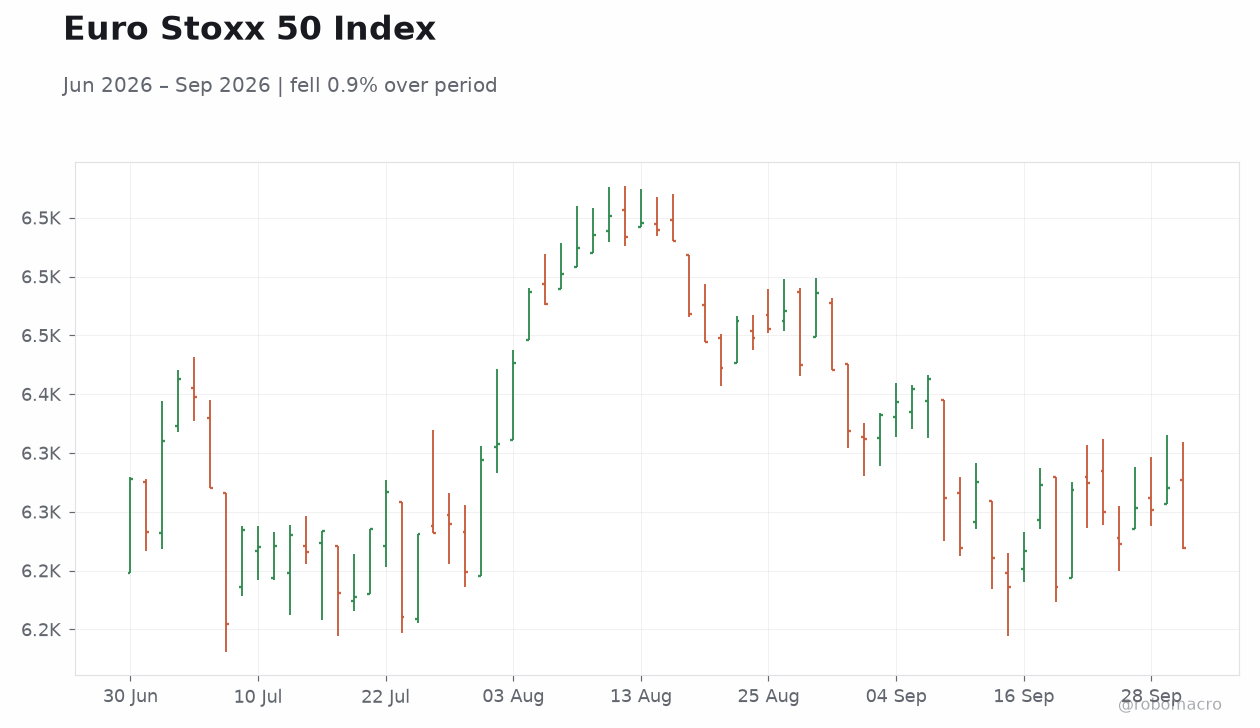
| Euro Stoxx 50 | 6,269.02 | -0.81% |
| DAX | 25,231.72 | -0.66% |
| CAC 40 | 7,964.51 | -0.89% |
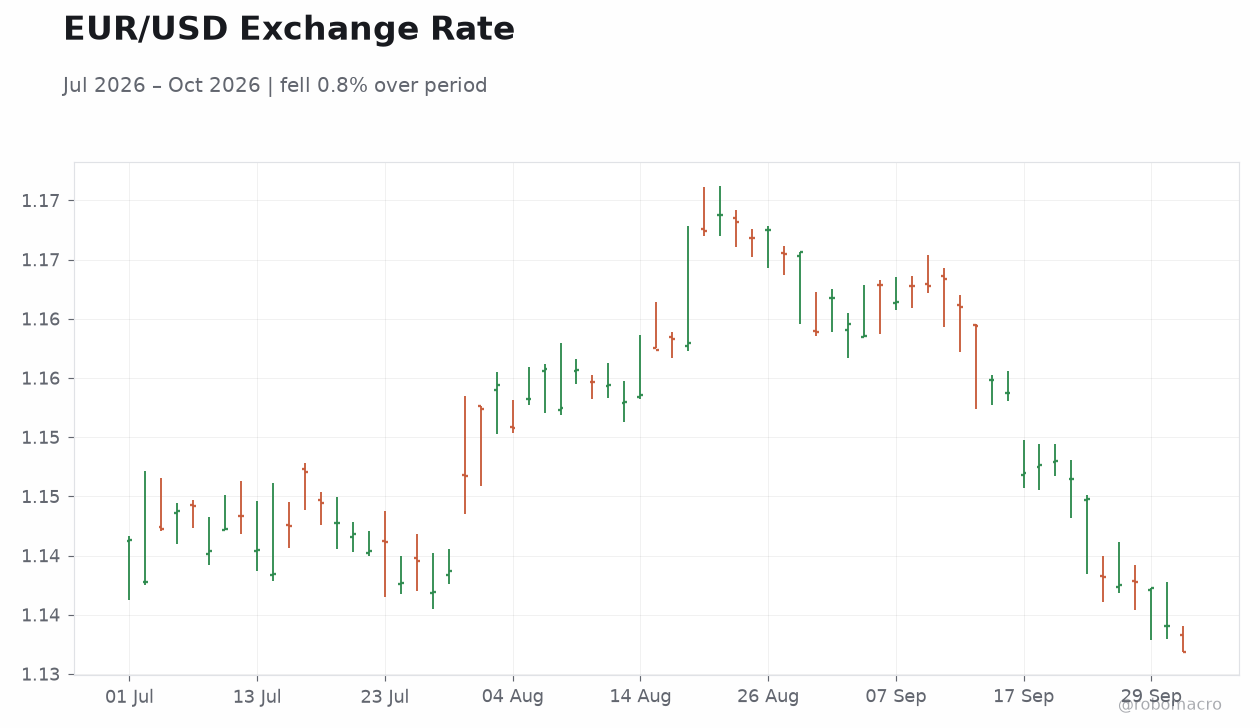
| EUR/USD | 1.13 | -0.16% |
| EUR/GBP | 0.85 | -0.35% |
| EUR/JPY | 179.16 | +0.37% |
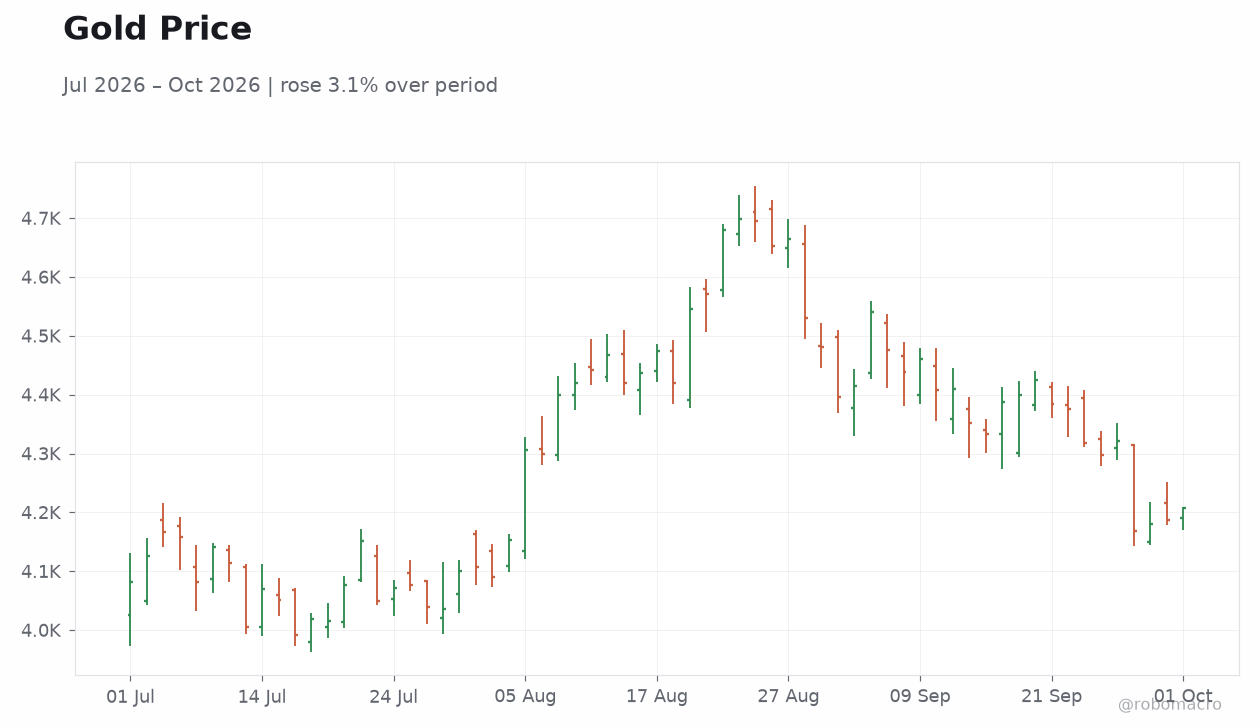
| Gold | 4,207.50 | +0.50% |
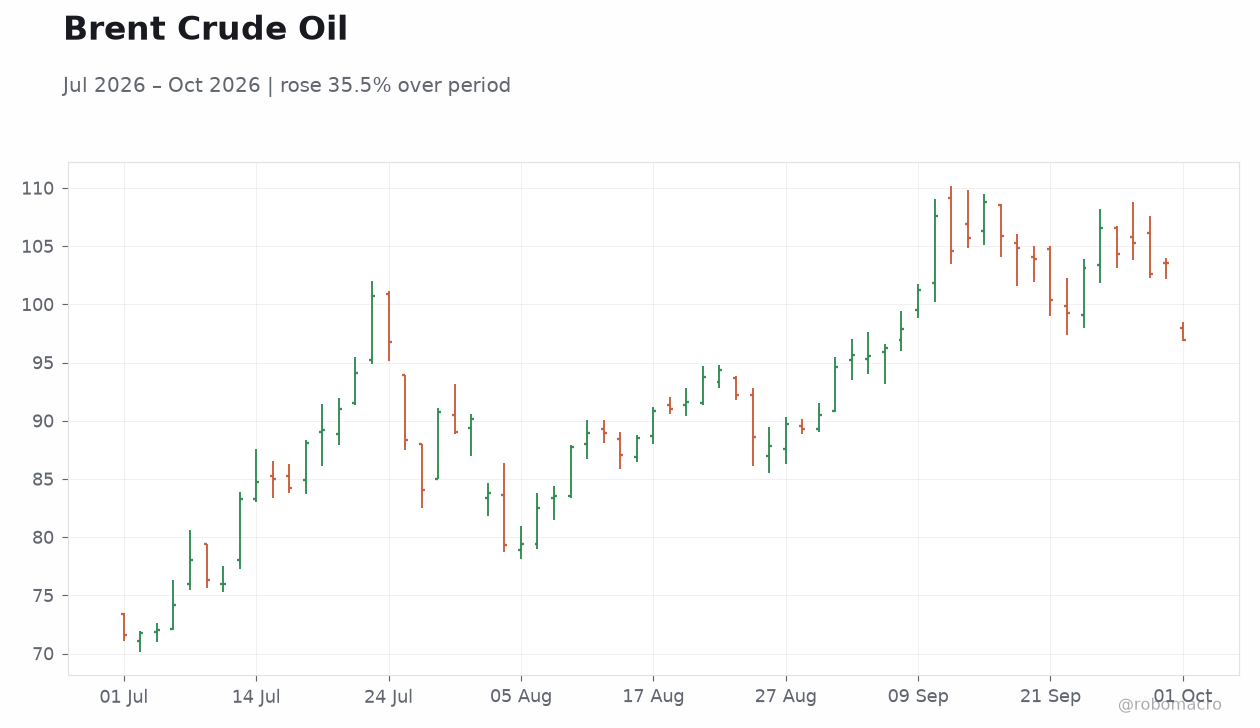
| Brent Crude | 96.96 | -6.35% |
| Bitcoin | 84,043.14 | +0.50% |
| German 2Y Bund | 3.28% | -2 bp |
| German 10Y Bund | 3.69% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Month-over-Month Preliminary | 0.70 | - | 0.30 |
| Inflation Rate Year-over-Year Preliminary | 4.30 | 4.70 | 4.90 |
| Unemployment Benefit Claims | 21,500 | - | -61,300 |
| Business Confidence Index | -3.80 | - | -1.60 |
| Retail Sales Month-over-Month | -3.20 | 1.50 | 1.30 |
| Retail Sales Year-over-Year | -2.20 | 0.10 | -0.40 |
| Inflation Rate Year-over-Year Preliminary | 2.40 | 2.80 | 3 |
| Inflation Rate Month-over-Month Preliminary | 0.70 | -0.60 | -0.30 |
| Headline Unemployment Rate | 6.40 | 6.40 | 6.40 |
| Unemployed Persons Level | 3m | - | 3.0m |
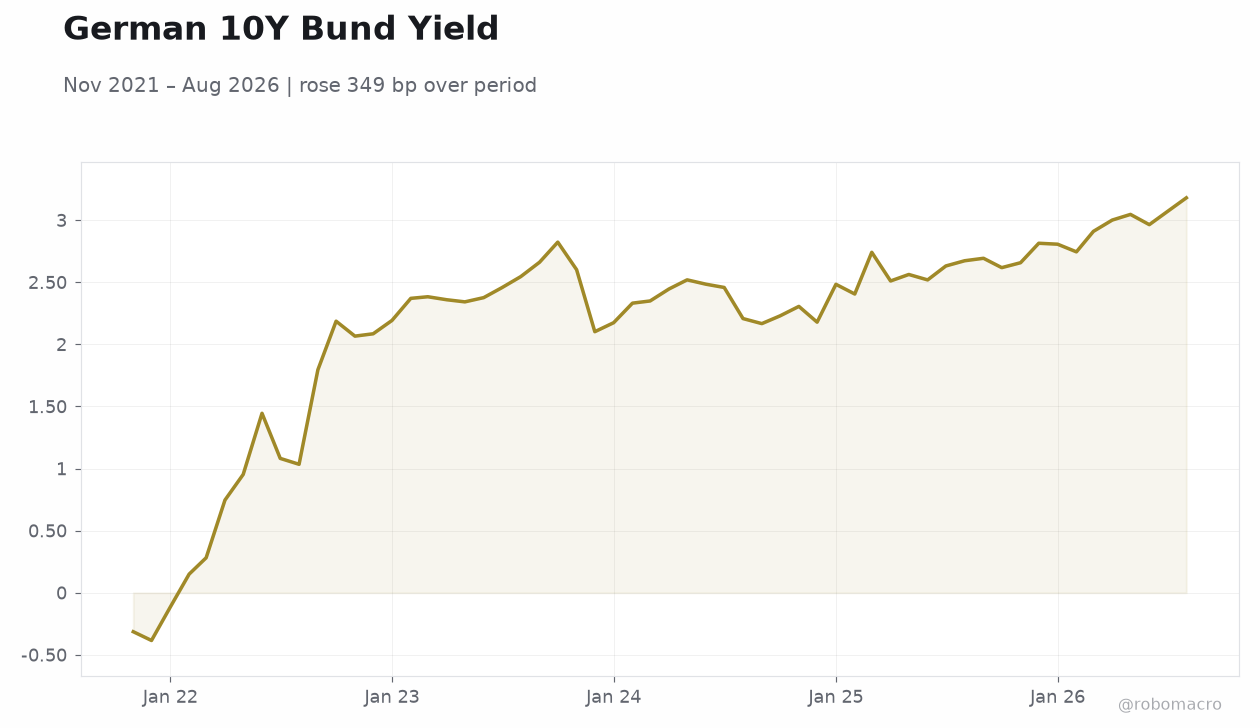 German 10Y Bund Yield | Type: macro_line | Yield %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| S&P Global Manufacturing PMI Index | 49.50 | 50.10 | 23:15 |
| S&P Global Manufacturing PMI Index | 49.60 | 50 | 23:45 |
| Headline Unemployment Rate | 5.80 | 5.70 | 00:00 |
| Inflation Rate Year-over-Year Preliminary | 3.30 | - | 20:30 |
| Unemployment Level Change | 44,419 | 17,600 | 23:00 |
| Retail Sales Month-over-Month | -0.40 | -0.10 | 00:00 |
- Spanish, French and Italian September CPI YoY all exceeded consensus, with Spain at 4.9%, France at 3.0% and Italy at 4.2%.
- German retail sales rose 1.3% MoM but fell 0.4% YoY while unemployment edged higher by 12,000 persons.
- Euro Stoxx 50 fell 0.81% and German 10-year Bund yields rose 6 bp to 3.69% as sticky inflation tempered rate-cut expectations.
Yesterday's Recap
Spanish preliminary September inflation rose 0.3% MoM and 4.9% YoY, beating the 4.7% consensus. French inflation printed 3.0% YoY versus 2.8% expected, while Italian CPI jumped to 4.2% YoY against a 3.8% forecast. German retail sales increased 1.3% MoM but declined 0.4% YoY, and the unemployment rate held at 6.4% even as unemployed persons rose by 12,000.
Italian business confidence improved to 91.9 while consumer confidence fell to 91.2. Spanish business confidence rose to -1.6. Equity markets closed lower, with the Euro Stoxx 50 down 0.81% to 6,269.02, the DAX off 0.66% and the CAC 40 down 0.89%.
The German 10-year Bund yield climbed 6 bp to 3.69% while the 2-year yield eased 2 bp to 3.28%. EUR/USD slipped 0.16% to 1.13 amid the mixed inflation and growth signals. Brent Crude plunged 6.35% to 96.96 while gold rose 0.50% to 4,207.50.
The Day Ahead
Spain and Italy S&P Global Manufacturing PMI releases are scheduled for today, with consensus readings near 50.1 and 50.0 respectively. Market participants will monitor any follow-up commentary from national statistics offices on the September inflation prints. Energy-price developments remain in focus after Brent crude fell 6.35% to 96.96.
Fixed-income traders will watch for any shifts in French-German yield spreads ahead of budget discussions in Paris. No major ECB speeches are listed on the calendar. Broader commodity weakness may ease imported inflation pressures over coming months but has not yet altered market pricing for ECB policy.
Other Economic Notes
Hotter-than-expected inflation readings across Germany, France, Italy and Spain reinforce the view that energy costs continue to drive price pressures. Chancellor Friedrich Merz met Siemens and Deutsche Bank CEOs under the “Made for Germany” initiative, lifting total investment pledges to €850 billion by 2028. The government directed state-owned SEFE to increase natural-gas storage ahead of winter.
French borrowing costs have risen sharply, with 10-year yields approaching 4.8% and prompting warnings of credit degradation. ↓ p.2