Eurozone Macro Daily(Beta Mode)
Bundesbank Lifts German Growth View to 1%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
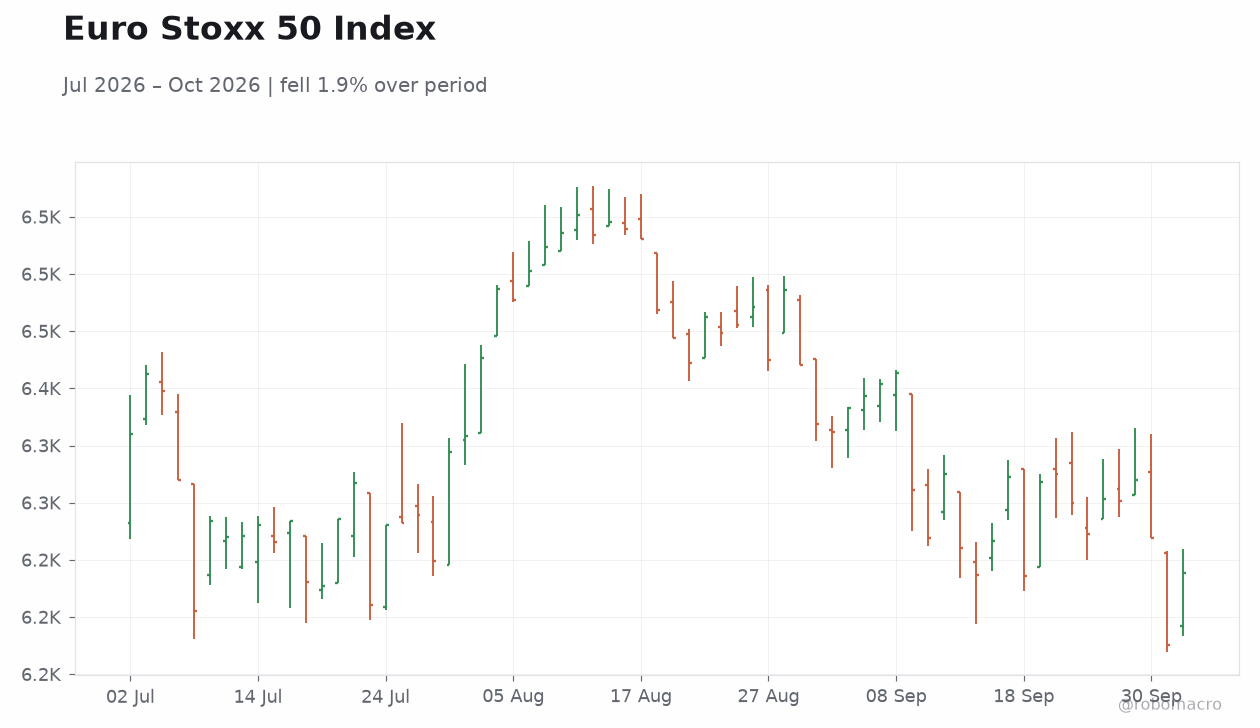
| Euro Stoxx 50 | 6,238.50 | +1.02% |
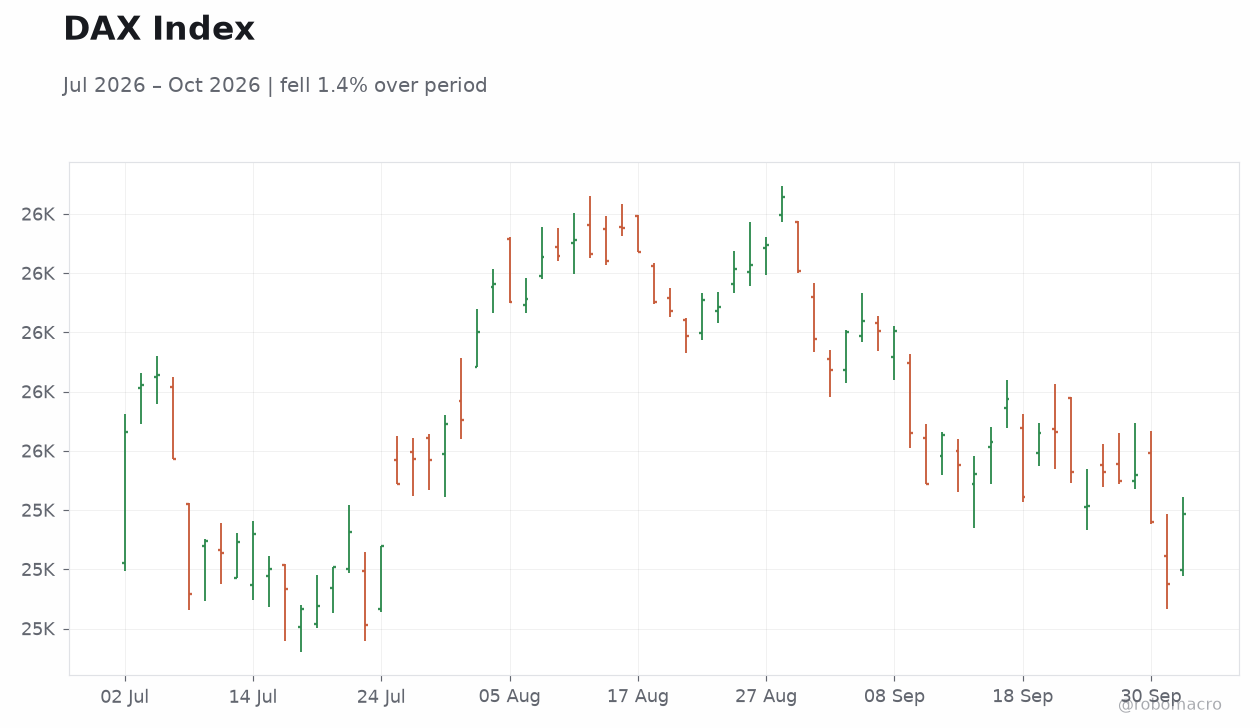
| DAX | 25,231.20 | +1.17% |
| CAC 40 | 7,897.19 | +0.79% |
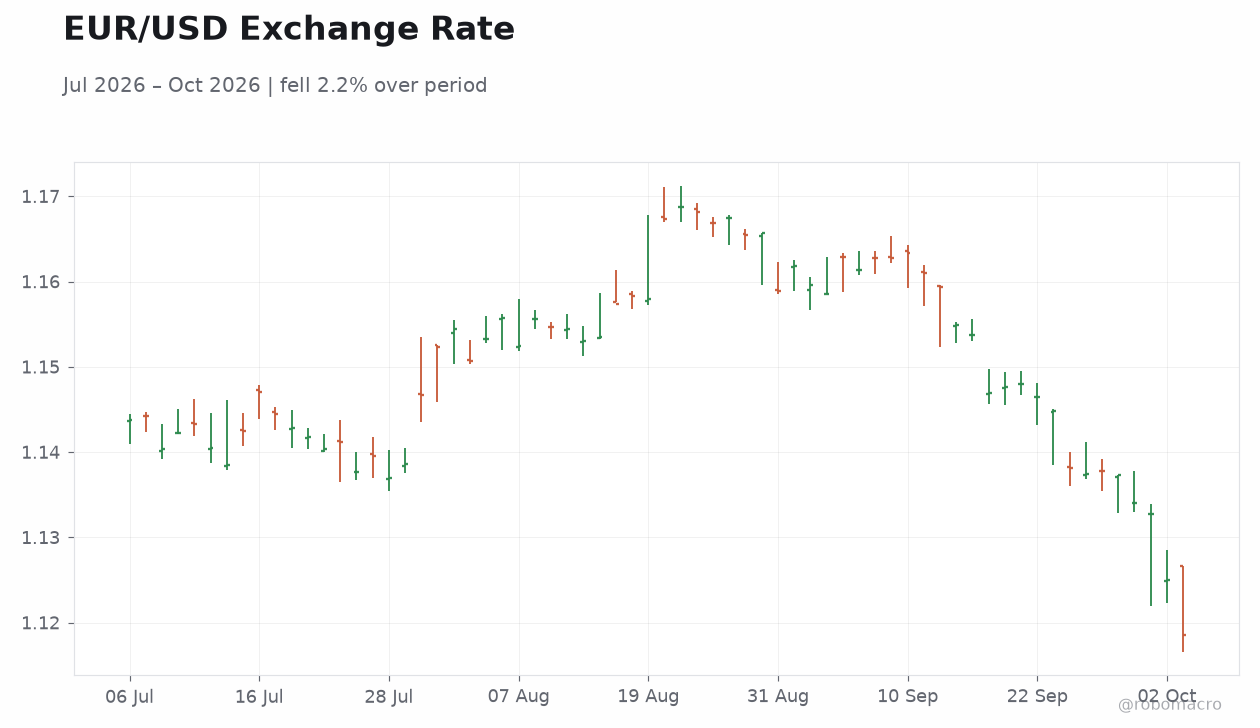
| EUR/USD | 1.12 | -0.56% |
| EUR/GBP | 0.85 | -0.65% |
| EUR/JPY | 177.62 | -0.47% |
| Gold | 4,161.20 | -0.03% |
| Brent Crude | 101.68 | -0.56% |
| Bitcoin | 85,525.78 | +0.90% |
| German 2Y Bund | 3.28% | -2 bp |
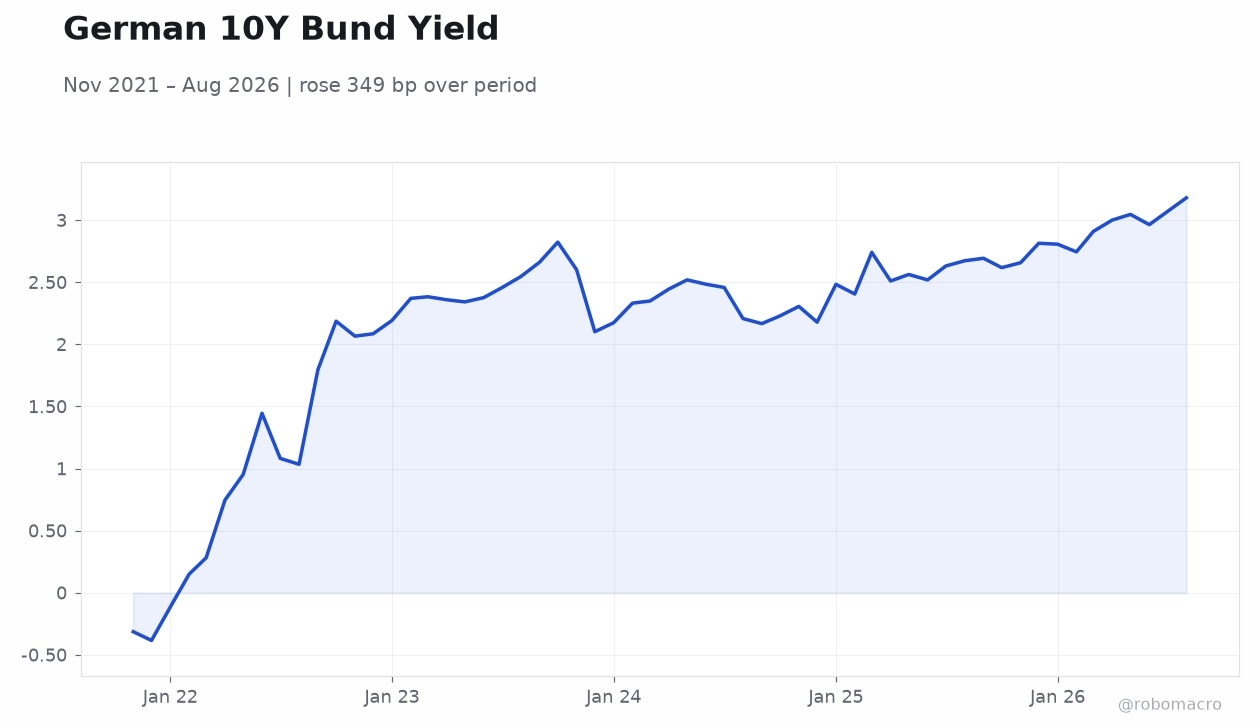
| German 10Y Bund | 3.69% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
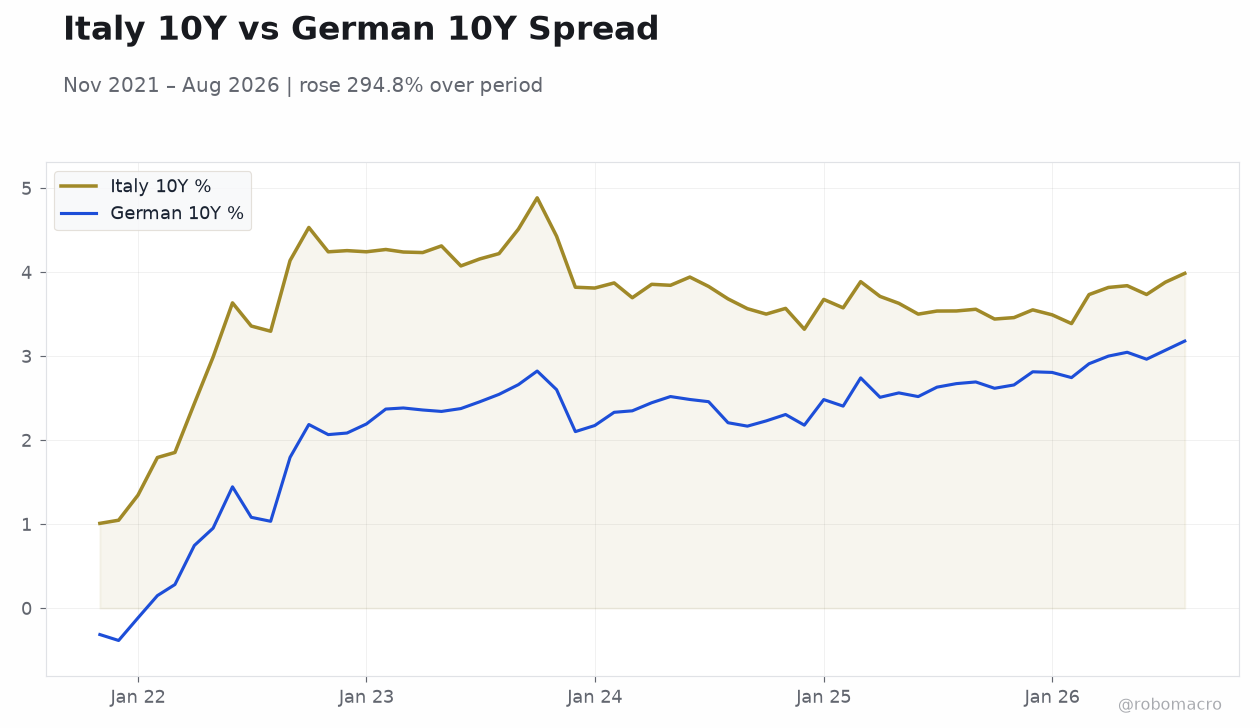 Italy 10Y vs German 10Y Spread | Type: macro_line | Italy 10Y %: 3.986 (2026-08-01) | Range: 1.01–4.885 | Trend(6pt): 1.01,4.243,3.696,3.629,3.881,3.986 | German 10Y %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| S&P Global Services PMI | 57.80 | 57.10 | 03:15 |
| S&P Global Services PMI | 55.20 | - | 03:45 |
| Factory Orders Month-over-Month | 2.50 | -0.90 | 02:00 |
| Industrial Production Month-over-Month | -0.40 | 0.20 | 02:45 |
| Industrial Production Month-over-Month | -1.10 | 1.40 | 02:00 |
| Trade Balance | -6,700m | -6,500m | 02:45 |
| Trade Balance | 21,300m | 19,200m | 02:00 |
| Exports Month-over-Month | -0.80 | - | 02:00 |
| Industrial Production Month-over-Month | 0.70 | 0 | 04:00 |
- Bundesbank raises 2026 German growth forecast to 1%, citing stronger momentum.
- French bond yields climb on fiscal slippage and political gridlock risks.
- Eurozone equities advance while EUR weakens across major crosses on divergent yields.
Yesterday's Recap
European equities posted solid gains on 4 October with no scheduled data releases across member states. The Euro Stoxx 50 rose 1.02% to 6,238.50, the DAX climbed 1.17% to 25,231.20 and the CAC 40 advanced 0.79% to 7,897.19. EUR/USD fell 0.56% to 1.12, EUR/GBP slipped 0.65% to 0.85 and EUR/JPY declined 0.47% to 177.62.
The German 2-year Bund yield eased 2 bp to 3.28% while the 10-year yield rose 6 bp to 3.69%. Bundesbank President Joachim Nagel stated German output could expand about 1% this year, roughly double earlier projections. French fiscal concerns weighed on the euro, with reports highlighting deepening bond-market stress and investor exits amid political impasse.
The Day Ahead
Spain’s S&P Global Services PMI is due at 03:15 ET with consensus at 57.1 versus 57.8 previously. Italy’s equivalent print follows at 03:45 ET. These flash readings will supply the first October services-sector signals for the two largest southern economies.
A downside surprise could pressure EUR crosses and support Bunds, while an upside beat would likely lift equities and peripheral spreads. No other high-impact Eurozone releases are scheduled for 5 October.
Other Economic Notes
Germany’s upgraded growth outlook reflects resilient domestic demand and export recovery despite earlier headwinds. France faces mounting pressure after unveiling a €54 billion cost-cutting budget for 2027 amid protests and rising borrowing costs that echo prior euro-area debt strains. Broader euro-area inflation reached 3.80% YoY at end-September, keeping the ECB on alert even as unemployment held at 6.40% in August.
Energy prices remain the dominant inflation driver across the currency union.
Global Macro News
Brent crude declined 0.56% to 101.68, easing imported inflation risks for euro-area importers. Gold held near 4,161.20 while Bitcoin rose 0.90% to 85,525.78, reflecting risk-on sentiment outside traditional assets. US disappointment over G20 lack of consensus on overproduction added to global commodity volatility.
↓ p.2