Eurozone Macro Daily(Beta Mode)
German Orders Slump, French Spreads in Focus
Market Snapshot
| Asset | Level | Change |
|---|---|---|
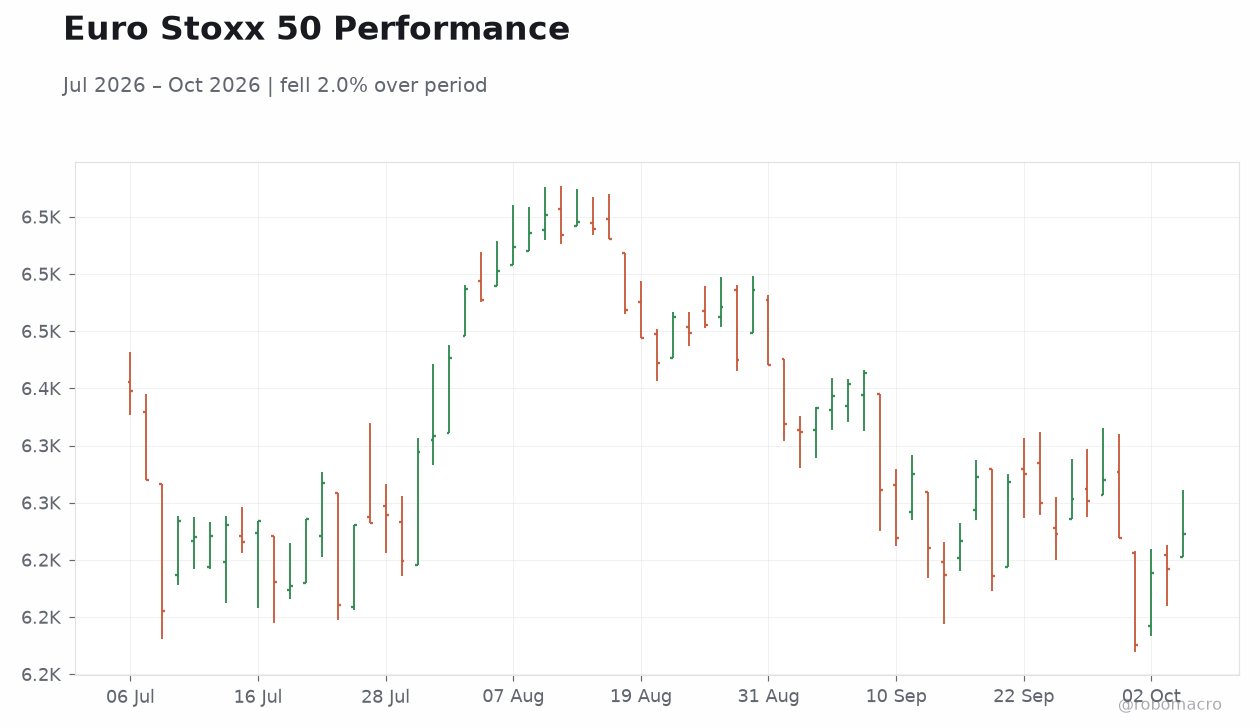
| Euro Stoxx 50 | 6,272.23 | +0.48% |
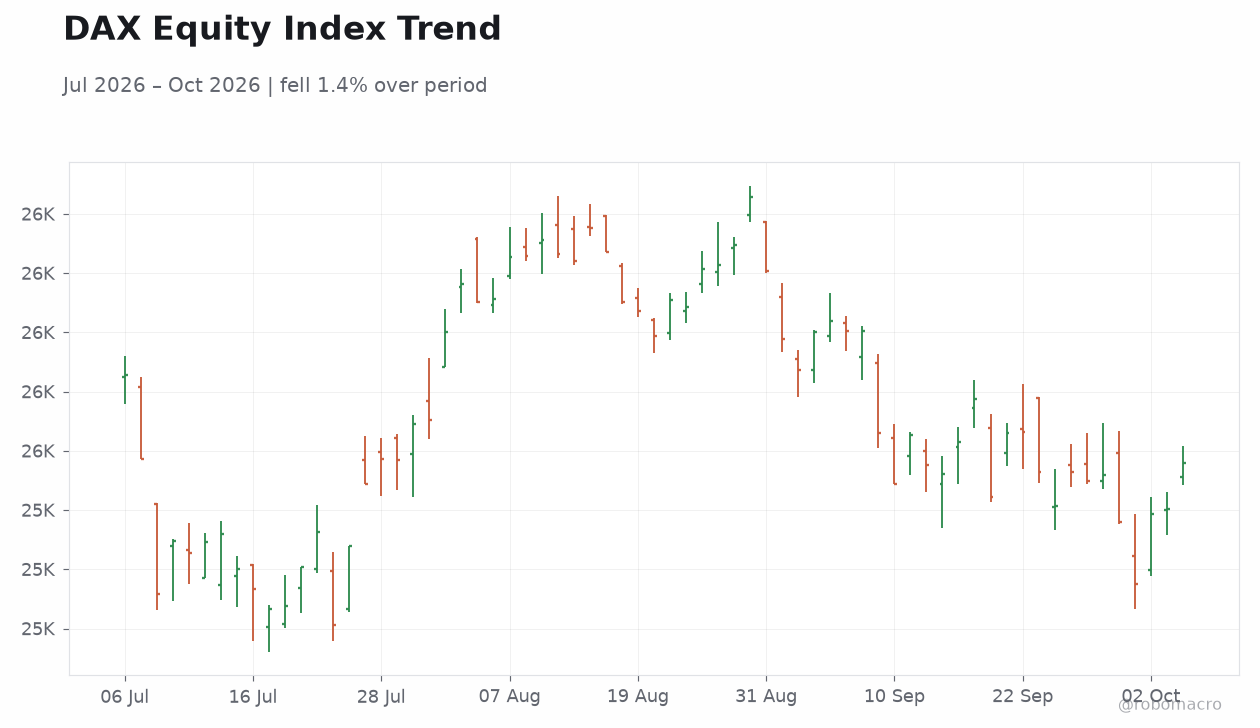
| DAX | 25,467.10 | +0.84% |
| CAC 40 | 7,865.07 | +0.40% |
| EUR/USD | 1.12 | +0.17% |
| EUR/GBP | 0.85 | -0.09% |
| EUR/JPY | 177.94 | +0.43% |
| Gold | 4,165.60 | -0.51% |
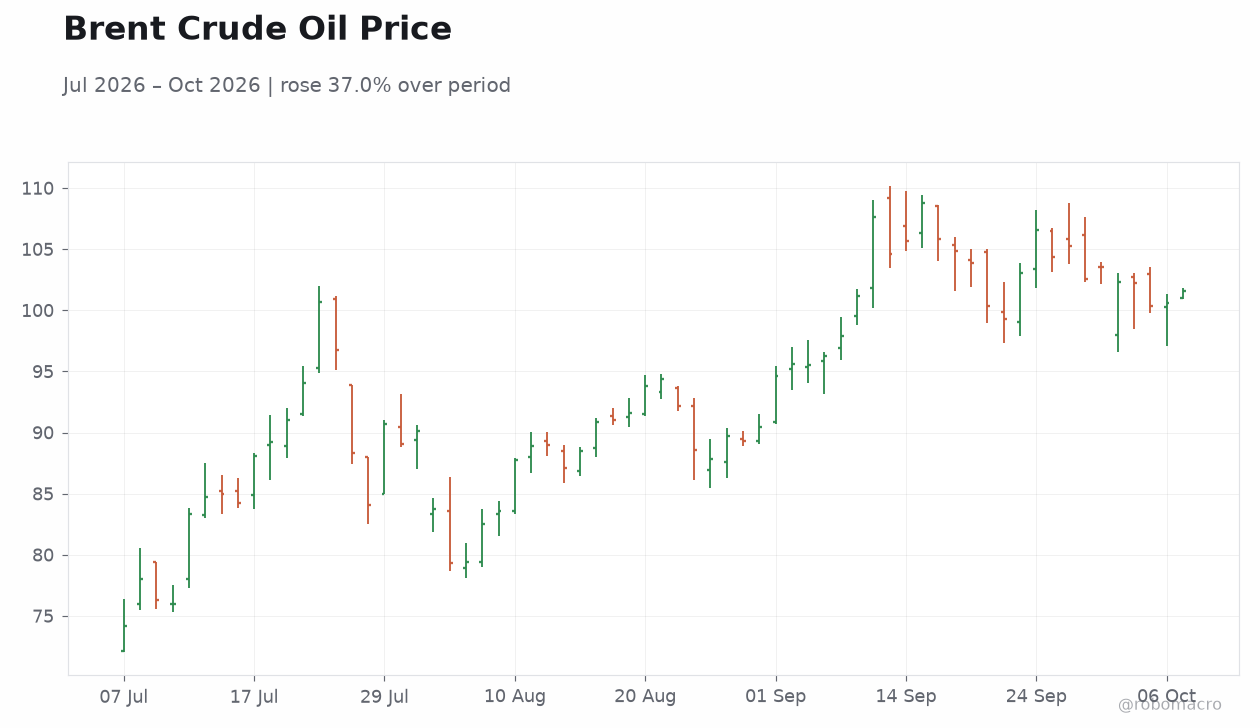
| Brent Crude | 101.59 | +1.00% |
| Bitcoin | 84,081.76 | -1.99% |
| German 2Y Bund | 3.08% | +6 bp |
| German 10Y Bund | 3.49% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| S&P Global Services PMI | 57.80 | 56.80 | 58.30 |
| S&P Global Services PMI | 55.20 | - | 51.70 |
| Factory Orders Month-over-Month | 3.20 | -1 | -10.60 |
| Industrial Production Month-over-Month | -0.60 | 0.30 | -0.30 |
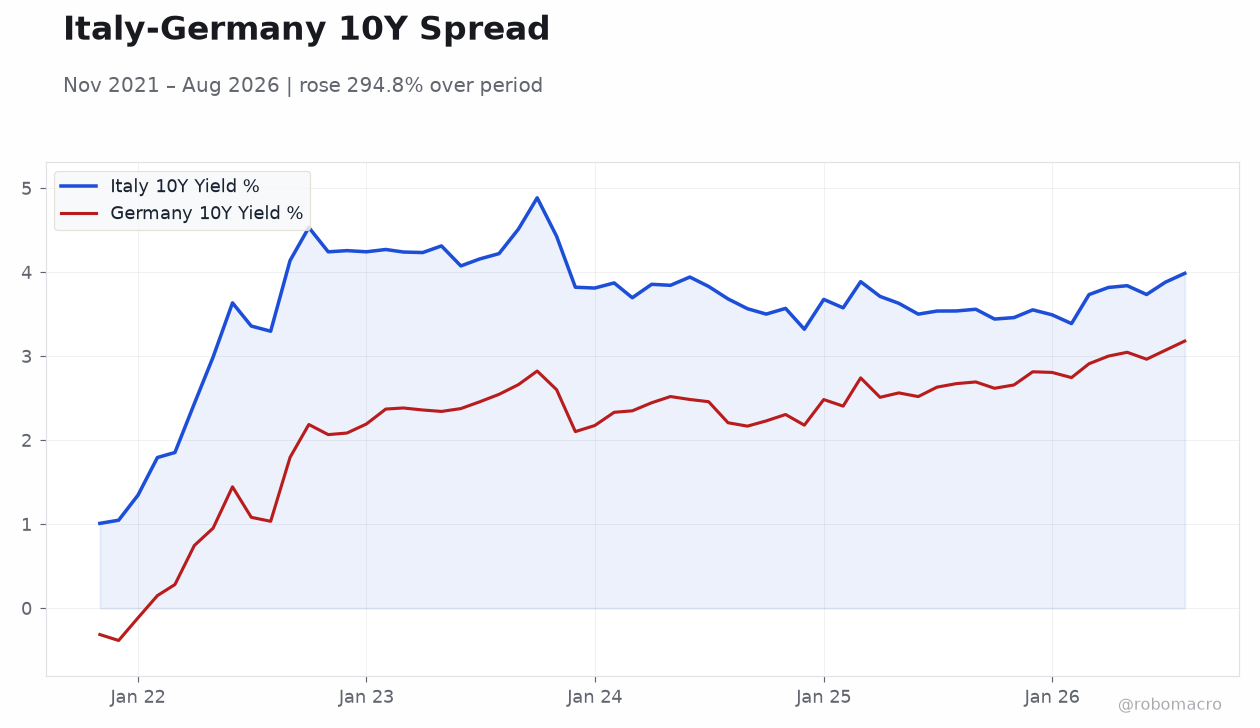
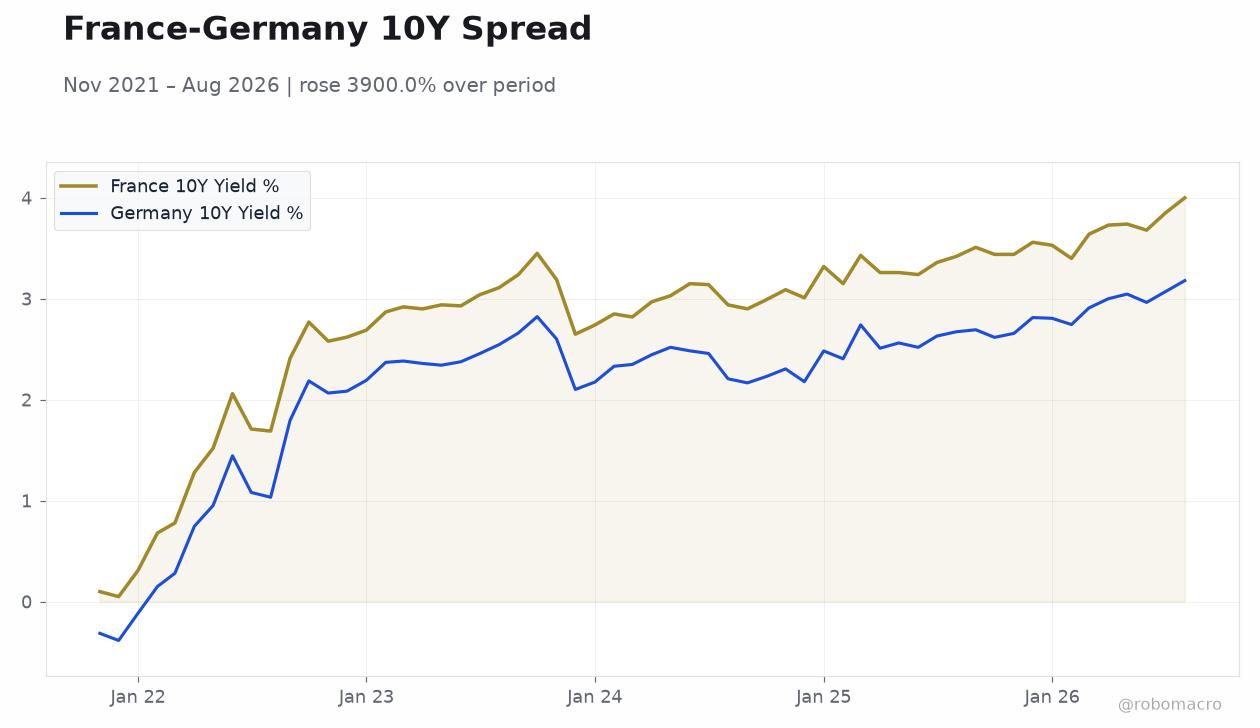 France-Germany 10Y Spread | Type: macro_line | France 10Y Yield %: 4 (2026-08-01) | Range: 0.05–4 | Trend(6pt): 0.1,2.69,2.82,3.26,3.85,4 | Germany 10Y Yield %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Industrial Production Month-over-Month | -1.10 | 0.50 | 02:00 |
| Trade Balance | -6,700m | -6,500m | 02:45 |
| Trade Balance | 21,300m | 19,000m | 02:00 |
| Exports Month-over-Month | -0.80 | - | 02:00 |
| Industrial Production Month-over-Month | 0.70 | 0 | 04:00 |
- German factory orders plunged 10.6% m/m in September, far below the -1.0% consensus, reviving concerns over the manufacturing recovery.
- The France-Germany 10-year spread widened to its widest since the euro crisis as French political risk and budget uncertainty dominate bond markets.
- ECB's Lane tempered hawkish expectations while Rehn defended past hikes; the deposit rate stands at 2.50% with Eurozone CPI at 3.8%.
Yesterday's Recap
Eurozone equities rallied on Tuesday, with the Euro Stoxx 50 up 0.48% to 6,272.23 and the DAX outperforming at +0.84% to 25,467.10, while the CAC 40 gained 0.40% to 7,865.07. The euro rebounded against the dollar, with EUR/USD rising 0.17% to 1.12, as French political risk eased following Le Pen's budget proposals. Bund yields firmed, with the German 2-year up 6 bp to 3.08% and the 10-year up 2 bp to 3.49%.
On the data front, German factory orders collapsed 10.6% m/m against a -1.0% consensus, a sharp reversal from the prior 3.2% gain. French industrial production fell 0.3% m/m, missing the +0.3% forecast and extending the prior month's -0.6% decline. Spanish services PMI beat at 58.3 versus 56.8 expected, while Italian services PMI disappointed at 51.7, down from 55.2.
Brent crude climbed 1.00% to $101.59, adding to the inflation backdrop.
The Day Ahead
Today's calendar centers on German industrial production, expected at +0.5% m/m after the prior -1.1% contraction, with the 02:00 ET release key for gauging manufacturing momentum. France posts its trade balance at 02:45 ET, with the deficit seen narrowing slightly to €6.5 billion from €6.7 billion. Tomorrow brings German trade balance and exports data, with the surplus forecast at €19.0 billion versus €21.3 billion previously.
Italy's industrial production on Friday is expected flat after a 0.7% gain. The data run will test whether Germany's order slump filters through to output, shaping ECB easing expectations.
Other Economic Notes
The France-Germany bond spread has widened to its widest since the euro crisis, with markets pricing elevated French political risk ahead of elections. Germany and France jointly called for tougher EU trade defences against China, signaling a more assertive commercial policy stance. French budget negotiations remain the focal point, with Le Pen's proposals providing temporary euro support.
The spread dynamics bear watching for implications peripheries-wide, as contagion risk from French fiscal slippage could complicate ECB policy calibration.