Eurozone Macro Daily(Beta Mode)
German IP Rebounds as France Bond Stress Builds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
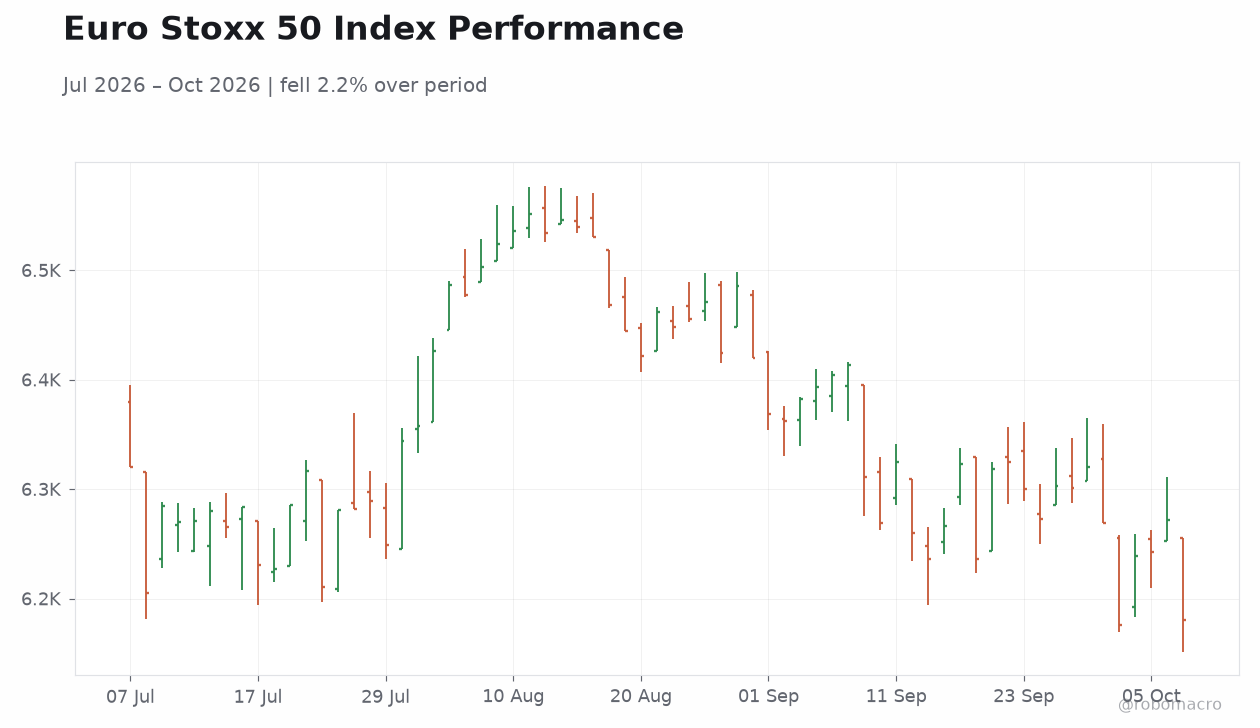
| Euro Stoxx 50 | 6,180.29 | -1.47% |
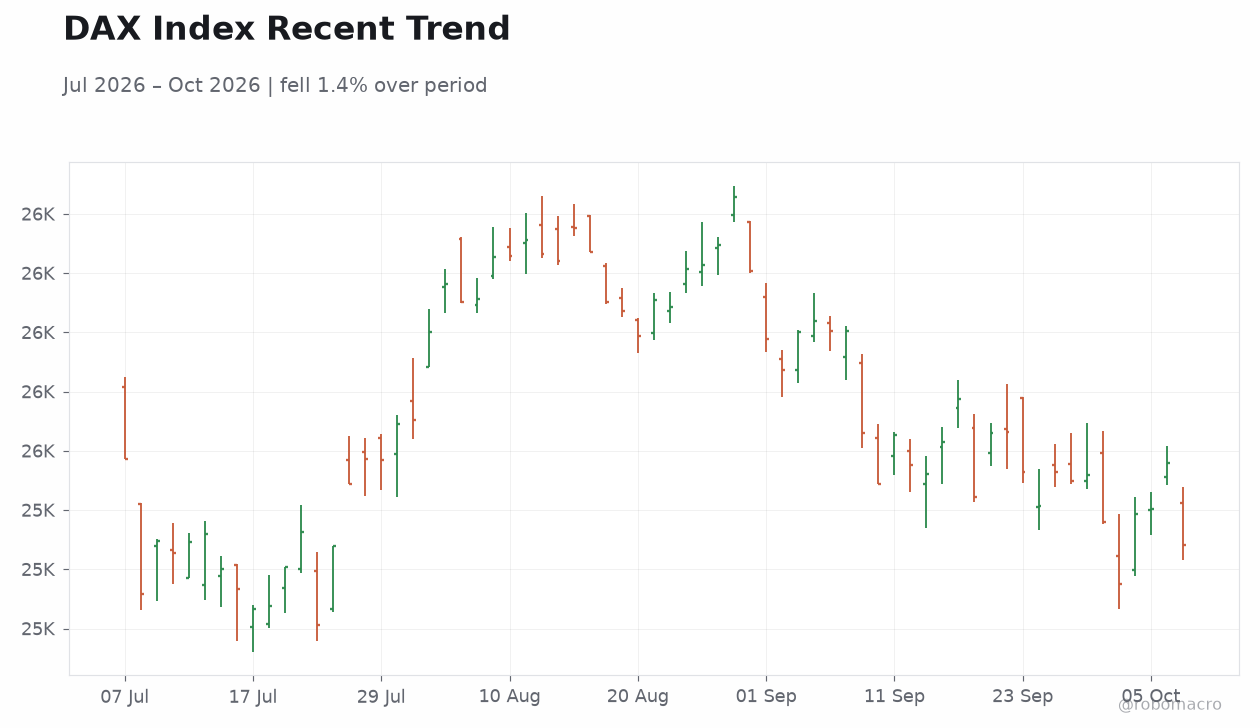
| DAX | 25,067.54 | -1.50% |
| CAC 40 | 7,769.21 | -1.22% |
| EUR/USD | 1.12 | -0.41% |
| EUR/GBP | 0.85 | +0.00% |
| EUR/JPY | 178.14 | +0.54% |
| Gold | 4,158.90 | +0.44% |
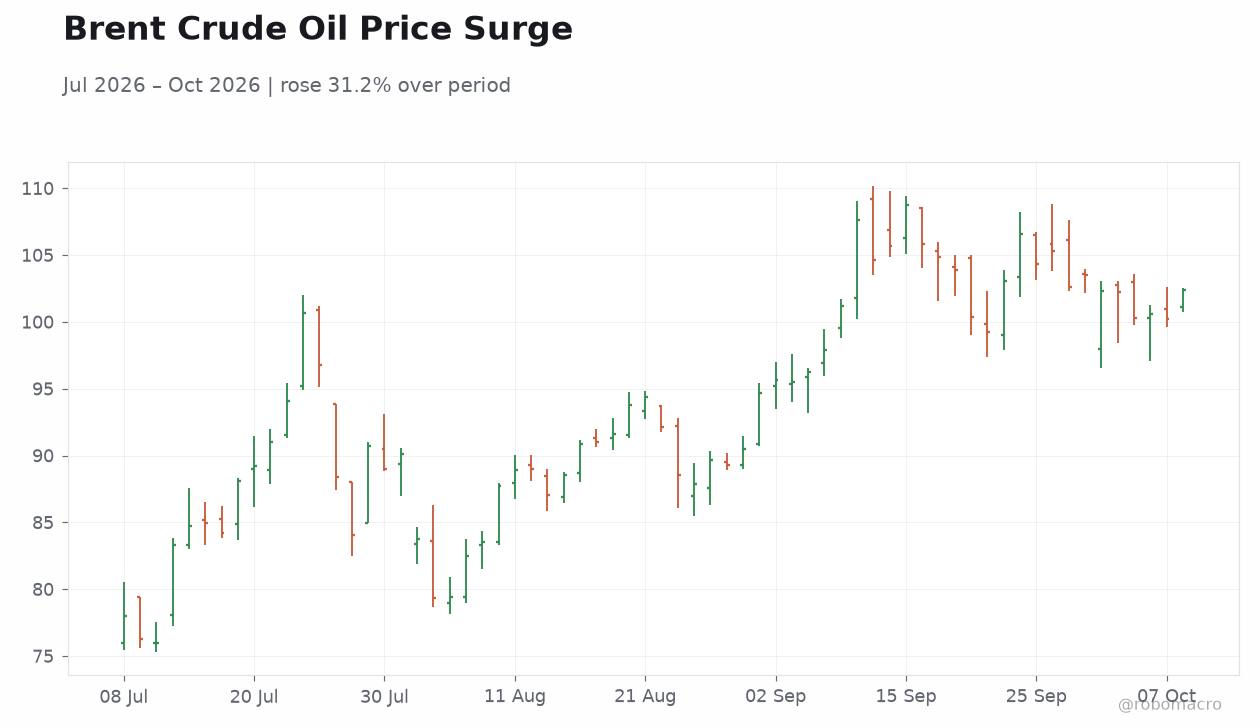
| Brent Crude | 102.33 | +2.13% |
| Bitcoin | 82,619.61 | -3.43% |
| German 2Y Bund | 3.06% | -2 bp |
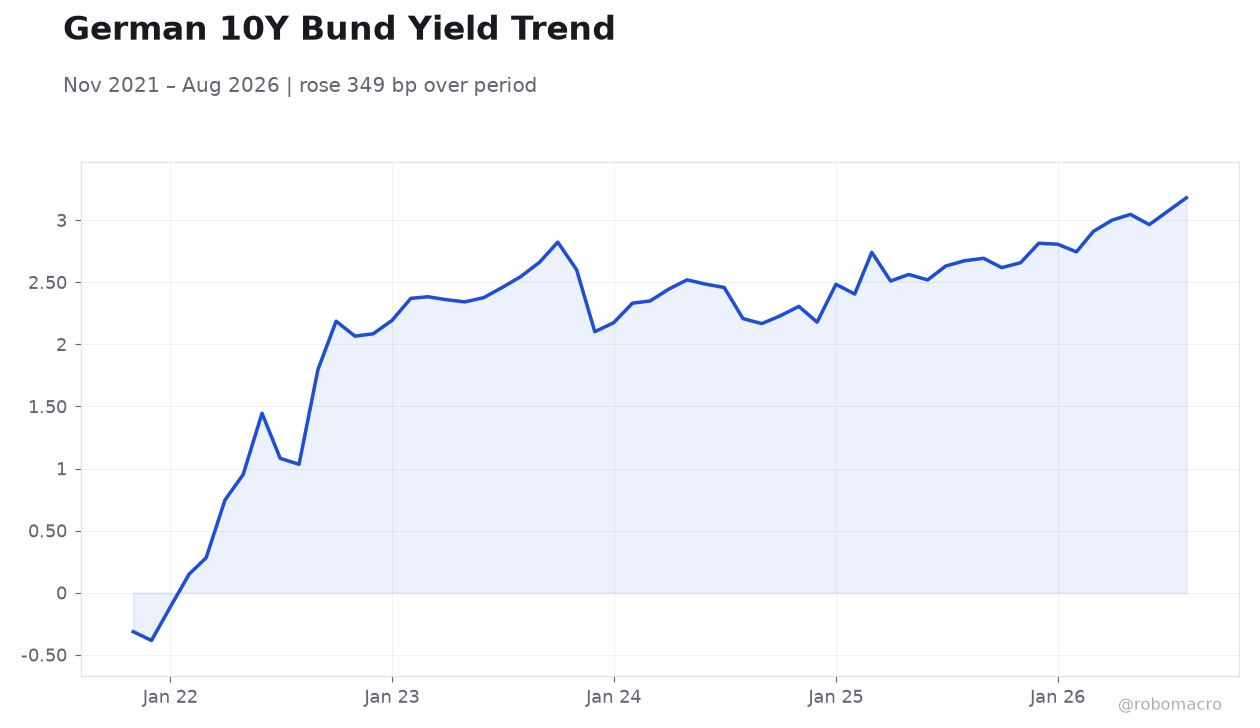
| German 10Y Bund | 3.52% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| S&P Global Services PMI | 57.80 | 56.80 | 58.30 |
| S&P Global Services PMI | 55.20 | - | 51.70 |
| Factory Orders Month-over-Month | 3.20 | -1 | -10.60 |
| Industrial Production Month-over-Month | -0.60 | 0.30 | -0.30 |
| Industrial Production Month-over-Month | -1.10 | 0.50 | 2 |
| Trade Balance | -6,600m | -6,500m | -6,100m |
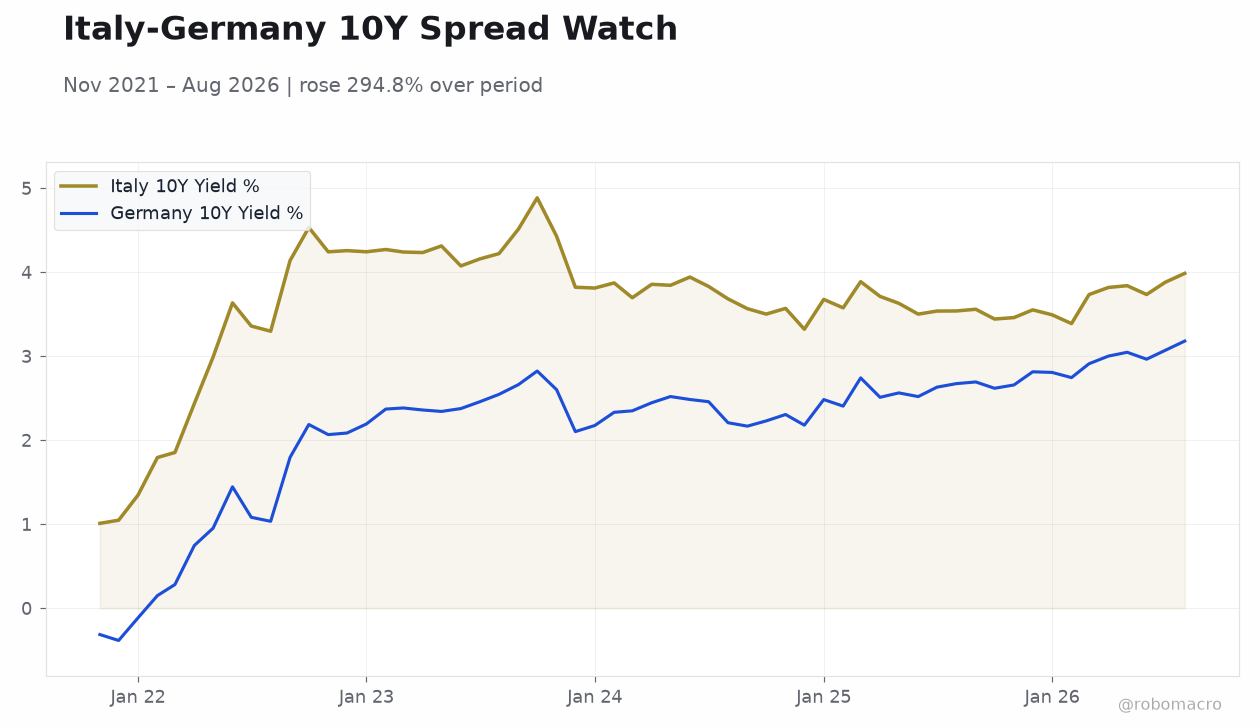 Italy-Germany 10Y Spread Watch | Type: macro_line | Italy 10Y Yield %: 3.986 (2026-08-01) | Range: 1.01–4.885 | Trend(6pt): 1.01,4.243,3.696,3.629,3.881,3.986 | Germany 10Y Yield %: 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | 21,300m | 19,000m | 02:00 |
| Exports Month-over-Month | -0.80 | - | 02:00 |
| Industrial Production Month-over-Month | 0.70 | 0 | 04:00 |
- German industrial production surged 2.0% m/m in September, far beating the 0.5% consensus, offsetting a steep -10.6% factory orders decline
- French bond spreads widen amid fiscal crisis; Banque de France chief says no ECB intervention needed
- Equities sold off sharply: DAX -1.50%, Euro Stoxx 50 -1.47%, while Brent jumped 2.13% to $102.33
Yesterday's Recap
European equities fell broadly on Wednesday, with the DAX down 1.50% to 25,067.54, the Euro Stoxx 50 off 1.47% at 6,180.29, and the CAC 40 lower by 1.22% at 7,769.21. The risk-off tone was partially cushioned by a strong German industrial production print of +2.0% m/m against a 0.5% consensus, a sharp rebound from the prior -1.1% contraction. German factory orders, released Tuesday, collapsed 10.6% m/m versus expectations of a modest -1.0% pullback from the prior +3.2% surge, underscoring the volatility in the country's manufacturing pipeline.
French industrial production slipped 0.3% m/m, missing the +0.3% consensus, while the French trade deficit narrowed to €6.1 billion from €6.6 billion, better than the €6.5 billion expected. In services, Spain's S&P Global PMI beat at 58.3 from 57.8, while Italy's printed 51.7, down sharply from 55.2. In rates, the German 10-year Bund yield rose 3 bp to 3.52% while the 2-year fell 2 bp to 3.06%, steepening the curve as the euro eased 0.41% to 1.12 against the dollar.
The Day Ahead
Today's calendar is headlined by German trade data at 08:00 CET, with the surplus expected to narrow to €19.0 billion from €21.3 billion. German monthly exports are also due, following a -0.8% contraction previously, and will be scrutinized for signs of external demand fragility after the factory orders slump. Tomorrow, Italian industrial production for August is forecast to show no growth at 0.0% m/m after July's +0.7% gain.
With no ECB speakers or Governing Council meetings scheduled, attention will center on how French bond dynamics evolve and whether the equity risk-off extends into a second session. Traders will also watch Brent crude, which jumped 2.13% to $102.33, for inflation implications.
Other Economic Notes
France's fiscal deterioration has become the euro area's dominant credit story, with headlines describing the country as Europe's most vulnerable economy and spreads surging on domestic unrest. Banque de France Governor François Villeroy de Galhau moved to calm markets, insisting France does not need ECB help at present, though the tone suggests Paris is sensitive to comparisons with the sovereign debt era. Encouragingly, the FT reports large asset managers are 'bottom fishing' in euro area bonds, judging fears of a debt-crisis-style blowup to be overdone.
↓ p.2