Eurozone Macro Daily(Beta Mode)
Bunds Rally, Equities Gain; France in Focus
Market Snapshot
| Asset | Level | Change |
|---|---|---|
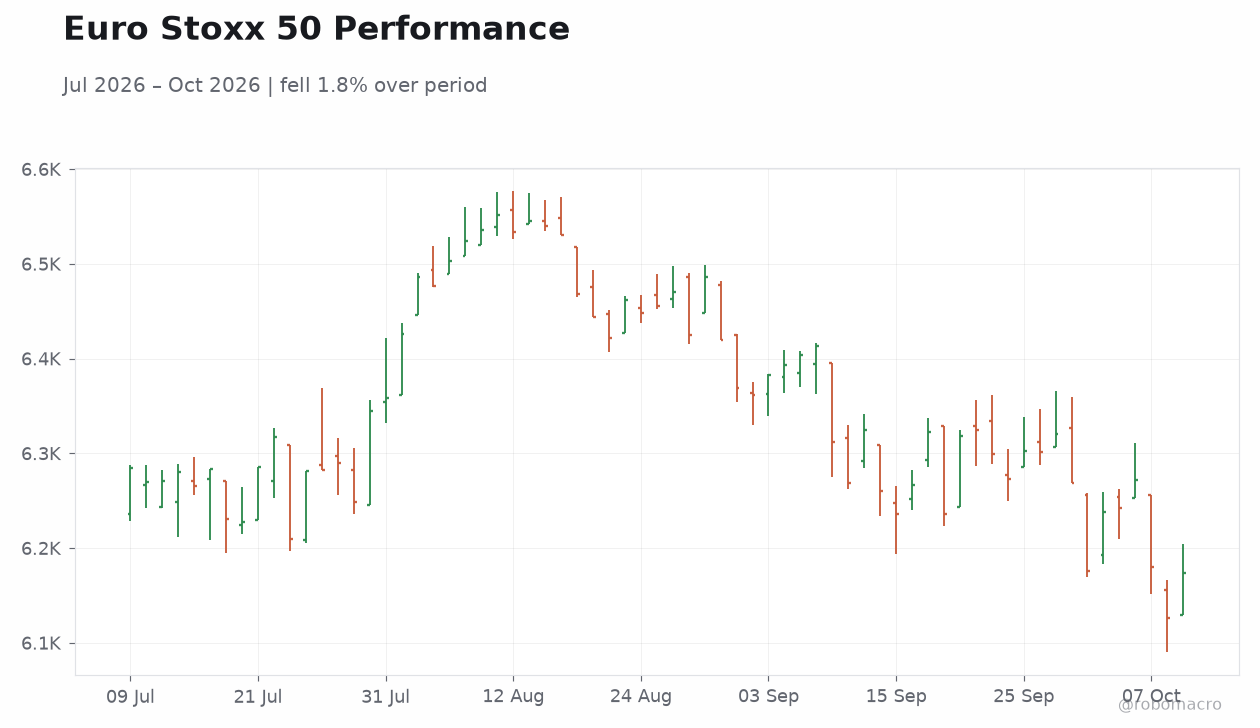
| Euro Stoxx 50 | 6,173.37 | +0.76% |
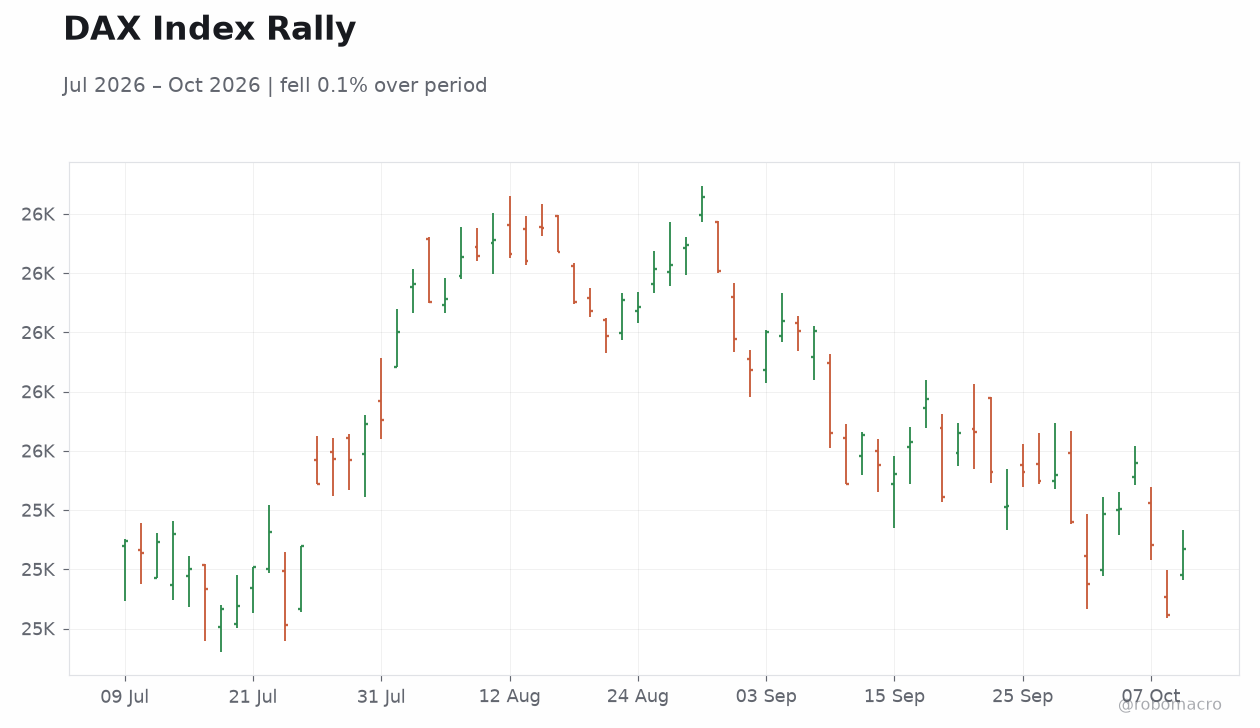
| DAX | 25,087.27 | +1.13% |
| CAC 40 | 7,803.33 | +0.95% |
| EUR/USD | 1.12 | -0.02% |
| EUR/GBP | 0.85 | -0.15% |
| EUR/JPY | 177.45 | +0.12% |
| Gold | 4,220.50 | +0.10% |
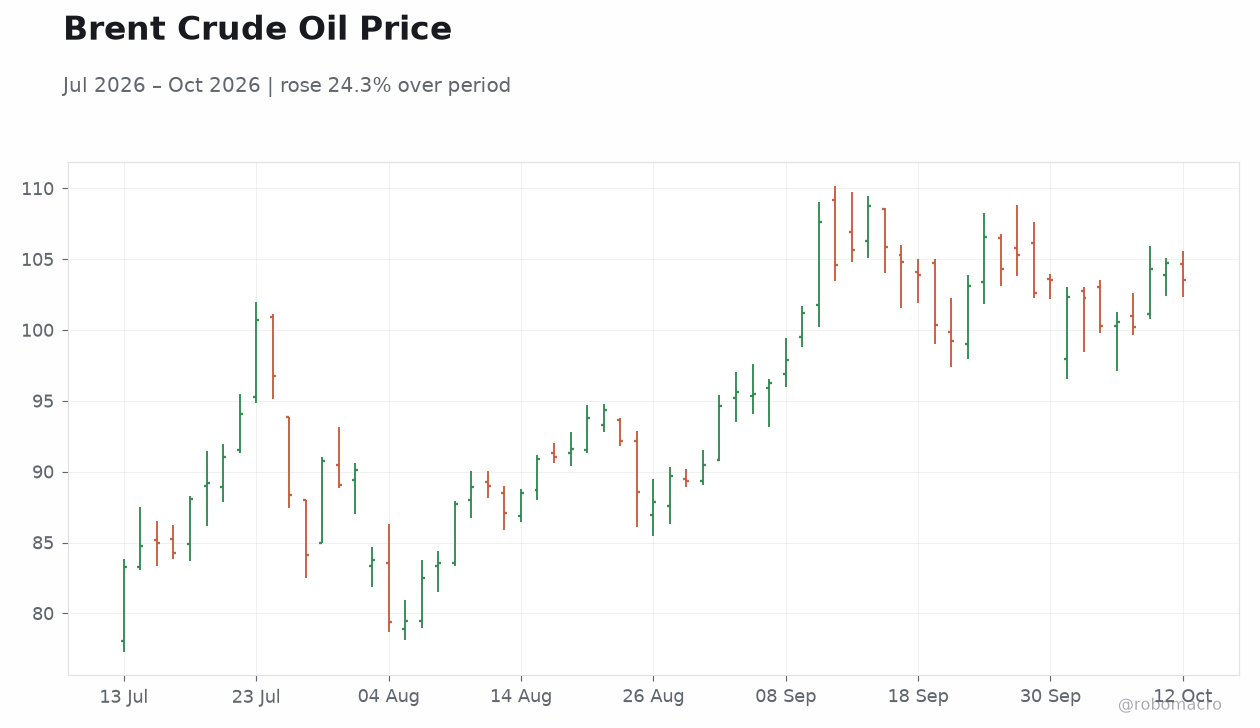
| Brent Crude | 103.39 | -1.27% |
| Bitcoin | 84,030.27 | +1.35% |
| German 2Y Bund | 3.08% | 0 bp |
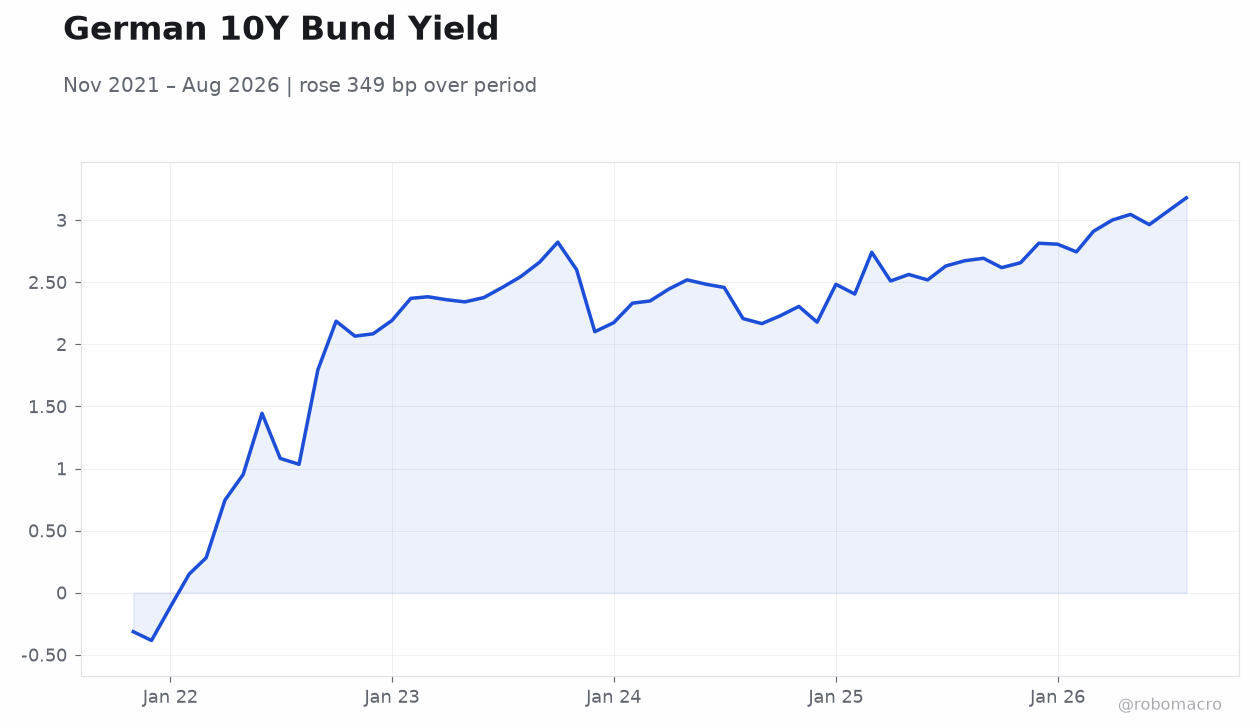
| German 10Y Bund | 3.53% | -4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
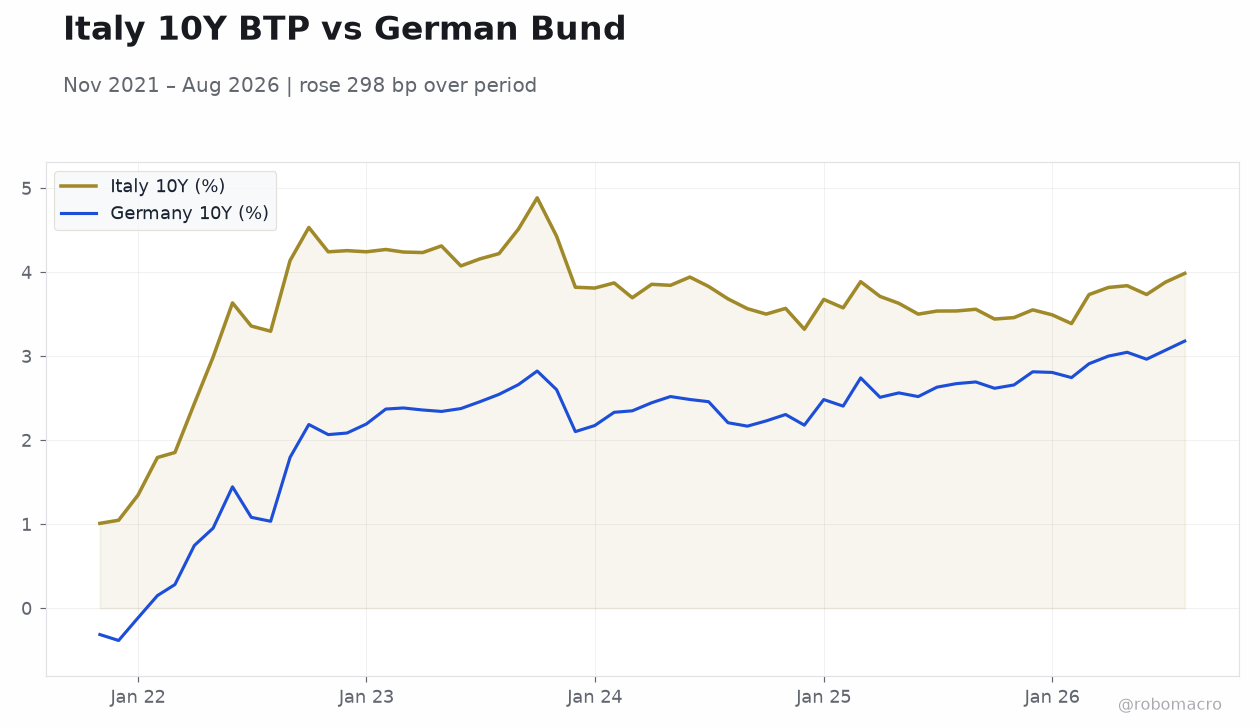 Italy 10Y BTP vs German Bund | Type: macro_line | Italy 10Y (%): 3.986 (2026-08-01) | Range: 1.01–4.885 | Trend(6pt): 1.01,4.243,3.696,3.629,3.881,3.986 | Germany 10Y (%): 3.18 (2026-08-01) | Range: -0.3843–3.18 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.18
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wholesale Prices Month-over-Month | 0.90 | 0.70 | 02:00 |
| Wholesale Prices Year-over-Year | 6.80 | - | 02:00 |
| Headline Unemployment Rate | 4 | - | 00:30 |
| Trade Balance | 8,240m | 7,500m | 06:00 |
- German 10-year Bund yield eased 4 bp to 3.53% as equities rallied, with the DAX up 1.13% and Euro Stoxx 50 gaining 0.76%.
- France's bond-market turmoil dominates the narrative, with the ECB seen sitting on the sidelines as fiscal concerns mount.
- German wholesale prices and Dutch unemployment headline a light data week; attention shifts to ECB commentary and France's fiscal trajectory.
Yesterday's Recap
Friday's session closed with a broad risk-on tone across European equities. The DAX led the charge, rising 1.13% to 25,087.27, while the CAC 40 added 0.95% to 7,803.33 and the Euro Stoxx 50 advanced 0.76% to 6,173.37. Fixed income told a more nuanced story: the German 10-year Bund yield fell 4 bp to 3.53%, signalling a flight to quality even as equities rallied, while the 2-year yield held steady at 3.08%.
In currency markets, EUR/USD slipped 0.02% to 1.12, and EUR/GBP lost 0.15% to 0.85, though EUR/JPY managed a 0.12% gain to 177.45. Brent crude declined 1.27% to $103.39, offering a modest tailwind for energy-importing eurozone economies. Gold edged up 0.10% to $4,220.50, and Bitcoin jumped 1.35% to $84,030, reflecting continued appetite for risk assets.
The contrast between rallying equities and easing core yields suggests markets are pricing slower growth alongside resilient corporate earnings.
The Day Ahead
The calendar is thin at the start of the week. German wholesale price data arrives Wednesday at 02:00 ET, with month-over-month consensus at 0.7% versus the prior 0.9% print; the year-over-year figure, previously 6.8%, will be scrutinised for pipeline inflation pressure. Thursday brings the Dutch headline unemployment rate at 00:30 ET, with the prior reading at 4.0% — a key gauge of labour-market tightness in the eurozone's northern core.
Italy's trade balance follows at 06:00 ET Friday, where the consensus of €7.5 billion compares against the prior €8.24 billion surplus. With no eurozone aggregate releases scheduled, peripheral bond spreads and ECB speaker commentary will likely drive intraday price action.
Other Economic Notes
France's fiscal predicament remains the eurozone's central tension. Protesters are demanding increased spending precisely as markets require consolidation, trapping the government between social pressure and bond-market discipline. French sovereign risk now exceeds Italy's in certain tenors — a remarkable reversal given Italy's historically precarious debt position.
↓ p.2