Eurozone Macro Daily(Beta Mode)
Bunds Bid as France Frays, Merz Woos Capital
Market Snapshot
| Asset | Level | Change |
|---|---|---|
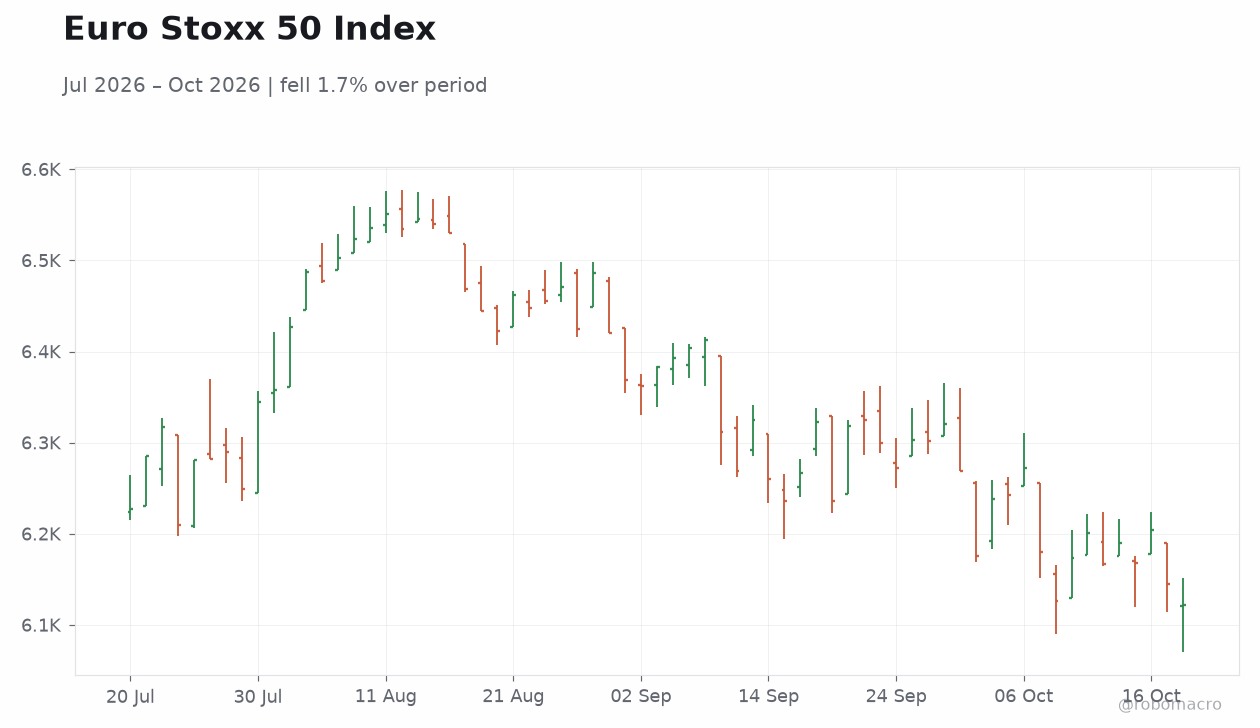
| Euro Stoxx 50 | 6,121.66 | -0.38% |
| DAX | 25,304.42 | -0.06% |
| CAC 40 | 7,838.49 | -0.38% |
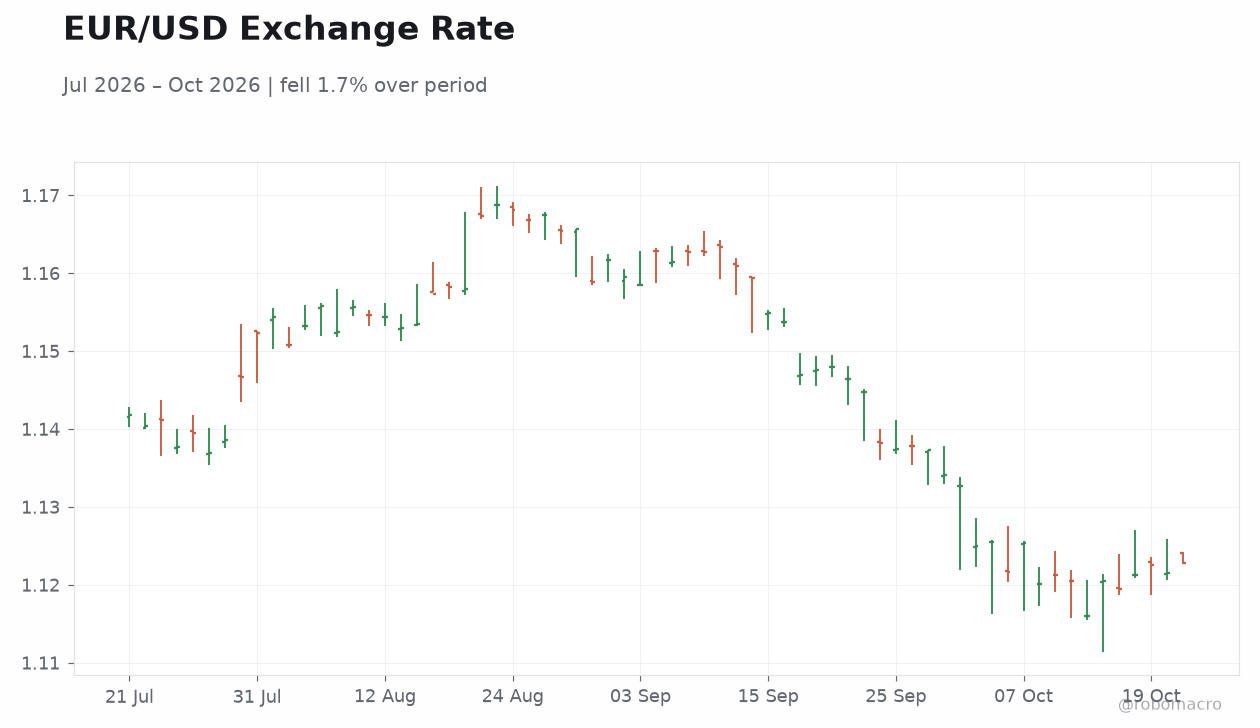
| EUR/USD | 1.12 | +0.11% |
| EUR/GBP | 0.84 | -0.38% |
| EUR/JPY | 177.44 | -0.18% |
| Gold | 4,132.70 | -0.24% |
| Brent Crude | 110.26 | +1.35% |
| Bitcoin | 82,743.17 | +1.09% |
| German 2Y Bund | 3.08% | -2 bp |
| German 10Y Bund | 3.48% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
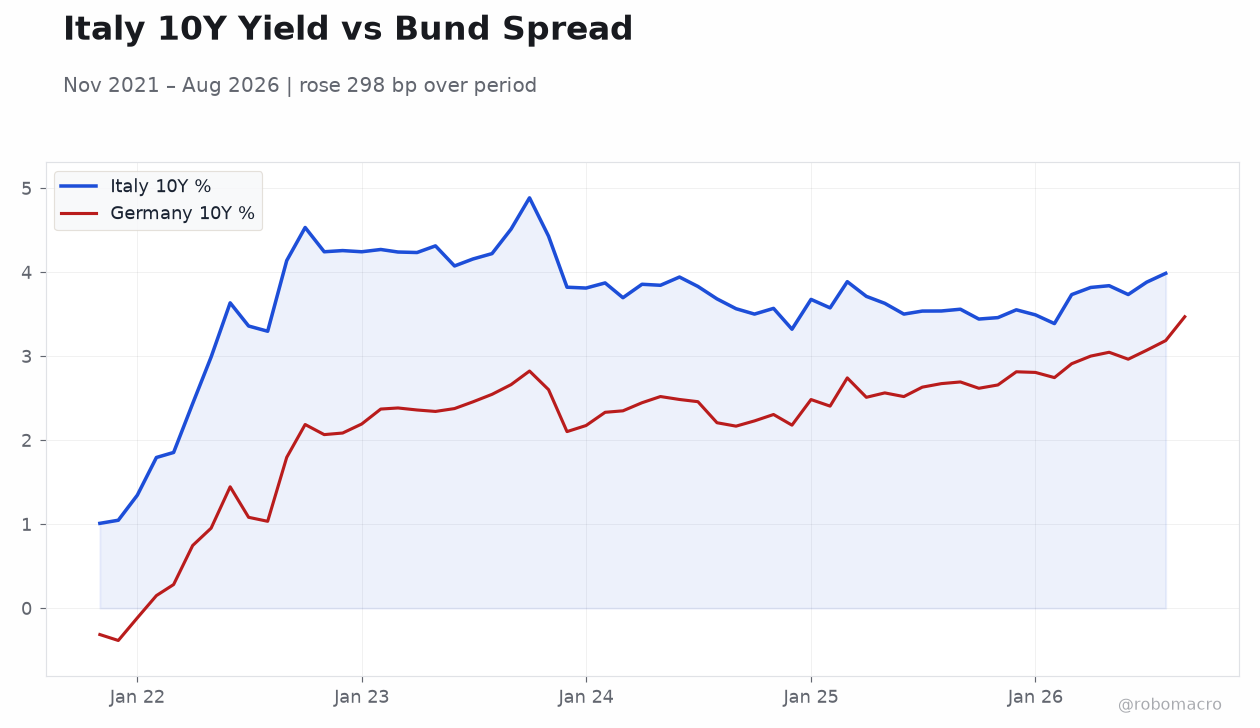
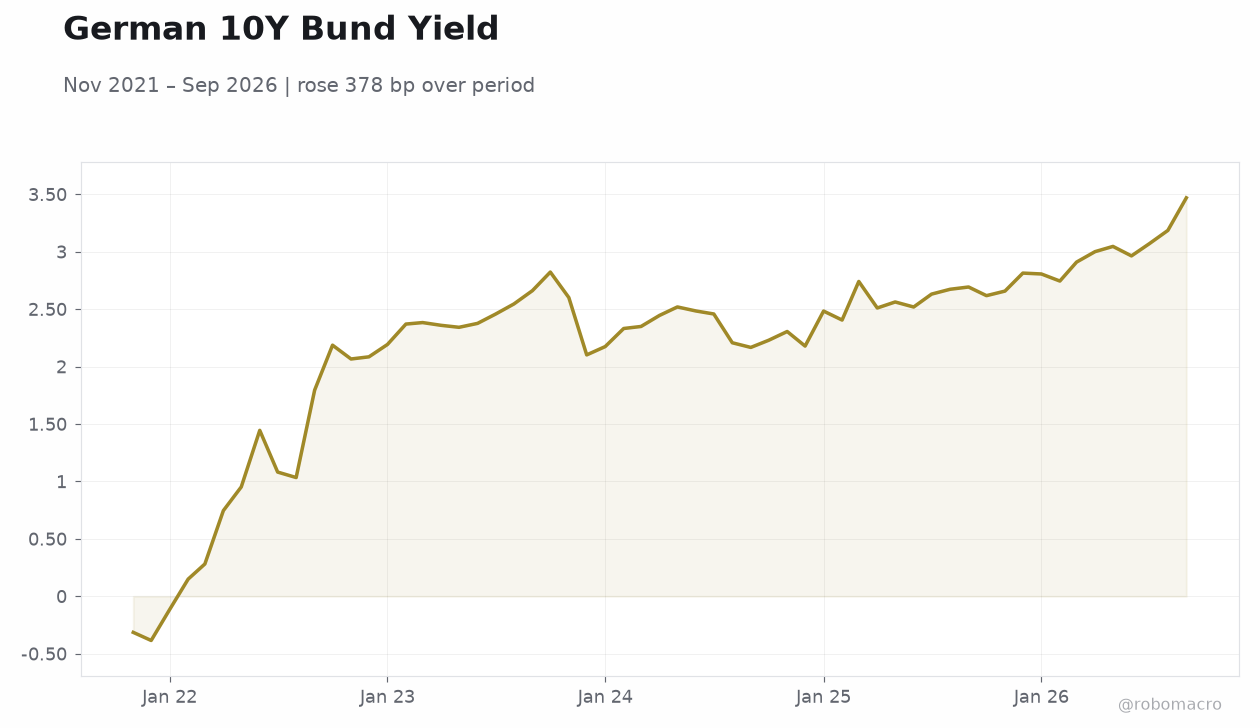 German 10Y Bund Yield | Type: macro_line | 10Y Bund %: 3.47 (2026-09-01) | Range: -0.3843–3.47 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.47
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- German 2Y and 10Y Bund yields eased 2 bp and 1 bp respectively, steepening the curve modestly as investors sought core duration amid French political risk.
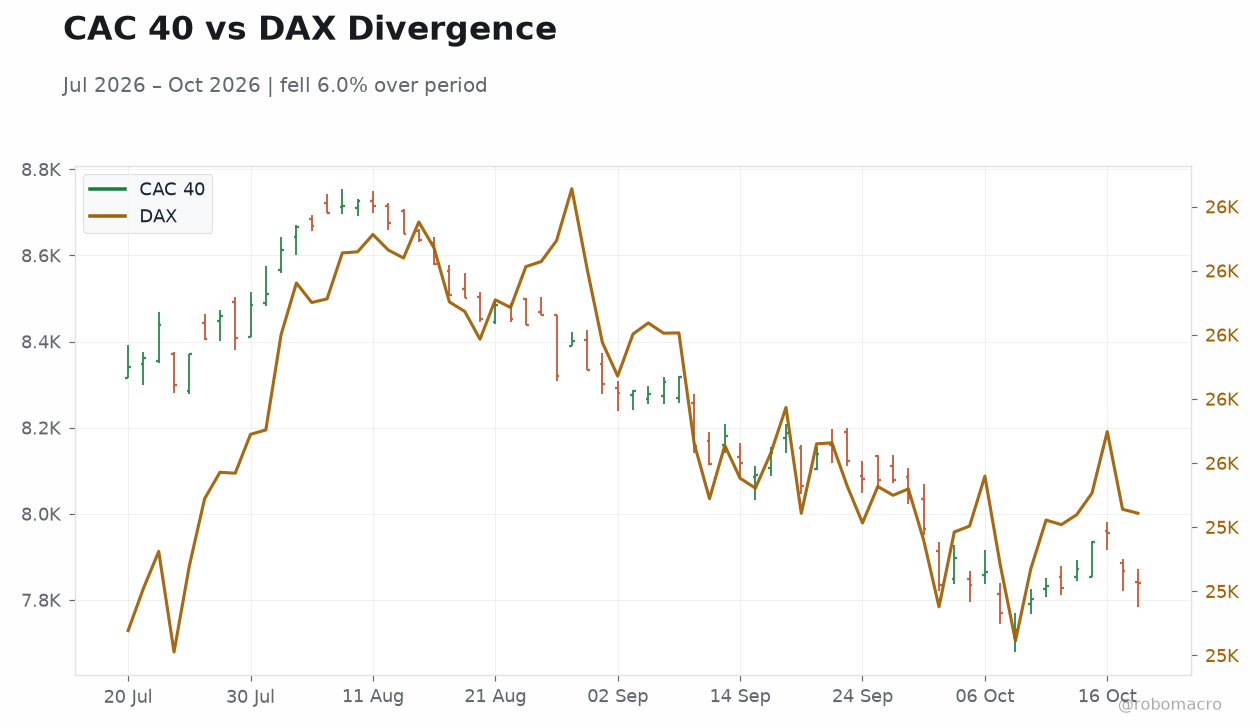
- Euro Stoxx 50 fell 0.38% and CAC 40 dropped 0.38%, while the DAX was nearly flat at -0.06%, reflecting France-specific stress rather than broad Eurozone weakness.
- Berlin's "Invest in Germany" summit secured €230bn in investment pledges, a record comparable to France's Choose France framework, supporting the medium-term German growth narrative.
Yesterday's Recap
Eurozone markets on October 20 were defined by divergence between core and periphery sentiment rather than fresh macro prints, with no scheduled data releases on the calendar. German 2Y Bund yields eased 2 bp to 3.08% and 10Y Bunds fell 1 bp to 3.48%, a modest core-duration bid consistent with hedging demand. Equities told a France-specific story: the CAC 40 dropped 0.38% while the DAX was essentially unchanged at -0.06%, and the Euro Stoxx 50 lost 0.38%.
EUR/USD firmed 0.11% to 1.12 despite French fiscal noise, while EUR/GBP slipped 0.38% to 0.84 as strong UK labour data lifted sterling. Brent crude jumped 1.35% to $110.26, a reminder that energy remains an upside inflation risk for the Eurozone. Gold eased 0.24% to $4,132.70, and Bitcoin gained 1.09%.
The Day Ahead
The October 21 calendar is empty for the Eurozone, leaving markets to trade off positioning, French political headlines and the residual effects of the German investment summit. With no tier-one prints, Bund direction will likely be driven by French budget risk and any ECB commentary on the sidelines. Equity investors will watch whether the CAC underperformance extends or stabilises after the recent unrest and curfew announcements.
EUR crosses remain sensitive to French fiscal credibility and to relative UK and US rate expectations. Absent data, liquidity may thin and amplify moves around headline risk.
Other Economic Notes
The €230bn in investment pledges unveiled at Berlin's "Invest in Germany" summit is a meaningful signal for German capex and medium-term growth, though pledges require conversion into actual spending. France remains the Eurozone's key fault line: curfews imposed after weekend unrest, elevated political risk and a budget trajectory under scrutiny have made French equities a favoured short for some investors. Scope Ratings frames France as a decisive test for eurozone cohesion and credit risk, a view echoed by AllianceBernstein's argument that French fiscal stress is not Europe's next debt crisis.
Energy prices near $110 Brent complicate the inflation outlook, keeping the ECB's easing path narrow.