Eurozone Macro Daily(Beta Mode)
French Debt Woes Pressure Eurozone
Market Snapshot
| Asset | Level | Change |
|---|---|---|
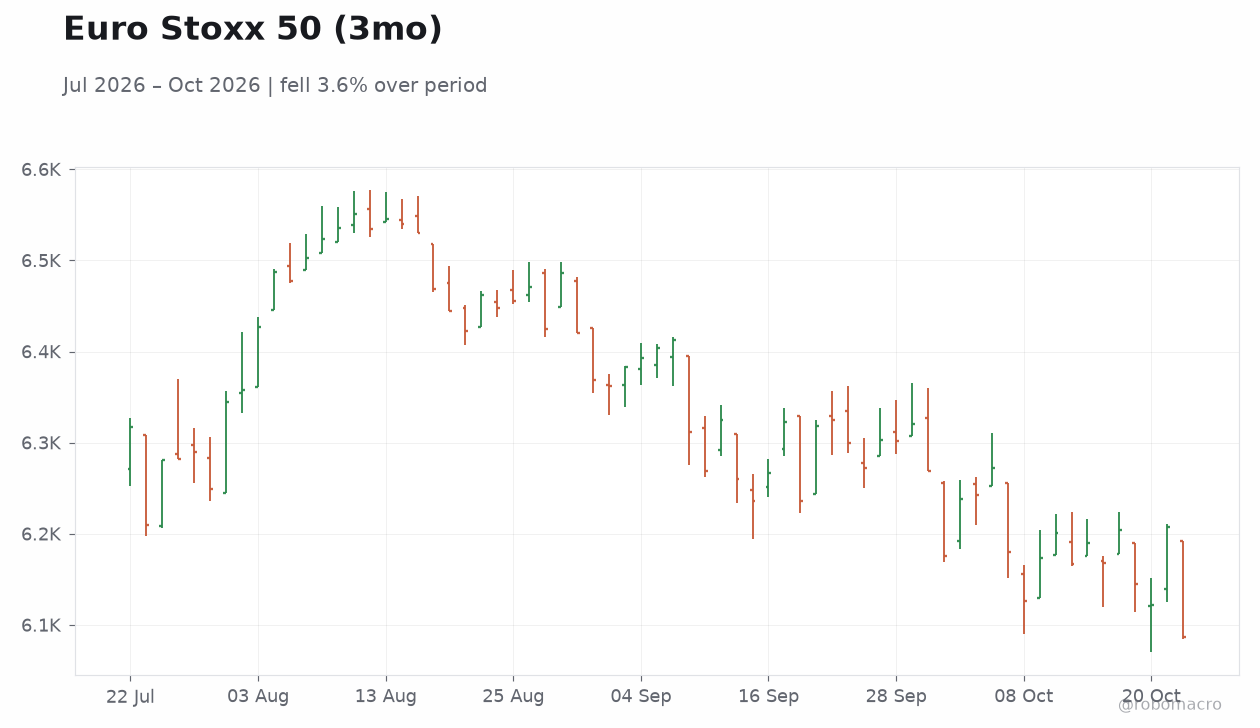
| Euro Stoxx 50 | 6,087.01 | -1.94% |
| DAX | 25,371.75 | -1.07% |
| CAC 40 | 7,811.26 | -1.39% |
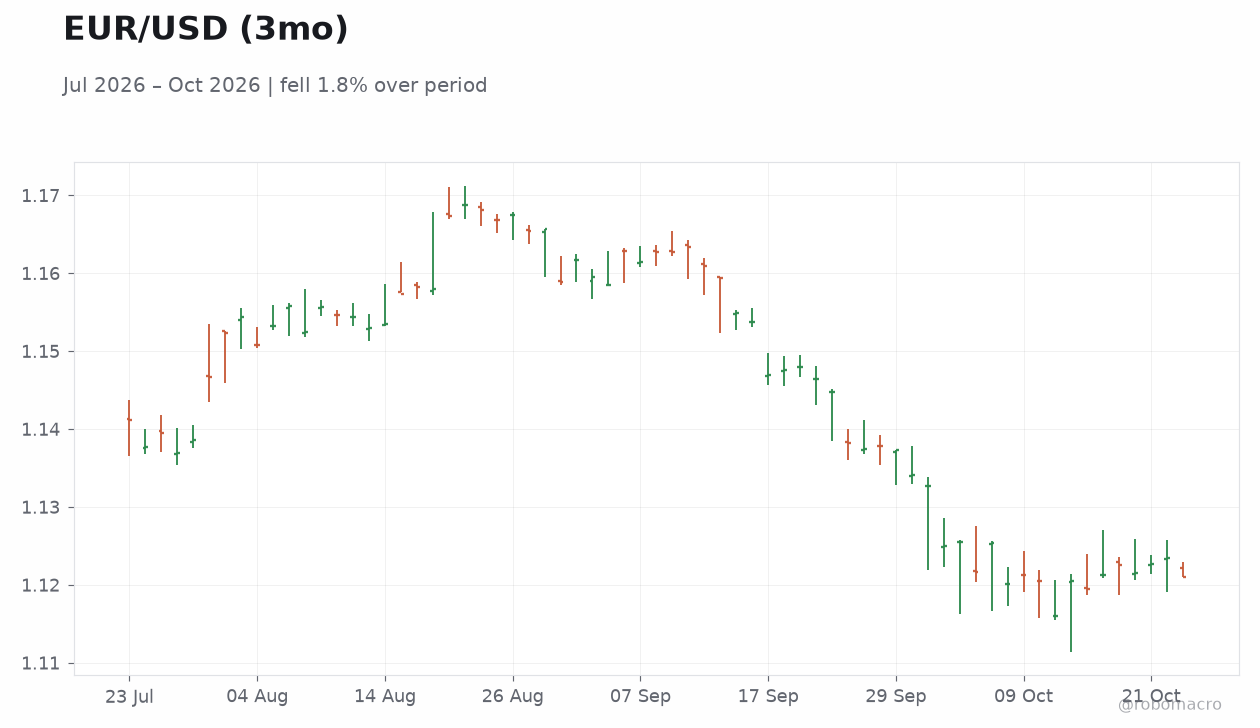
| EUR/USD | 1.12 | -0.20% |
| EUR/GBP | 0.84 | -0.17% |
| EUR/JPY | 176.00 | -0.93% |
| Gold | 4,017.90 | -1.05% |
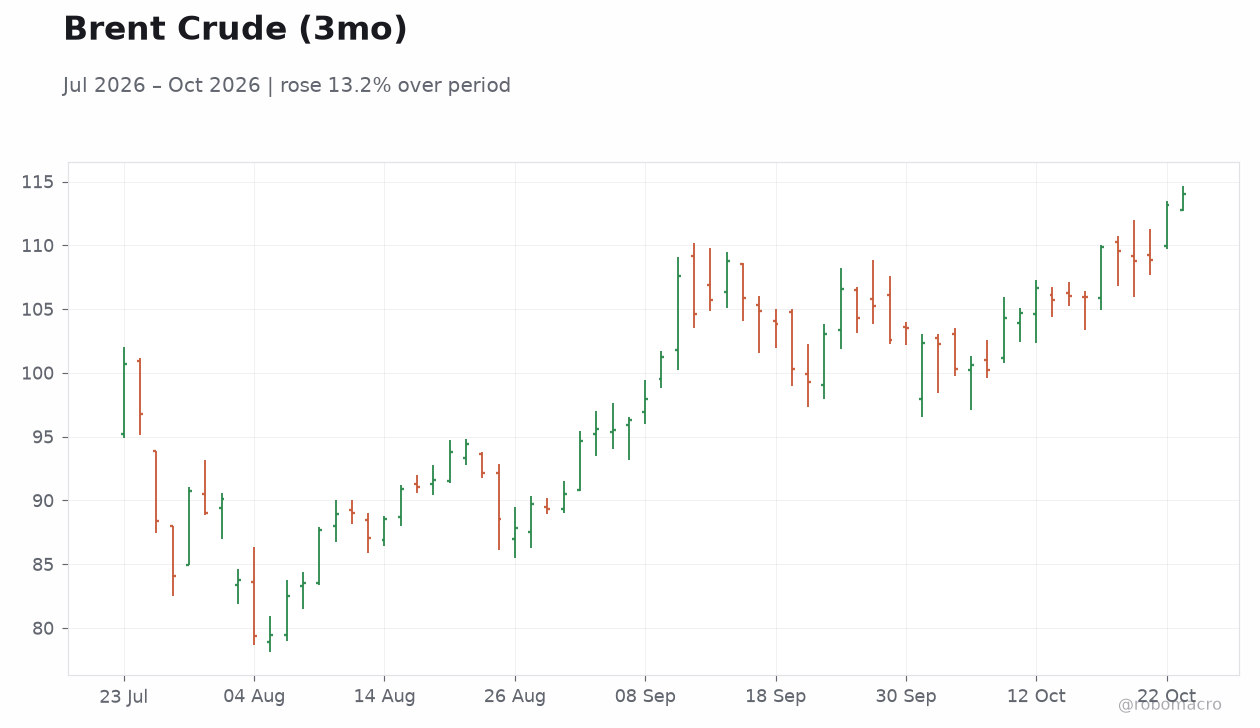
| Brent Crude | 114.05 | +0.78% |
| Bitcoin | 81,529.25 | -2.96% |
| German 2Y Bund | 3.11% | +4 bp |
| German 10Y Bund | 3.42% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
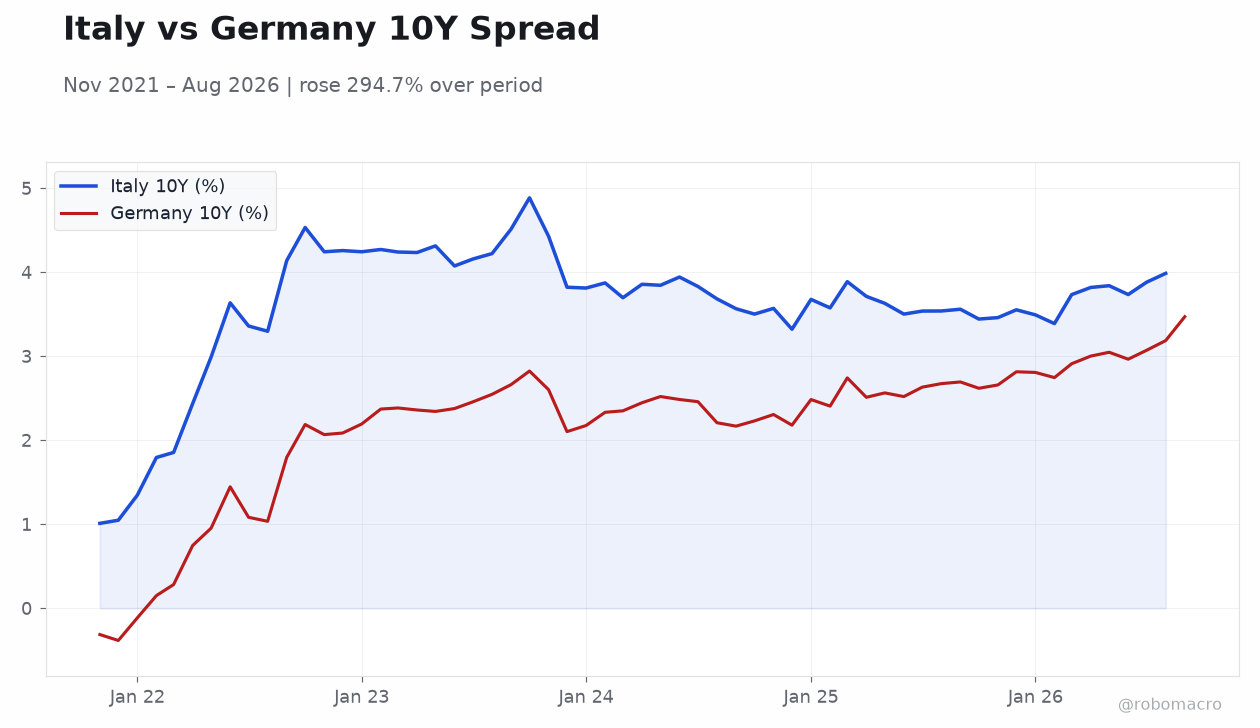
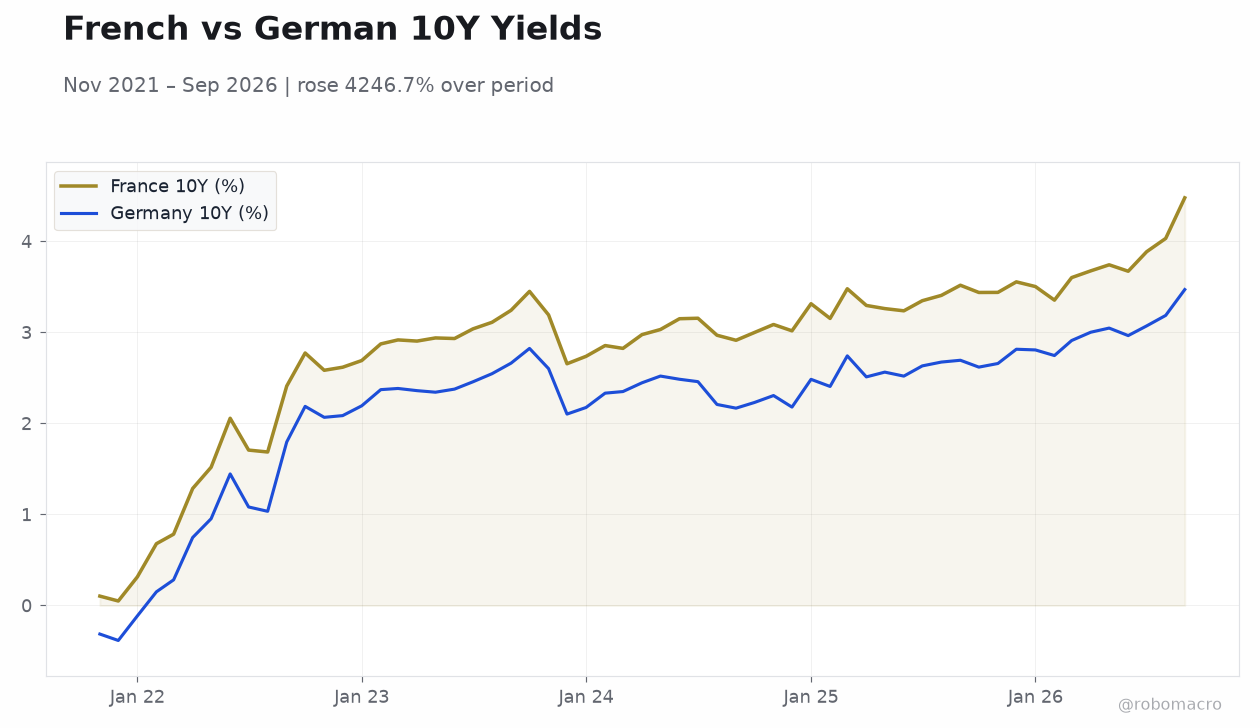 French vs German 10Y Yields | Type: macro_line | France 10Y (%): 4.477 (2026-09-01) | Range: 0.0493–4.477 | Trend(6pt): 0.103,2.69,2.824,3.261,3.885,4.477 | Germany 10Y (%): 3.47 (2026-09-01) | Range: -0.3843–3.47 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.47
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- French sovereign risk premium hits eurozone crisis highs, driving CAC 40 down 1.39% and widening spreads versus German Bunds.
- German 2-year yield rises 4 bp to 3.11% while 10-year eases 2 bp to 3.42%, reflecting mixed fiscal and growth signals.
- Euro Stoxx 50 falls 1.94% as EUR/USD slips 0.20% to 1.12 amid broader risk aversion and French unrest.
Yesterday's Recap
Equity markets across the eurozone declined sharply on 22 October, with the Euro Stoxx 50 dropping 1.94%, the DAX falling 1.07% and the CAC 40 sliding 1.39%. German 2-year Bund yields climbed 4 bp to 3.11% while the 10-year yield eased 2 bp to 3.42%, as investors digested French fiscal concerns. French debt risk premiums reached levels last seen during the eurozone sovereign crisis, prompting foreign investors to reduce exposure according to multiple reports.
German gas consumption hit a nine-month high amid colder weather and weaker wind output, lifting power-sector demand. The euro weakened modestly, with EUR/USD down 0.20% to 1.12, EUR/GBP off 0.17% to 0.84 and EUR/JPY declining 0.93% to 176.00. ECB Governing Council member Fabio Panetta noted that rising bond yields would restrain eurozone economic activity without posing an immediate threat.
Broader market moves reflected caution ahead of any potential fiscal slippage in France and Italy.
The Day Ahead
Attention turns to scheduled speeches by ECB officials and national finance ministers that could clarify fiscal-monetary coordination. Market participants will monitor any updates on French budget negotiations and their potential impact on sovereign spreads. German tax-revenue projections through 2030 are expected to remain in focus following the Finance Ministry’s assessment of limited fiscal space.
Investors also await any fresh commentary on PEPP reinvestments and TPI activation criteria amid ongoing French debt-market volatility. Cross-asset flows into German Bunds may continue if French political uncertainty persists into the weekend.
Other Economic Notes
France’s public-debt trajectory, now projected above €3.8 trillion by 2027, continues to dominate eurozone fiscal discussions and is pressuring local-government finances in major cities. Germany’s more resilient tax base offers limited room for additional stimulus, constraining any coordinated eurozone response. Rising sovereign spreads risk transmitting stress to Italian and Spanish funding costs if investor differentiation weakens.
Persistent core inflation at 3.80% and unemployment at 6.40% leave the ECB with little margin to ease policy even as growth faces headwinds from higher yields.