Eurozone Macro Daily(Beta Mode)
Bund Yields Ease as French Debt Worries Mount
Market Snapshot
| Asset | Level | Change |
|---|---|---|
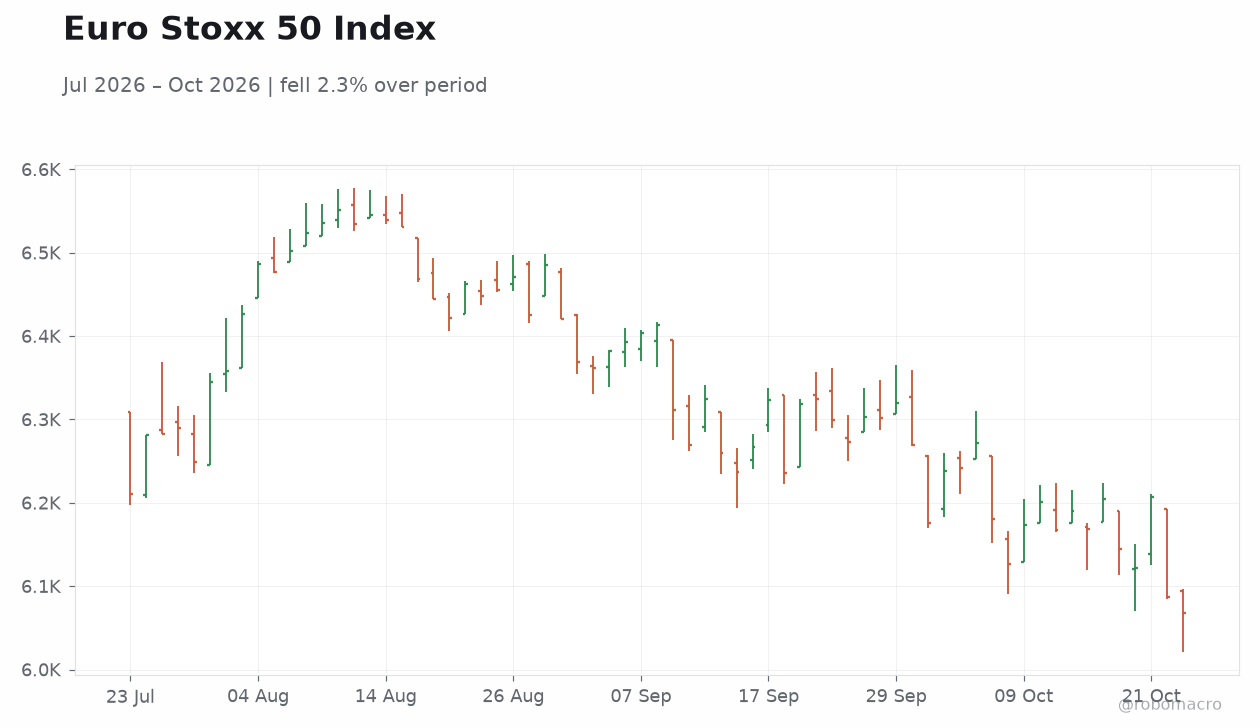
| Euro Stoxx 50 | 6,068.22 | -0.31% |
| DAX | 25,181.65 | -0.75% |
| CAC 40 | 7,782.82 | -0.36% |
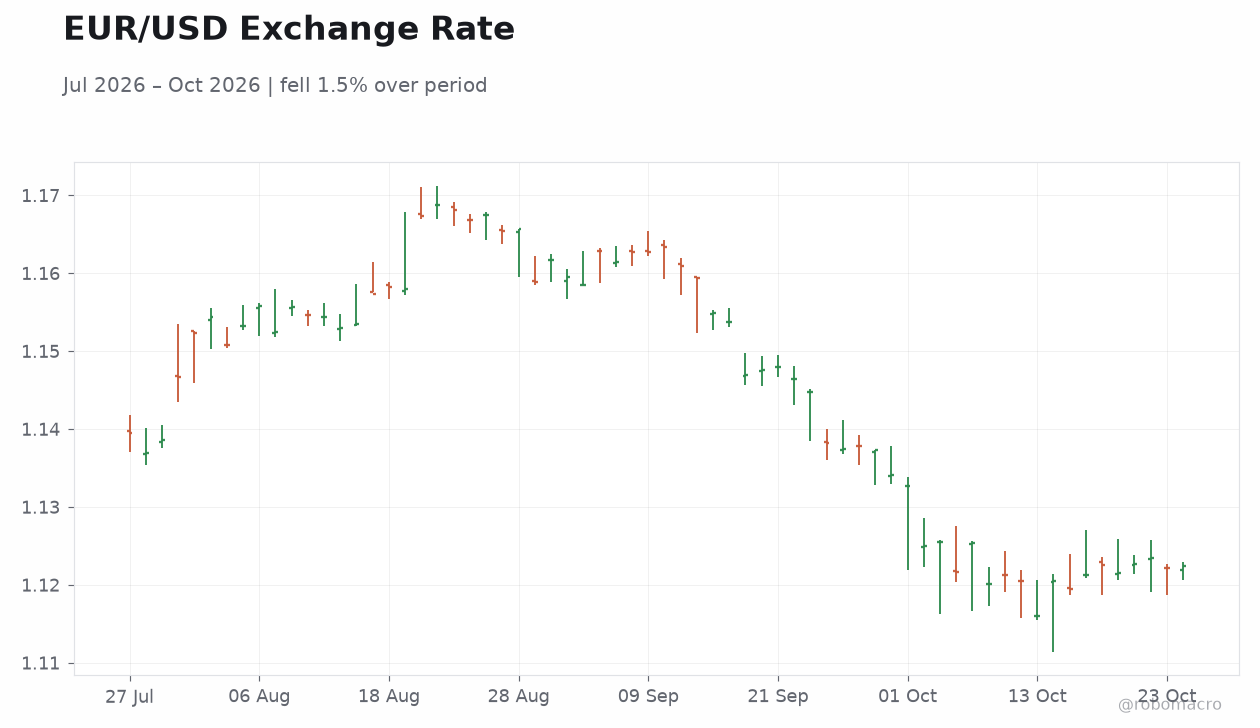
| EUR/USD | 1.12 | +0.02% |
| EUR/GBP | 0.84 | +0.18% |
| EUR/JPY | 176.09 | +0.28% |
| Gold | 4,027.00 | +0.48% |
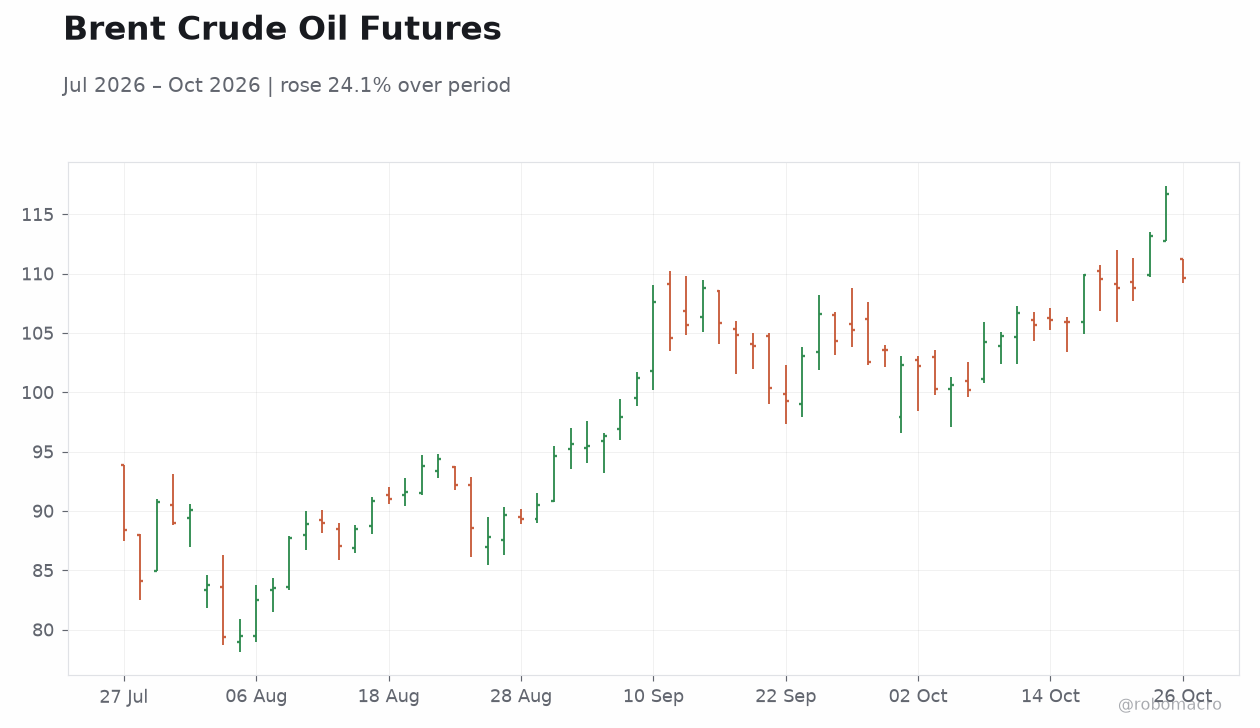
| Brent Crude | 109.62 | -6.08% |
| Bitcoin | 79,999.69 | -0.98% |
| German 2Y Bund | 3.02% | -9 bp |
| German 10Y Bund | 3.39% | -5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
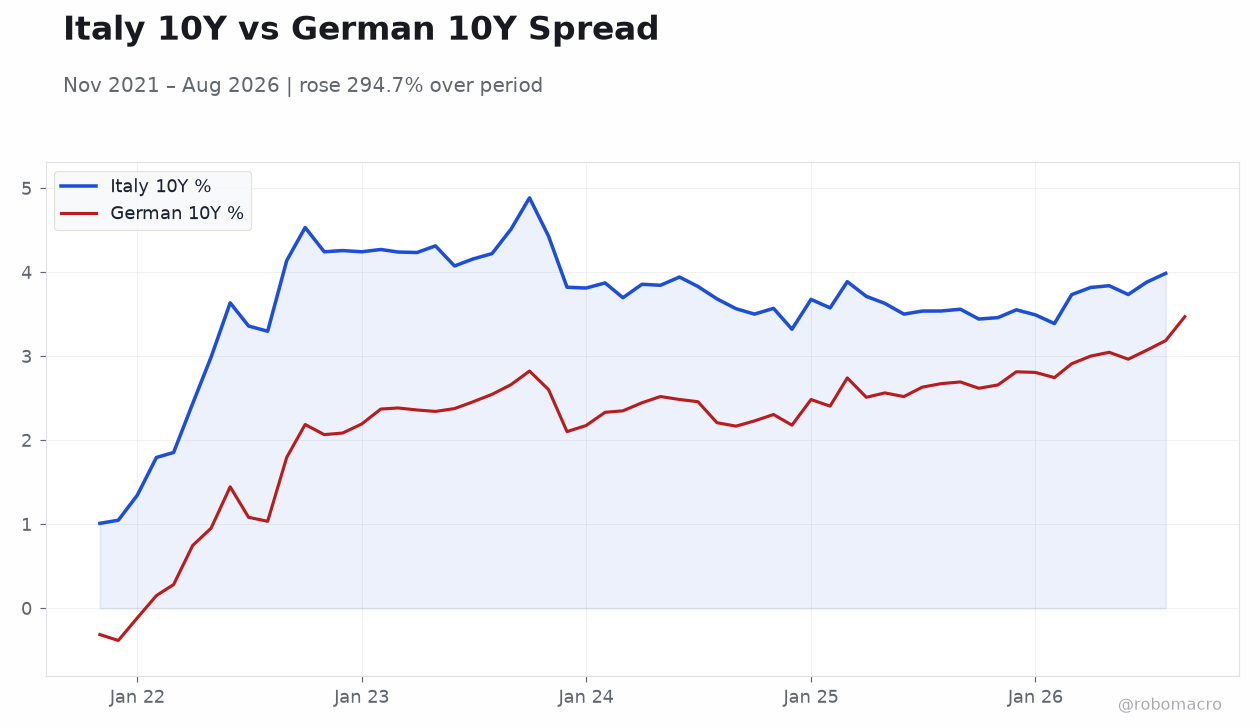
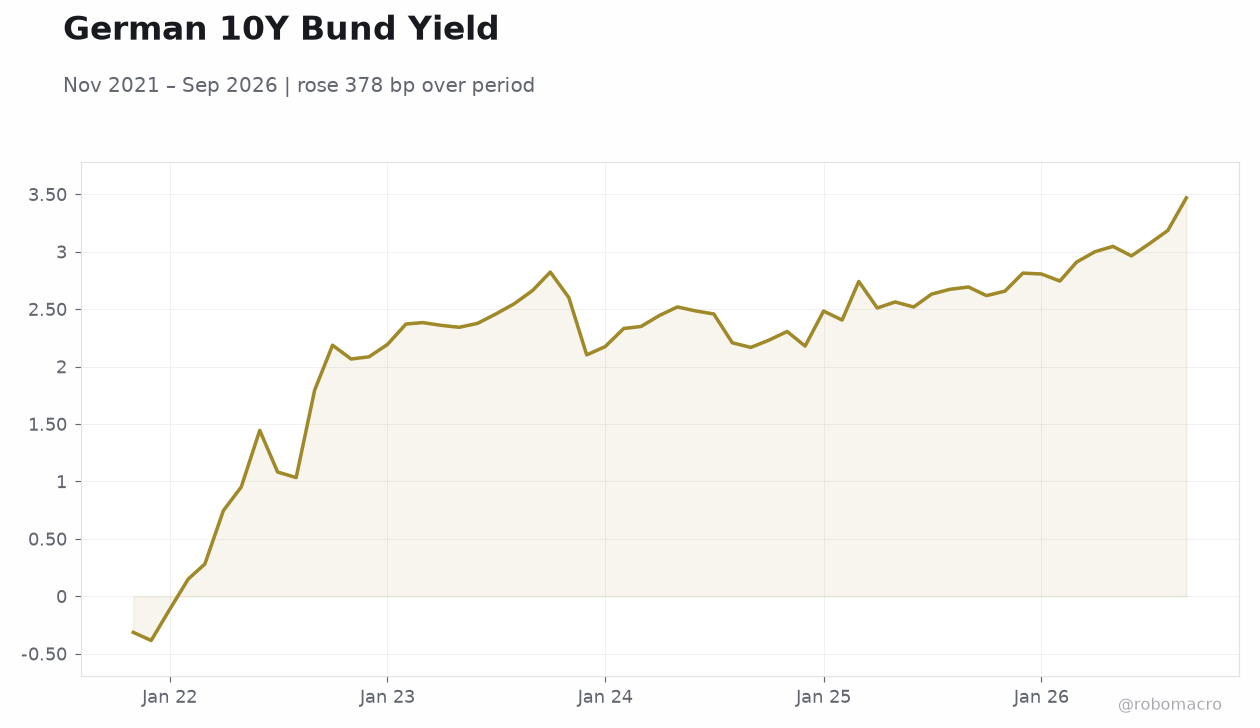 German 10Y Bund Yield | Type: macro_line | Yield %: 3.47 (2026-09-01) | Range: -0.3843–3.47 | Trend(6pt): -0.3136,2.193,2.349,2.563,3.07,3.47
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Ifo Business Climate | 89.90 | 89.80 | 05:00 |
| Consumer Confidence Index | 86 | - | 03:45 |
| Headline Unemployment Rate | 9.87 | - | 04:00 |
| GFK Consumer Confidence Index | -30.60 | -30 | 03:00 |
| Unemployment Benefit Claims | -61,300 | - | 07:00 |
| Headline Unemployment Rate | 6.20 | 6.20 | 05:00 |
| Business Confidence Index | 91.90 | - | 07:00 |
| Consumer Confidence Index | 91.20 | - | 07:00 |
| Business Confidence Index | -1.60 | - | 07:00 |
| GDP Growth Quarter-over-Quarter Preliminary | 0 | - | 02:30 |
- German 10-year Bund yield fell 5 bp to 3.39% while the 2-year eased 9 bp to 3.02% on safe-haven flows.
- Euro Stoxx 50 declined 0.31% and DAX dropped 0.75% as French fiscal concerns weighed on sentiment.
- EUR/USD held near 1.12 after modest gains, supported by lower German yields and steady ECB policy expectations.
Yesterday's Recap
European equities closed lower on Monday with the Euro Stoxx 50 off 0.31%, DAX down 0.75% and CAC 40 slipping 0.36%. German Bund yields declined sharply as investors sought safety amid renewed focus on French debt sustainability. The 2-year Bund yield fell 9 bp to 3.02% and the 10-year eased 5 bp to 3.39%.
EUR/USD edged up 0.02% to 1.12 while EUR/GBP rose 0.18%. No high-impact Eurozone data releases occurred on the session. Market commentary highlighted political paralysis in France and questions over whether ECB tools could contain any spillover.
Brent crude fell more than 6% while gold advanced 0.48%. Growth momentum remains uneven across the currency bloc with France showing clear signs of slowdown while Germany and Spain continue to post steadier readings. Inflation at 3.80% year-over-year still exceeds the ECB’s target and keeps real yields elevated.
Unemployment across the Eurozone stands at 6.40%, providing some buffer against rapid policy easing.
The Day Ahead
Germany’s Ifo Business Climate for October is due at 05:00 ET and is expected to edge lower to 89.8 from 89.9. France will release its Consumer Confidence Index early Tuesday followed by Spain’s headline unemployment rate. Later in the week attention turns to Germany’s GfK Consumer Confidence, French unemployment claims and preliminary French GDP and inflation prints.
Italy and Spain will also publish business and consumer confidence readings. Markets will monitor any comments from ECB speakers for signals on how the central bank views French fiscal risks. Fiscal slippage in France has raised questions about debt dynamics and potential contagion to peripheral spreads.
Policymakers in Berlin are also weighing measures to protect domestic refining capacity amid high energy costs.
Other Economic Notes
Growth momentum remains uneven across the currency bloc with France showing clear signs of slowdown while Germany and Spain continue to post steadier readings. Inflation at 3.80% year-over-year still exceeds the ECB’s target and keeps real yields elevated. ↓ p.2