Eurozone Macro Daily(Beta Mode)
French Debt Worries Shadow ECB Hold
Market Snapshot
| Asset | Level | Change |
|---|---|---|
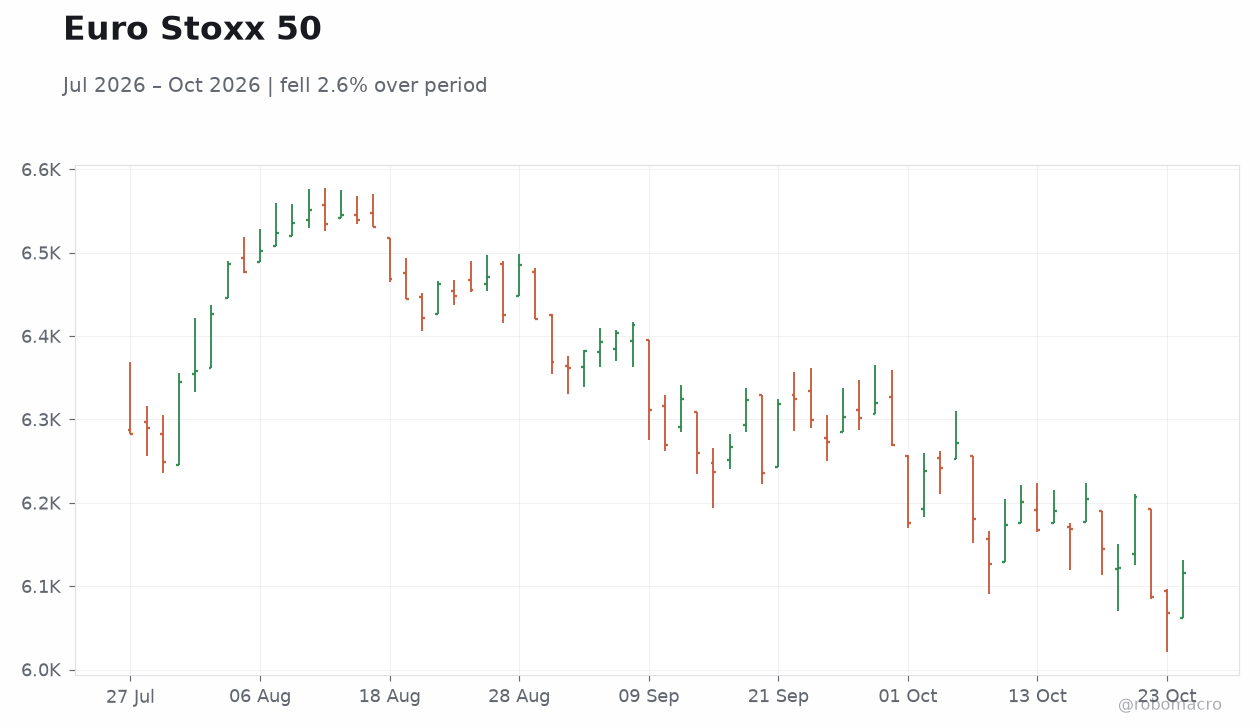
| Euro Stoxx 50 | 6,116.23 | +0.79% |
| DAX | 25,181.65 | -0.75% |
| CAC 40 | 7,847.32 | +0.83% |
| EUR/USD | 1.12 | -0.41% |
| EUR/GBP | 0.84 | -0.13% |
| EUR/JPY | 176.01 | +0.05% |
| Gold | 4,025.90 | -0.31% |
| Brent Crude | 109.68 | -5.29% |
| Bitcoin | 79,631.89 | -0.49% |
| German 2Y Bund | 3.08% | +6 bp |
| German 10Y Bund | 3.40% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Ifo Business Climate | 89.90 | 90 | 90.20 |
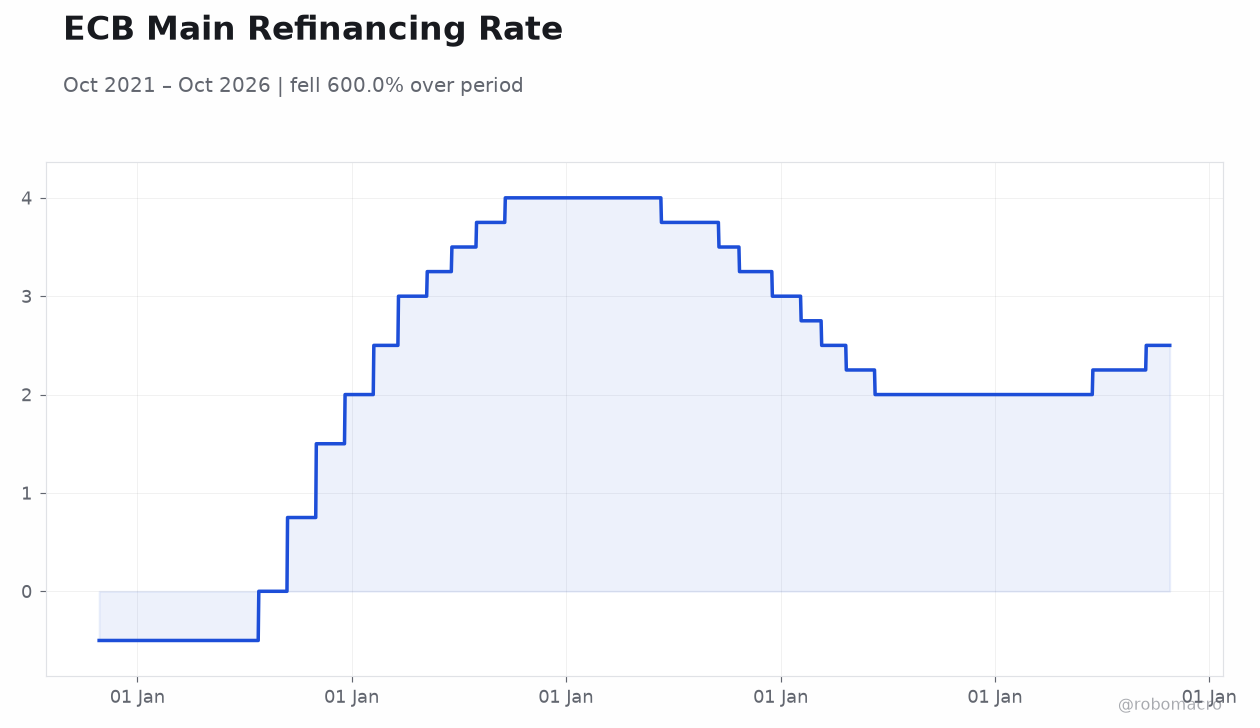
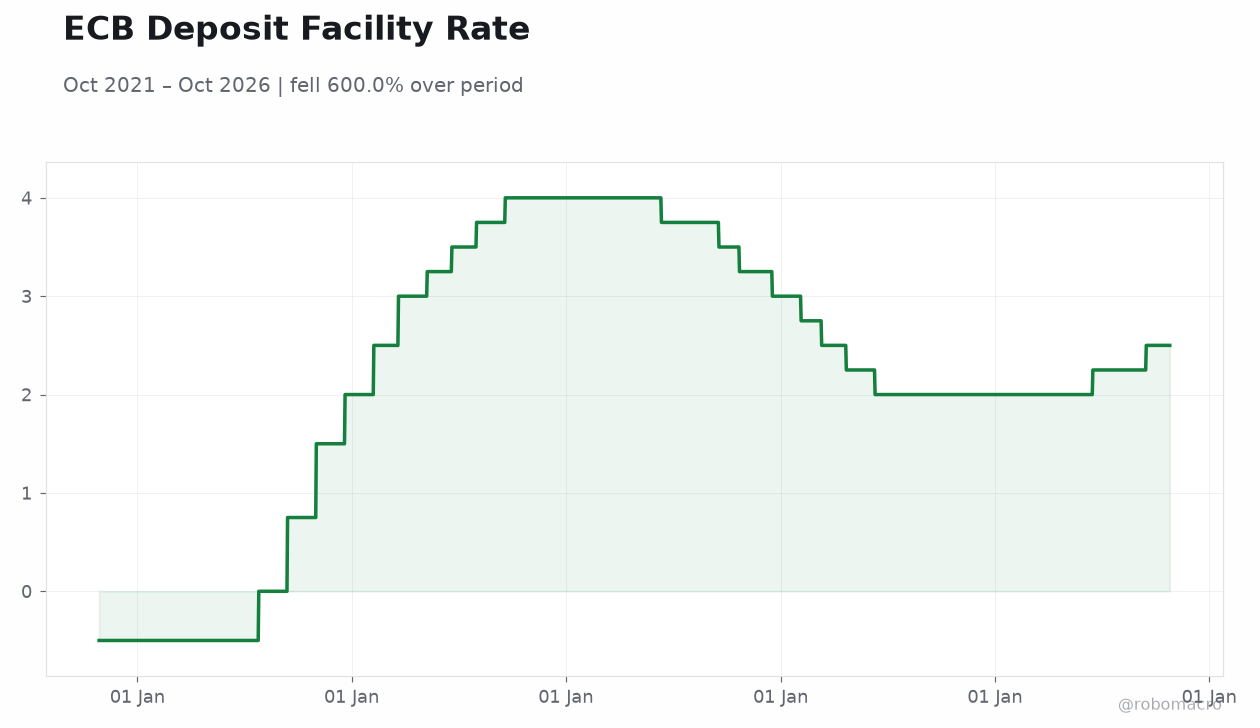
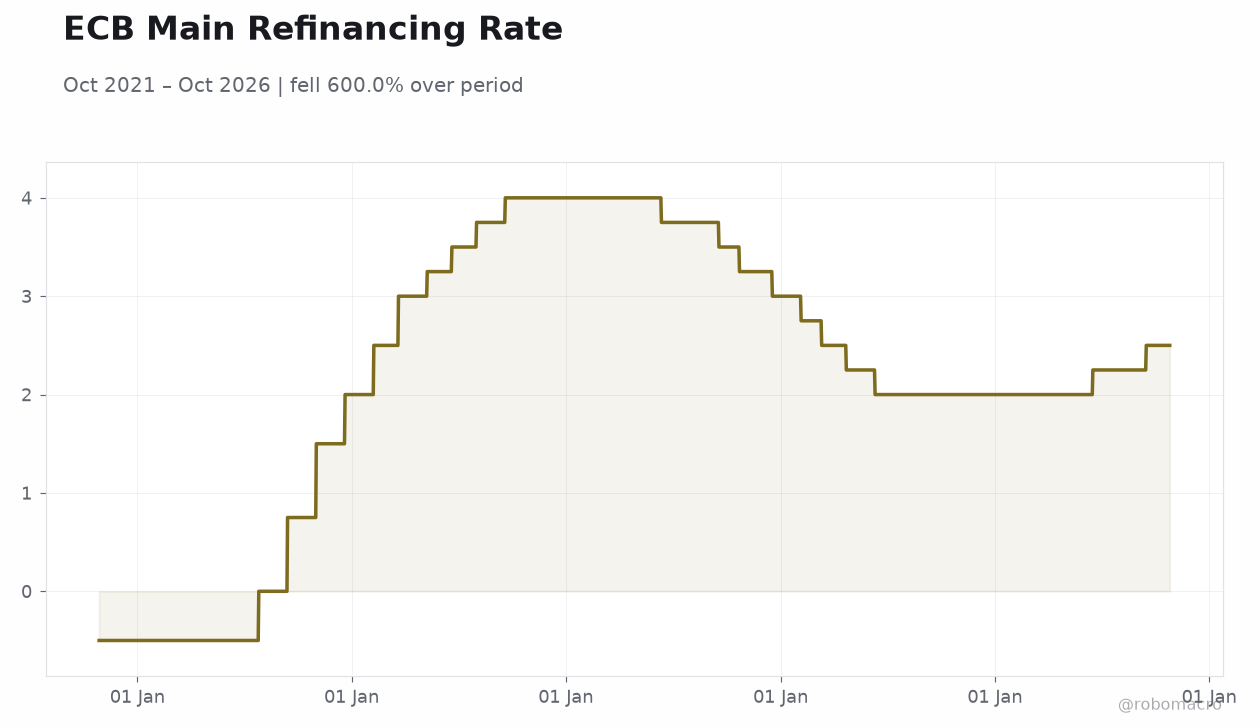
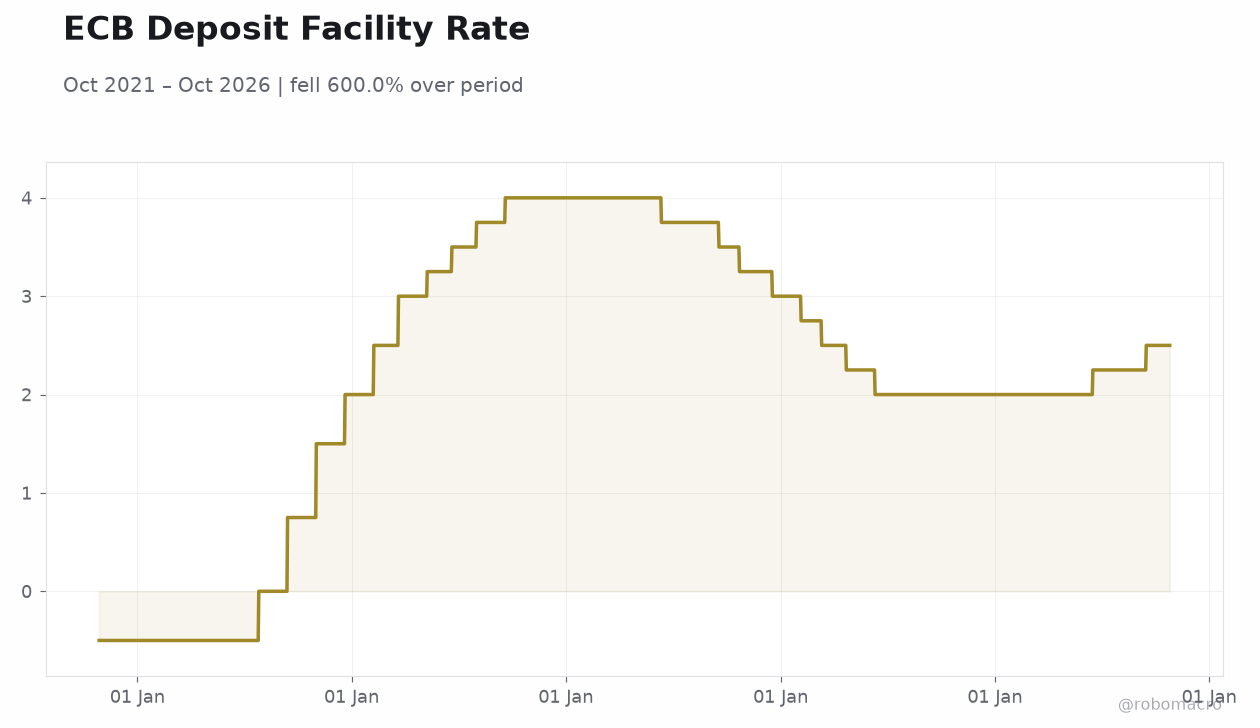 ECB Deposit Facility Rate | Type: macro_line | ECB Deposit Facility Rate: 2.5 (2026-10-26) | Range: -0.5–4 | Trend(5pt): -0.5,2,4,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Consumer Confidence Index | 86 | - | 03:45 |
| Headline Unemployment Rate | 9.87 | - | 04:00 |
| GFK Consumer Confidence Index | -30.60 | -31 | 03:00 |
| Unemployment Benefit Claims | -61,300 | - | 07:00 |
| Headline Unemployment Rate | 6.20 | 6.20 | 05:00 |
| Business Confidence Index | 91.90 | - | 07:00 |
| Consumer Confidence Index | 91.20 | - | 07:00 |
| Business Confidence Index | -1.60 | - | 07:00 |
| GDP Growth Quarter-over-Quarter Preliminary | 0 | - | 02:30 |
| GDP Growth Year-over-Year Preliminary | 0.50 | - | 02:30 |
- German Ifo Business Climate beat expectations at 90.2, signaling modest improvement in business sentiment.
- German 10-year Bund yields rose 4 bp to 3.40% amid French fiscal concerns and broader eurozone yield pressure.
- Euro Stoxx 50 advanced 0.79% while EUR/USD fell 0.41% to 1.12 ahead of the ECB decision.
Yesterday's Recap
German Ifo Business Climate printed at 90.2, above the 90.0 consensus and prior 89.9, reflecting a slight lift in German business conditions. Equity markets showed mixed performance with Euro Stoxx 50 rising 0.79% to 6,116.23 while the DAX declined 0.75% to 25,181.65 and CAC 40 gained 0.83% to 7,847.32. German 2-year Bund yields climbed 6 bp to 3.08% and the 10-year yield increased 4 bp to 3.40%, driven by French debt concerns.
EUR/USD weakened 0.41% to 1.12 and EUR/GBP slipped 0.13% to 0.84. Brent crude fell sharply 5.29% to 109.68, adding to downside pressure on energy-sensitive eurozone assets. Overall market moves reflected caution ahead of the ECB meeting amid persistent French fiscal risks.
Eurozone CPI stands at 3.80% year-over-year and unemployment at 6.40%, underscoring sticky price pressures even as growth cools.
The Day Ahead
France will release its Consumer Confidence Index at 03:45 ET followed by Spain’s Headline Unemployment Rate at 04:00 ET. Germany’s GfK Consumer Confidence Index is due at 03:00 ET on 28 October with a consensus of -31. Later in the week France reports preliminary GDP growth and inflation figures on 30 October while Spain releases its GDP flash estimates.
Italy will publish its Headline Unemployment Rate and confidence indices on 29 October. Markets will also monitor any additional comments from ECB officials ahead of the 29 October policy decision. Energy price swings and French bond-market stress remain key variables for positioning.
Other Economic Notes
Eurozone CPI remains at 3.80% year-over-year while unemployment stands at 6.40%, indicating persistent price pressures despite cooling growth. French debt market stress has pushed yields higher and raised questions about fiscal sustainability relative to Italy. Member states including Germany and Spain face divergent growth trajectories that complicate uniform ECB policy responses.
Energy price volatility, highlighted by the sharp drop in Brent, adds uncertainty to inflation forecasts across the bloc. Policymakers continue to balance these risks against the 2.50% deposit rate level. Divergent national outlooks increase the chance that any future easing path will remain gradual and data-dependent.