Eurozone Macro Daily(Beta Mode)
ECB Holds as Lagarde Exits, France GDP Eyed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Euro Stoxx 50 | 6,207.07 | +0.64% |
| DAX | 26,039.68 | +1.31% |
| CAC 40 | 7,970.00 | +1.05% |
| EUR/USD | 1.12 | +0.36% |
| EUR/GBP | 0.84 | -0.14% |
| EUR/JPY | 176.06 | -0.00% |
| Gold | 4,031.40 | -0.50% |
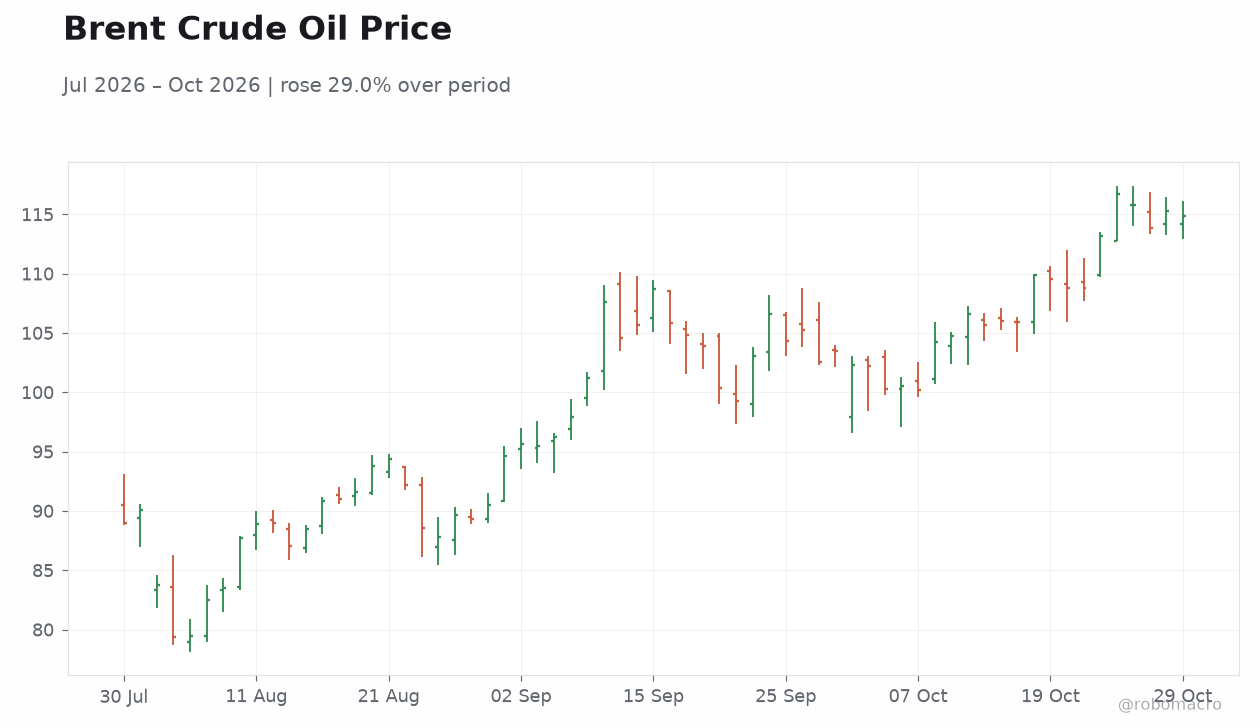
| Brent Crude | 114.88 | -0.38% |
| Bitcoin | 77,812.98 | -4.25% |
| German 2Y Bund | 3.07% | -1 bp |
| German 10Y Bund | 3.39% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Ifo Business Climate | 89.90 | 90 | 90.20 |
| Consumer Confidence Index | 85 | 85 | 80 |
| Headline Unemployment Rate | 9.87 | 9.90 | 10.18 |
| GFK Consumer Confidence Index | -30.60 | -30.90 | -30.80 |
| Unemployment Benefit Claims | -61,300 | - | 110,800 |
| Headline Unemployment Rate | 6.30 | 6.20 | 6.30 |
| Business Confidence Index | 91.90 | 92 | 91.90 |
| Consumer Confidence Index | 91.20 | 90.90 | 90.30 |
| Business Confidence Index | -1.60 | - | - |
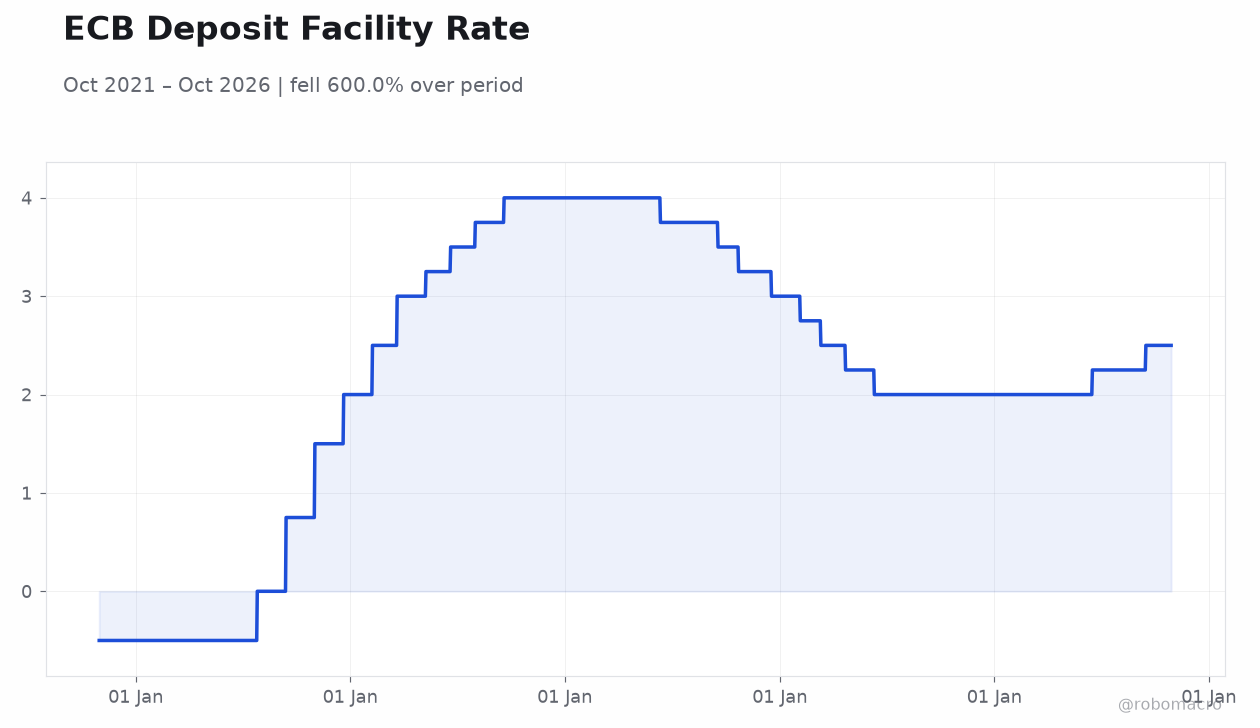
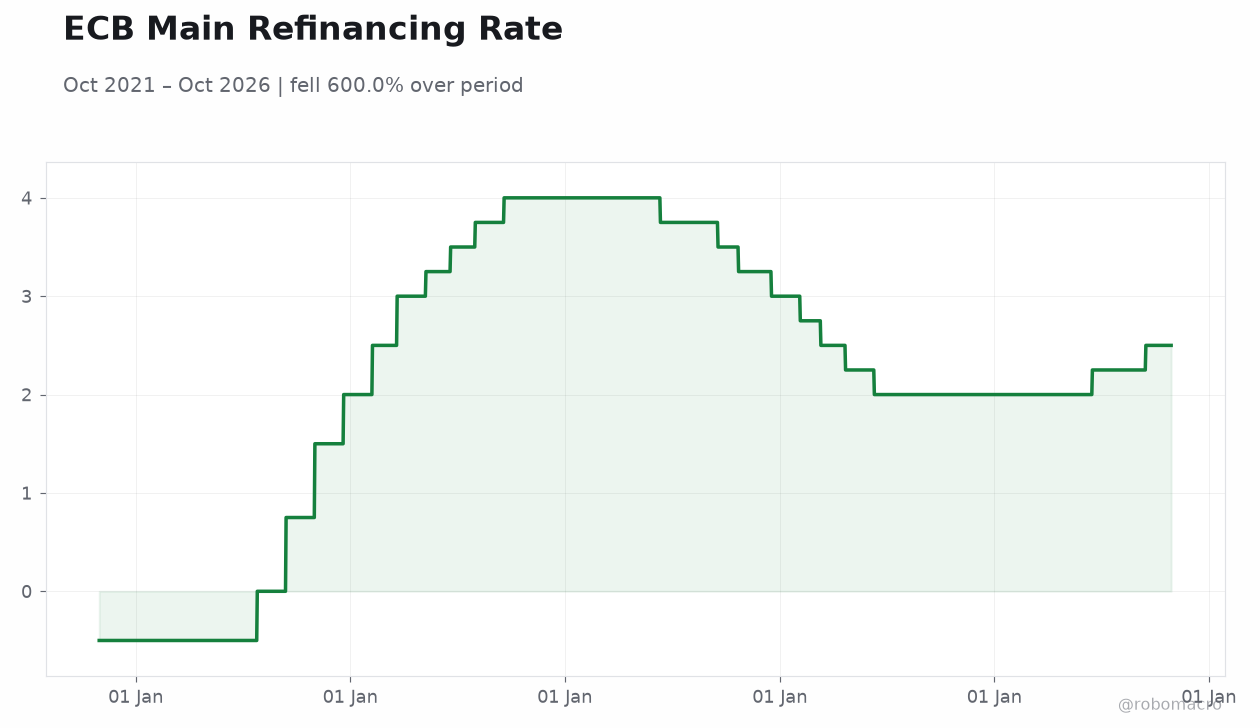
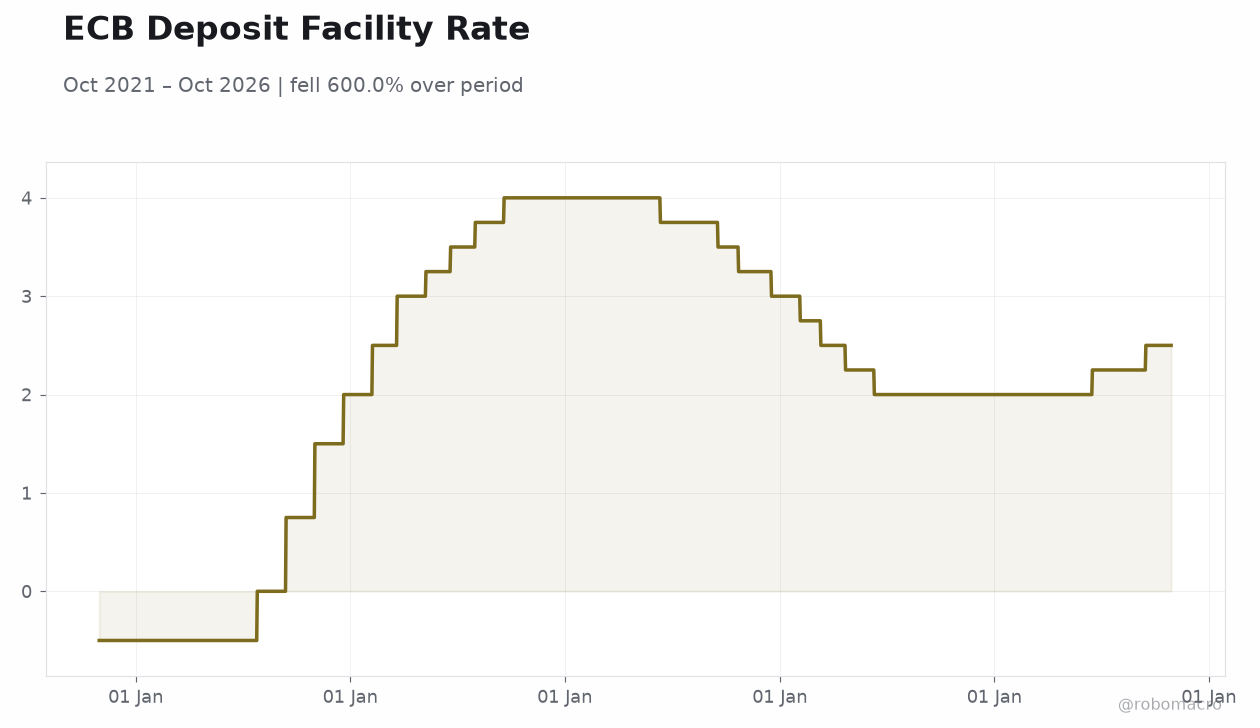
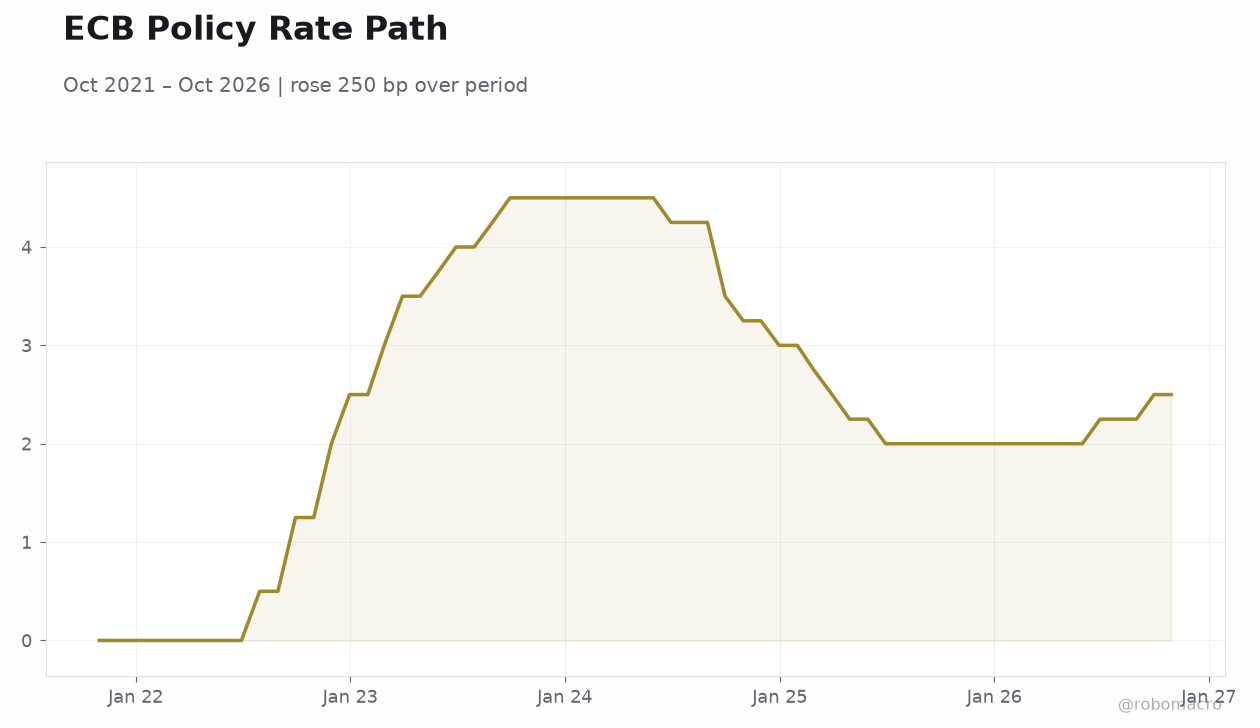 ECB Policy Rate Path | Type: macro_line | Policy rate %: 2.5 (2026-10-29) | Range: 0–4.5 | Trend(5pt): 0,2.5,4.5,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| GDP Growth Quarter-over-Quarter Preliminary | 0 | 0.10 | 02:30 |
| GDP Growth Year-over-Year Preliminary | 0.50 | 0.30 | 02:30 |
| Inflation Rate Year-over-Year Preliminary | 3.10 | 3.20 | 03:45 |
| Inflation Rate Month-over-Month Preliminary | -0.30 | 0.20 | 03:45 |
| GDP Growth Quarter-over-Quarter Flash Estimate | 0.70 | 0.60 | 04:00 |
| GDP Growth Year-over-Year Flash Estimate | 2.60 | 2.70 | 04:00 |
| Inflation Rate Month-over-Month Preliminary | 0.30 | 0.60 | 04:00 |
| Inflation Rate Year-over-Year Preliminary | 4.90 | 4.90 | 04:00 |
| GDP Growth Quarter-over-Quarter Flash Estimate | 0.60 | - | 04:30 |
| GDP Growth Year-over-Year Flash Estimate | 1.60 | - | 04:30 |
- ECB held the deposit rate at 2.50% on 29 October; Lagarde announced early departure, triggering succession race
- French Q3 GDP and October CPI flash prints due today; consensus sees +0.1% q/q growth and 3.2% inflation
- Bunds edged lower in yield (10Y at 3.39%, -1 bp); DAX outperformed (+1.31%) as equities rallied into the ECB
Yesterday's Recap
The ECB's 29 October decision left the deposit rate unchanged at 2.50%, with markets parsing the statement for signals on France and energy risks. German Ifo Business Climate printed at 90.2 on 26 October, marginally above the 90.0 consensus and prior 89.9, offering a modest upside surprise. French Consumer Confidence fell sharply to 80 versus 85 expected and previously, a notable downside miss.
Spanish headline unemployment rose to 10.18% from 9.87%, above the 9.9% consensus. German GFK Consumer Confidence came in at -30.8, close to the -30.9 consensus. Italian unemployment held at 6.3% (consensus 6.2%), while Italian business confidence was steady at 91.9 and consumer confidence slipped to 90.3.
French unemployment benefit claims swung to +110,800 from -61,300 previously. Markets rallied: the DAX rose 1.31%, CAC 40 gained 1.05%, and Euro Stoxx 50 added 0.64%, while EUR/USD firmed 0.36% to 1.12 and the 10-year Bund yield eased 1 bp to 3.39%.
The Day Ahead
France releases Q3 GDP preliminary estimates at 02:30 ET, with consensus at +0.1% q/q (prior 0.0%) and +0.3% y/y (prior 0.5%). French October CPI flash follows at 03:45 ET, consensus 3.2% y/y (prior 3.1%) and +0.2% m/m (prior -0.3%). Spain publishes Q3 GDP flash at 04:00 ET, consensus +0.6% q/q (prior 0.7%) and +2.7% y/y (prior 2.6%).
These prints will be scrutinised for divergence between the eurozone's two largest economies, particularly given France's fiscal and political backdrop. Markets will also watch for any ECB commentary following Lagarde's announced early exit.
Other Economic Notes
Eurozone sentiment weakened in October with price expectations ticking higher, per survey data, complicating the ECB's disinflation narrative as headline CPI sits at 3.80% (September). France has reclaimed the title of Europe's highest tax burden at 46% of GDP, with national debt continuing to grow amid street protests — a fiscal overhang that keeps OAT spreads in focus. Ireland's economy surged again, providing an outsized boost to aggregate eurozone activity.
Italian confidence indicators were mixed, with consumer sentiment softening to 90.3 while business confidence held at 91.9. The Lagarde succession race adds a layer of institutional uncertainty just as France heads toward elections.