Eurozone Macro Daily(Beta Mode)
Bunds Bid as France Slips, Gas Risk Builds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Euro Stoxx 50 | 6,131.31 | -1.22% |
| DAX | 25,818.21 | -0.85% |
| CAC 40 | 7,969.42 | -0.01% |
| EUR/USD | 1.12 | -0.03% |
| EUR/GBP | 0.83 | -0.17% |
| EUR/JPY | 176.42 | -0.03% |
| Gold | 3,898.90 | -3.29% |
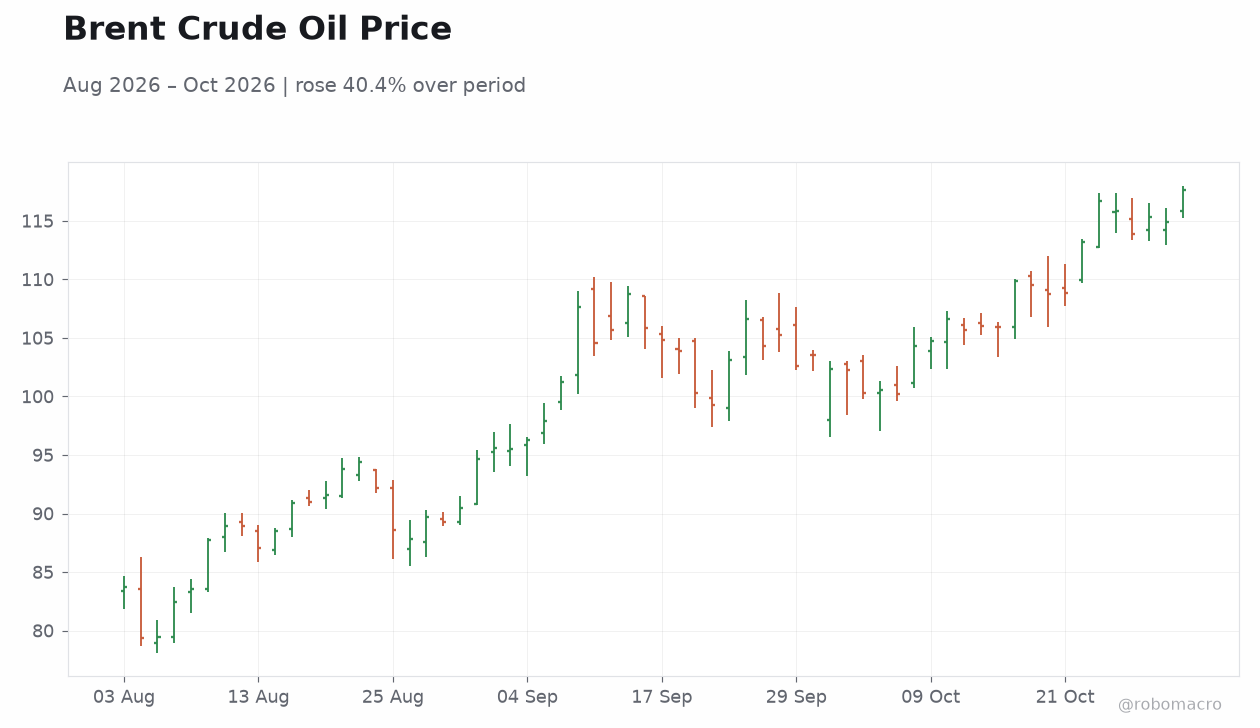
| Brent Crude | 117.64 | +2.40% |
| Bitcoin | 78,274.01 | +1.08% |
| German 2Y Bund | 3.06% | +4 bp |
| German 10Y Bund | 3.40% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
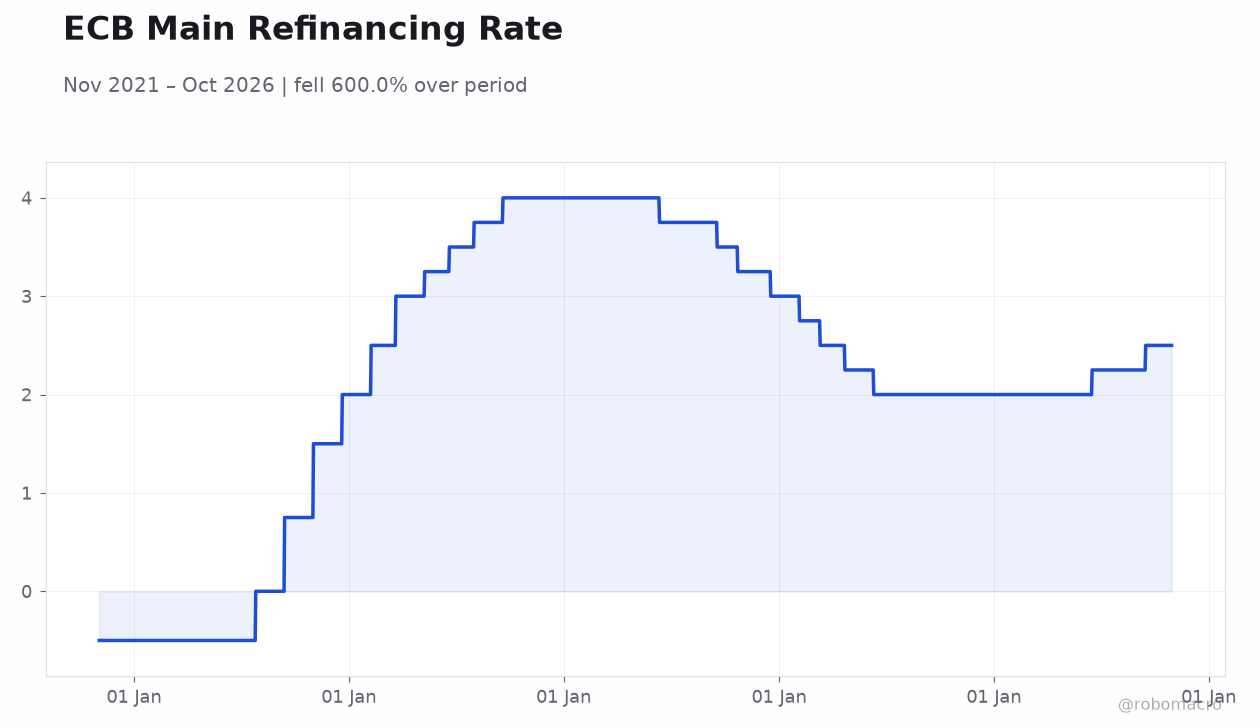
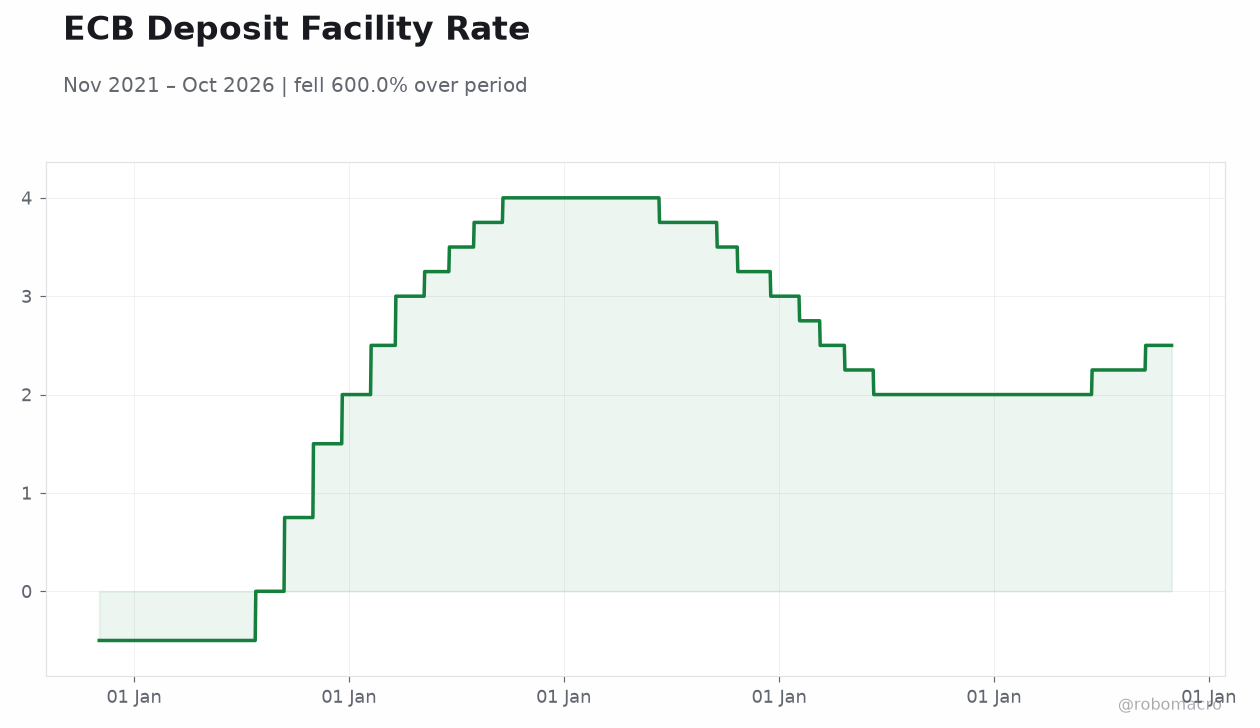
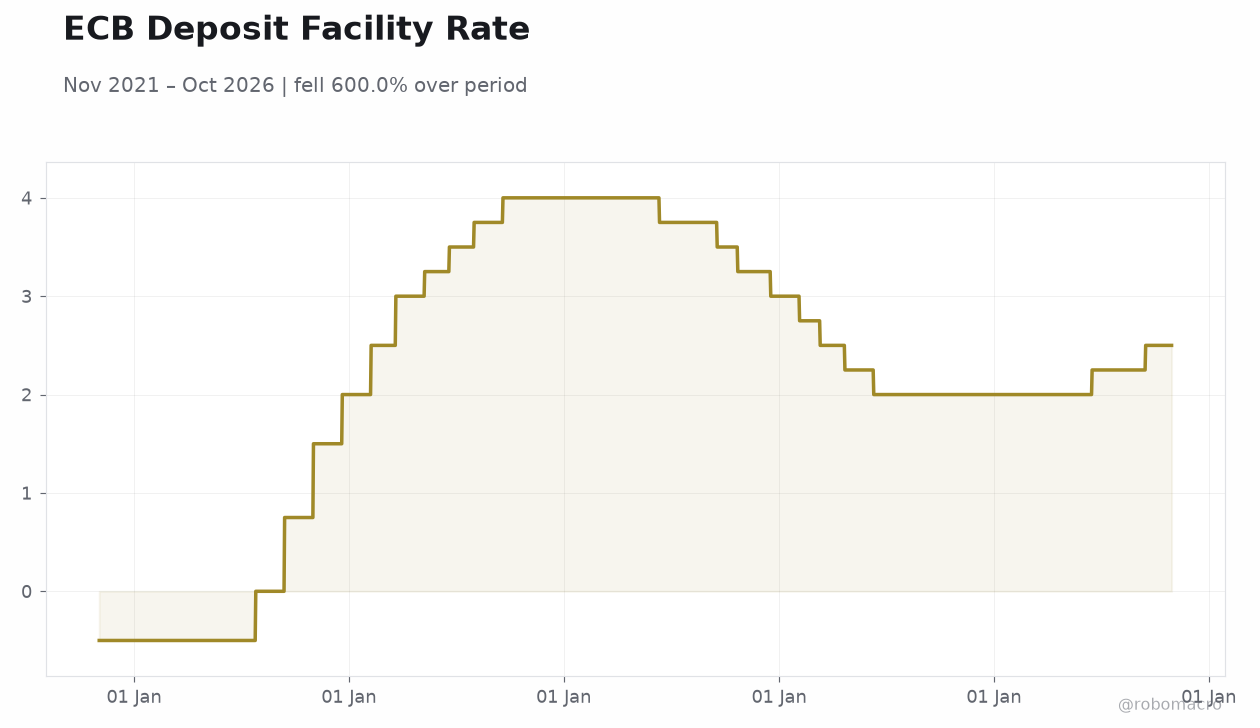 ECB Deposit Facility Rate | Type: macro_line | ECB Deposit Facility Rate: 2.5 (2026-10-30) | Range: -0.5–4 | Trend(5pt): -0.5,2,4,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Retail Sales Month-over-Month | 1.30 | 0.50 | 02:00 |
| Retail Sales Year-over-Year | -0.40 | - | 02:00 |
| S&P Global Manufacturing PMI Index | 51 | 50.60 | 03:15 |
| S&P Global Manufacturing PMI Index | 50.40 | 49.70 | 03:45 |
- German Q3 GDP unexpectedly grew 0.2% while France contracted 0.1%, deepening the euro-area growth divergence and pushing Fitch to a negative outlook on French debt.
- Bunds rallied on Friday with the 10-year yield easing 2 bp to 3.40% while the 2-year rose 4 bp to 3.06%, flattening the curve as markets weigh ECB patience against fiscal stress.
- German retail sales and Spanish/Italian manufacturing PMIs headline today's calendar, with Brent above $117 and Germany missing its winter gas storage target keeping energy risk elevated.
Yesterday's Recap
Friday's session closed a week defined by diverging euro-area growth. German Q3 GDP rose 0.2% q/q, beating expectations on state spending despite summer drought and Iran-war disruptions, while French GDP fell 0.1% after prior stagnation, leaving France near recession amid budget deadlock. Fitch placed France's rating on negative outlook in an unscheduled move, underscoring the speed of fiscal deterioration.
Spanish inflation held at a three-year high ahead of elections, and the Banque de France's Deputy Governor estimated climate change is shaving 0.1 pp off French quarterly growth. Markets reflected the strain: the Euro Stoxx 50 fell 1.22% to 6,131.31, the DAX dropped 0.85% to 25,818.21, and the CAC 40 was flat at 7,969.42. EUR/USD held near 1.12 (-0.03%) and EUR/GBP slipped 0.17% to 0.83.
Bunds outperformed, with the 10-year yield easing 2 bp to 3.40% while the 2-year rose 4 bp to 3.06%.
The Day Ahead
Germany's September retail sales print at 02:00 ET is the first focus, with consensus at +0.5% m/m following August's +1.3%, and the y/y series due alongside it after the prior -0.4% reading. Spain's S&P Global manufacturing PMI follows at 03:15 ET, expected at 50.6 versus 51.0 previously, before Italy's PMI at 03:45 ET, where consensus of 49.7 from 50.4 would signal a return to contraction. These releases will test whether the periphery can offset the Franco-German divergence.
No major ECB speakers or Governing Council events are scheduled, leaving markets to trade the data and Friday's risk-off tone. Attention already turns toward the 3 December flash HICP and the 17 December ECB decision.
Other Economic Notes
Germany's failure to meet its winter gas storage target is a material risk: as the bloc's largest economy it will lean on spot purchases, potentially lifting prices for other EU members and complicating the inflation path already at 3.80% y/y. The ECB's latest survey flagged higher costs and wage pressure facing euro-area firms, suggesting services inflation will be sticky. ↓ p.2